 Andrew
General educational commentary only, generated automatically with AI. Not investment advice or a recommendation to buy, sell or hold any security. Capital is at risk.
Bank Earnings Beat but Fail to Lift Sentiment
U.S. stocks finished mixed on Tuesday, according to the news brief. The S&P 500 was nearly flat. The Nasdaq slipped 0.15%. The Dow fell 170 points. Major banks posted higher profits and revenue. Equities-trading revenue rose 39% on average. The Wall Street Journal reported that bank earnings did not excite investors. Strong results did not offset worries about rates and the economy. One reading is that good earnings alone may not change the mood while borrowing costs stay high.
CPI Report Is the Main Near-Term Test
The next big event is September CPI. CNBC reported that inflation data is expected to show price increases are accelerating. Economists expect a 0.6% monthly rise and 3.6% annual inflation, per the news brief. Several Fed officials say another rate hike this year may be appropriate. Reuters reported that Fed's Collins sees another hike on the table before the end of 2026. New York Fed President John Williams does not expect further increases in 2027. This mix leaves rate expectations uncertain. A hotter CPI reading could reinforce hike expectations and pressure stocks and bonds.
Chip and AI Shares Face a Harder Stretch
Chip shares came under pressure. MarketWatch described "AI fatigue" gripping the market and driving chip stocks toward their worst stretch in 16 months. Investors are questioning AI spending, financing risks and growth expectations. The news brief calls this a test of investor patience with the trade. This may suggest that the AI theme is being re-examined rather than abandoned. The source does not say how long the pressure may last.
Oil and China Data Add Cost Pressure
Middle East tensions are supporting oil-risk premiums. CNBC reported that oil rose amid growing tensions between Iran-backed Houthis and Saudi Arabia. Houthi threats against Saudi energy infrastructure could add pressure to energy prices. China's producer-price inflation accelerated to 4.5%, above expectations. CNBC noted this was the fastest pace since June 2022. Singapore's central bank unexpectedly held policy steady, which The Wall Street Journal described as a caution signal. Together these items point to renewed cost pressures outside the U.S.
Online Sentiment Splits between Index Hope and Stock Fatigue
Online sentiment comes from unverified posts by anonymous retail users. It may include rumour or speculation and has not been checked. At the theme level, posts describe a split mood. Some discuss index-level optimism around a cool CPI reading. Others describe fatigue with memory and high-beta themes. Fear/Greed was described near 50/100, neutral with a slight tilt toward greed. Posts also noted narrow leadership, with a few large caps holding up while small caps and equal-weight measures lagged. This is unconfirmed chatter, not institutional flow. One interpretation is that index-level hope and single-theme pessimism are running side by side.
Chart Screen Flags Dow Weakness on Several Measures
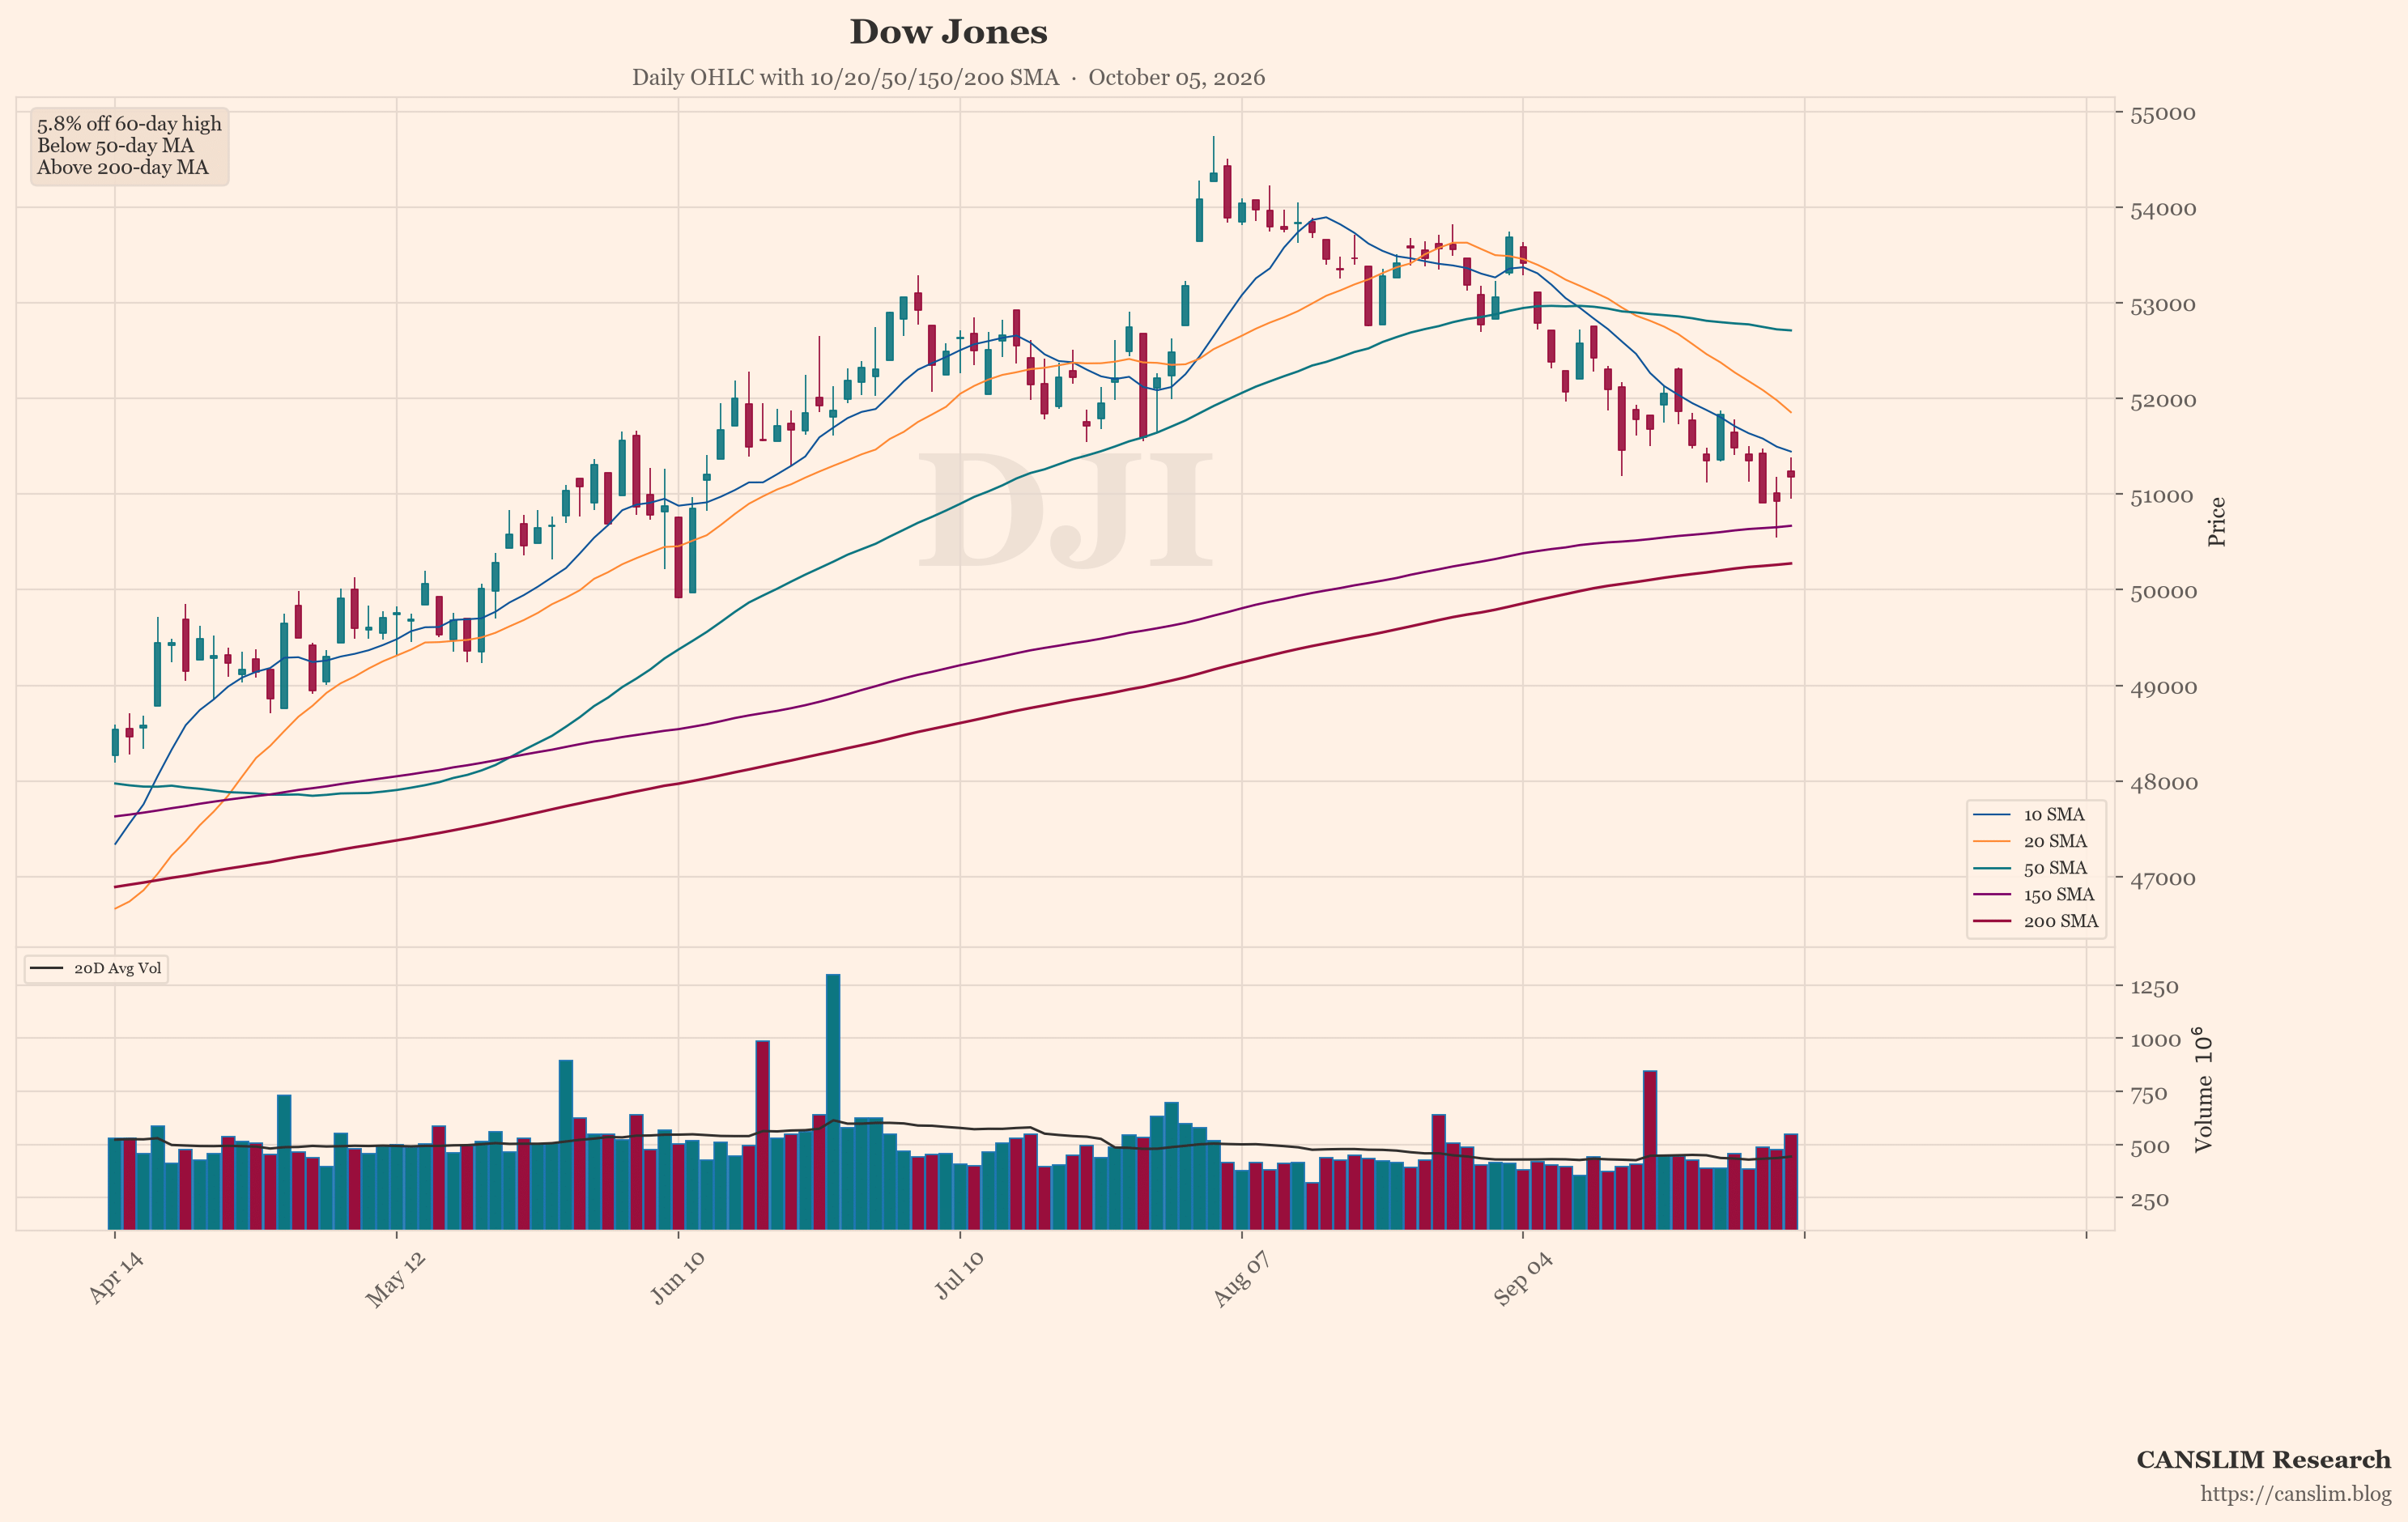
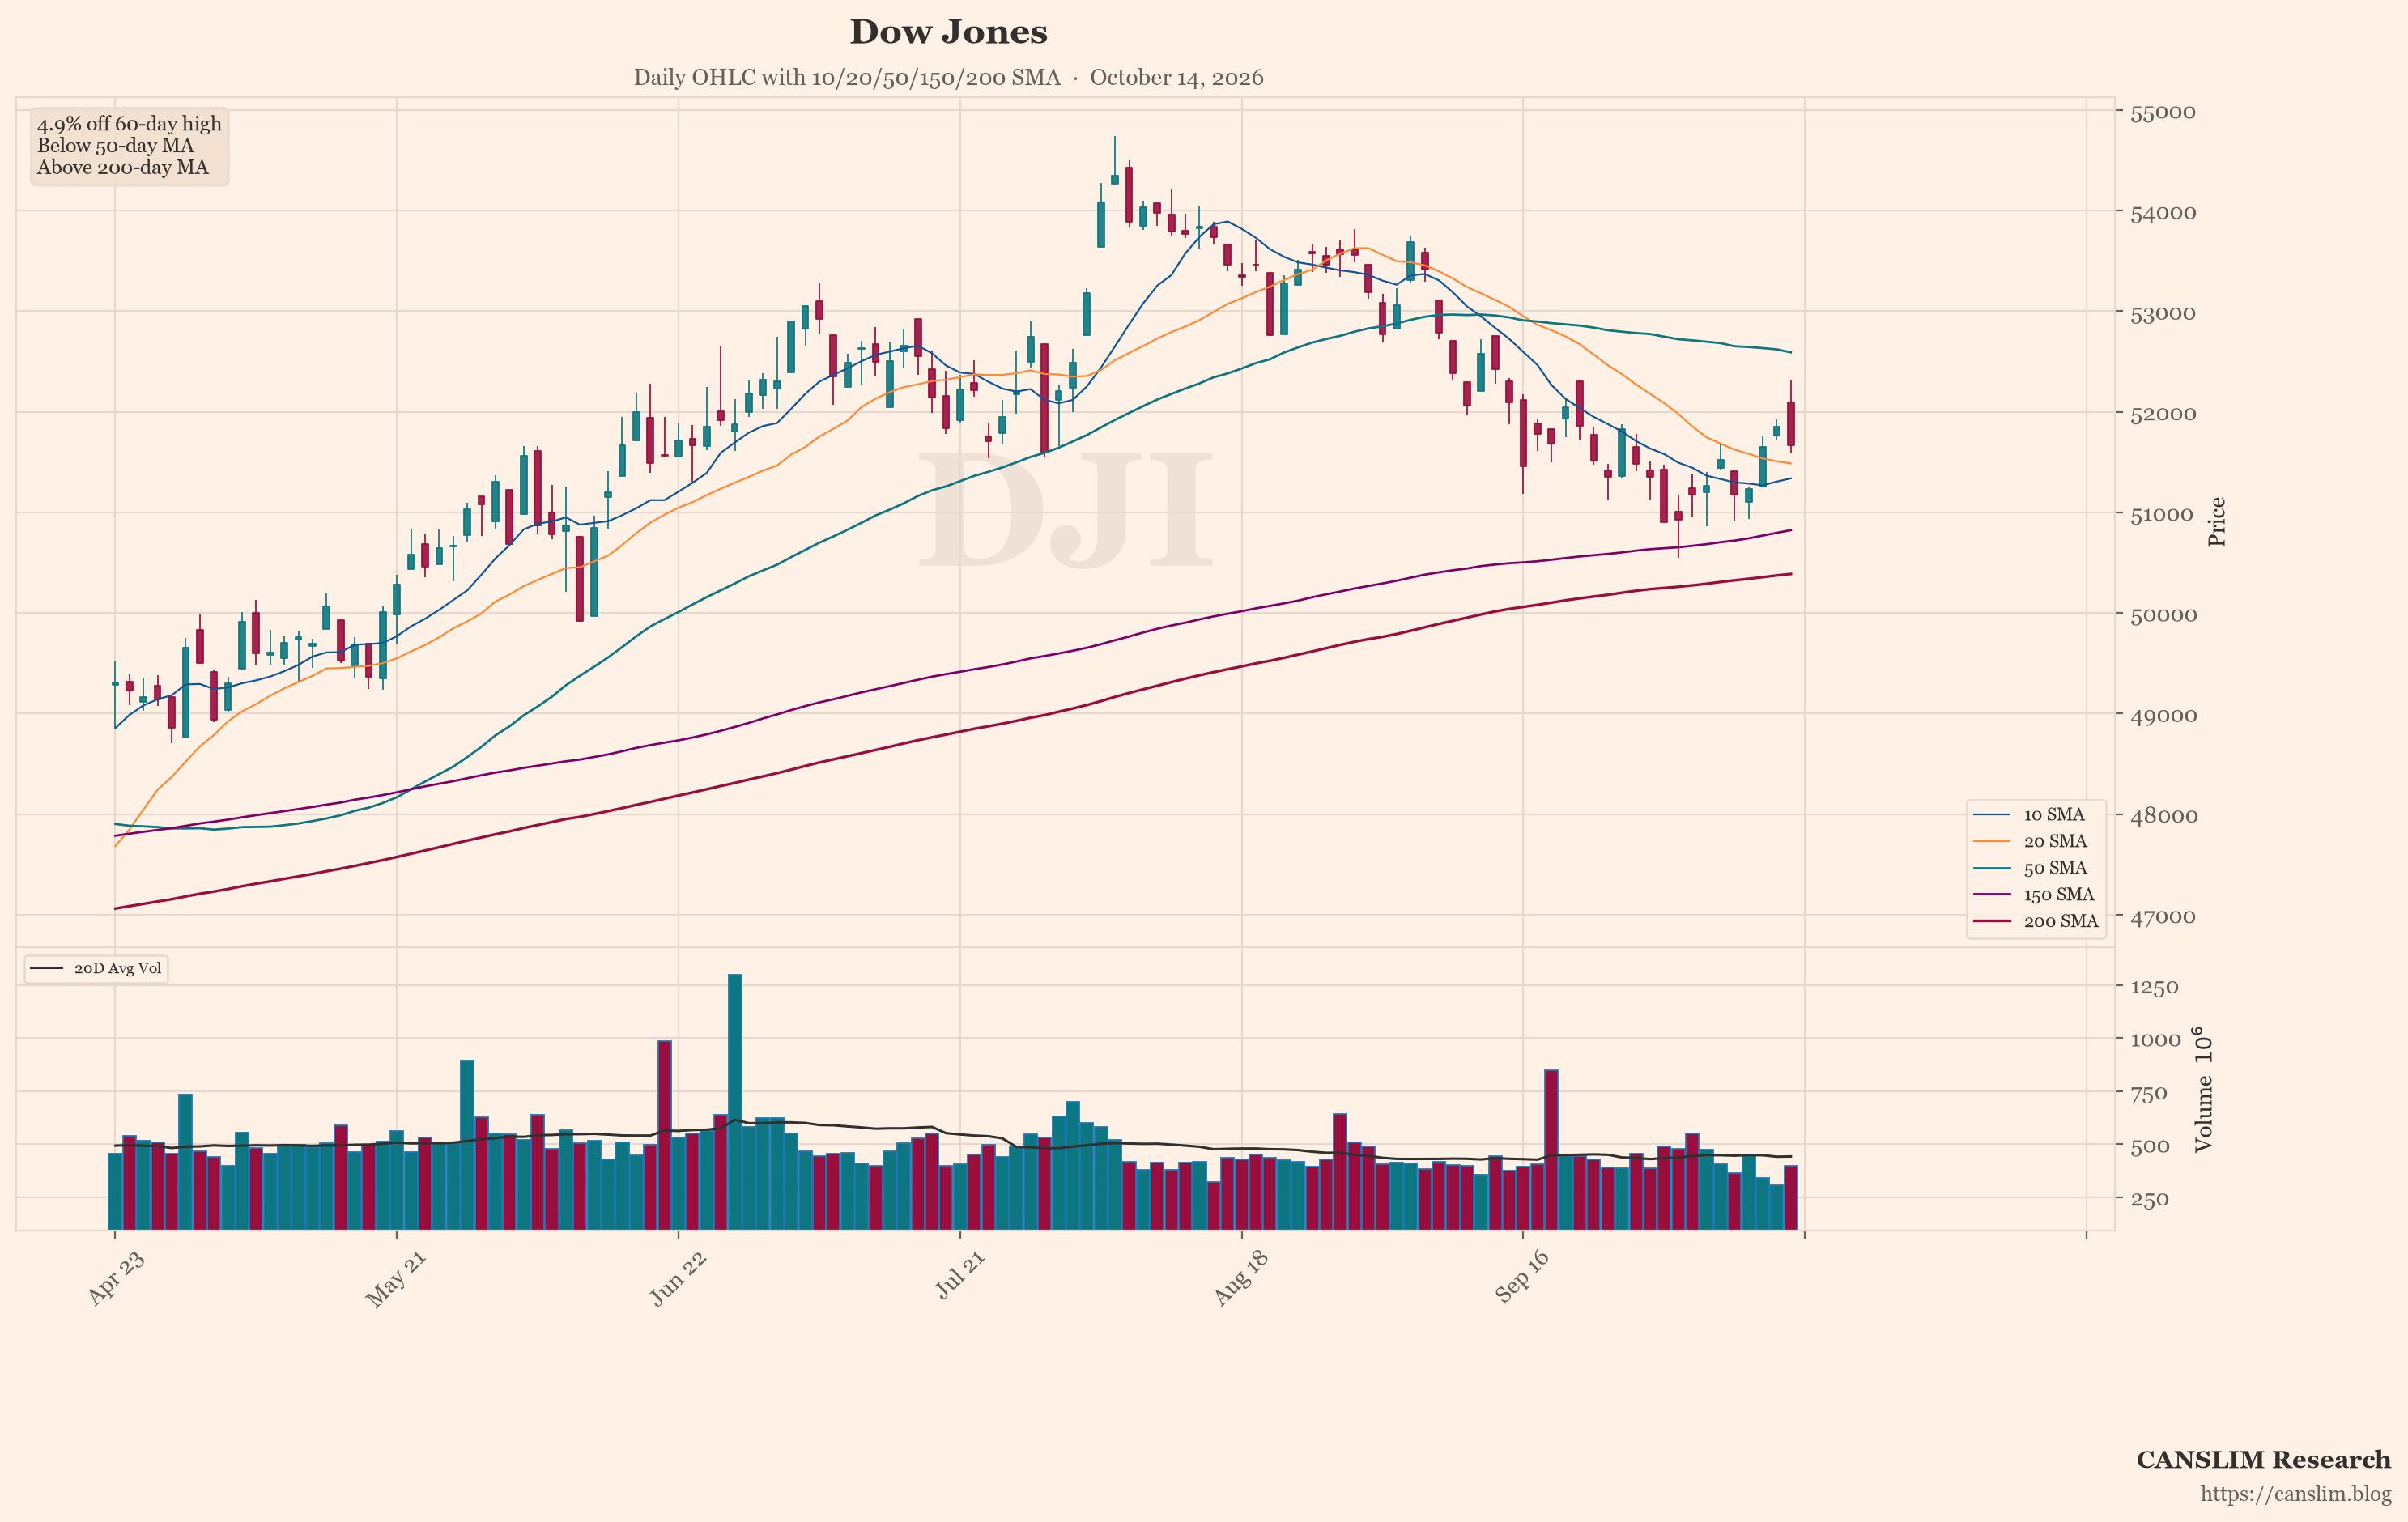
The featured chart shows the Dow Jones (^DJI). An automated technical screen picked it because, among the indices and stocks it checked, it showed the most weakness on a few measures. These include distance from its recent high, position versus its 50-day and 200-day moving averages, and down days on higher volume. This is one screen, not a full view of the market. Past price patterns do not predict future results. The screen is a description of recent price behaviour, not a signal about what comes next.
Mixed Conditions with Inflation and Rates Unresolved
Conditions look mixed. Bank profits grew, but investors did not respond strongly. Chip and AI shares weakened. Oil and China producer prices added cost pressure. The CPI report and the Fed's response remain open questions. Online sentiment is split and unverified. Breadth has been narrow, with large caps holding better than small caps. Risks include a hotter CPI reading, further rate-hike talk, energy escalation and continued pressure on AI-related shares. These factors could shift rate expectations and market leadership in ways that are not yet clear.
Sources: a third-party AI-generated market news summary, and an AI summary of unverified posts by anonymous retail users online. This article was written by an AI language model from those summaries and published automatically without human review. Updated 2026-10-14 14:00 HKT.
CANSLIM Research (canslim.blog) is an independent educational publisher. It is not licensed or registered as a broker, investment adviser, research analyst or asset manager in any jurisdiction. This article is general information for education only. It is not investment advice, a research report, an investment recommendation, or an offer or solicitation to buy or sell any security, and it does not consider any reader's objectives, financial situation or needs. No ticker, chart, heading or technical comment is a suggestion to buy, sell, hold or short. Figures come from third-party sources, are not independently verified, and may be incomplete, out of date or wrong. Online sentiment may include rumour, speculation or coordinated posting. Past performance and past price patterns do not predict future results. Investing involves risk, including the loss of capital. This article is not updated after publication. Laws differ by country; seek advice from a licensed professional in your jurisdiction before making any investment decision.
Discover more from CANSLIM Research
Subscribe to get the latest posts sent to your email.