Andrew@CANSLIM RESEARCH
Tech Holds the Line as the Dow Slips Again
The market enters a new week with a split personality. The S&P 500 fell just 0.08% last week. It sits only 1.9% below its record close. The Dow logged a third straight weekly loss. But the Nasdaq held up better. Large-cap tech and AI enthusiasm did the heavy lifting. That resilience is real. It also means the market leans on a narrow set of leaders. The Fed has resumed tightening. The 10-year Treasury yield is near 5%. Futures now price about two more quarter-point hikes by January 2027. Money is not cheap anymore.
Diesel at Record Highs Is the Story Nobody Can Ignore
Oil is above $100. Diesel just hit a record near $6.45 per gallon, up about 74% year over year. The bottleneck is not crude alone. Refineries are the chokepoint. The EIA expects distillate inventories to fall below 100 million barrels. They may stay under five-year lows for most of 2027. Why does this matter? Diesel moves freight, factories and food. Higher fuel costs feed straight into consumer prices. That makes the Fed's job harder. The online crowd talks about this constantly. Traders post $7 diesel signs in Indiana and $8 stations in California. One in nine French gas stations is out of fuel. Yet positioning is confused. Some bet on oil falling. Others call for $150 crude. Few have a clear plan.
The Online Crowd Sees a Bull Victory That Wasn't There
Friday felt like a win. Semiconductors ripped higher. SNDK closed at 1791.83, up 10.99%. AMAT rose 6.57%. MU gained 3.95% to 1015.53. AMD added 2.72%. NVDA rose 1.20%. But look closer. QQQ closed at 721.36, up only 0.62%. SPY fell 0.13% to 761.62. DIA dropped 0.48%. IWM lost 0.46%. Only tech won. The crowd noticed. Many said the late rally came from triple-witching options expiration, not real buying. That is the key behavior today: knowing the move is fake, but buying anyway. Sentiment sits in greed near 70/100. Price targets for SNDK jumped from 3000 to 5000+. Talk of SPY 800 or 900 floods the feed. Meanwhile, the cash camp grows louder. Some warn most individual stocks remain more than 30% below their highs.
Breadth Is Thin and the Leaders Know It
The headline indexes hide the damage. Several S&P 500 sectors sit in oversold territory. Leadership is concentrated in large-cap growth. META fell 2.49%. DELL dropped 3.30%. PANW lost 3.05%. BE sank 5.27%. This is not a broad advance. It is a narrow one. Growth investors should respect that. When breadth narrows, breakouts fail more often. Keep position sizes small. Watch for distribution days. The market can hold up on a few names, but it cannot run forever on five tickers.
Memory Chips Face a New Threat From China
China's CXMT says its fifth-generation DRAM platform entered mass production. That is a long-term risk for Samsung, SK Hynix and Micron. It will not hurt earnings this quarter. But it adds supply to a market that runs on pricing power. Watch MU earnings on September 30. The crowd treats it as a calendar anchor. Targets of 1100, 1200 and 1300 are common. Discipline matters more than targets now.
DRAM Chart Shows the Weakest Link
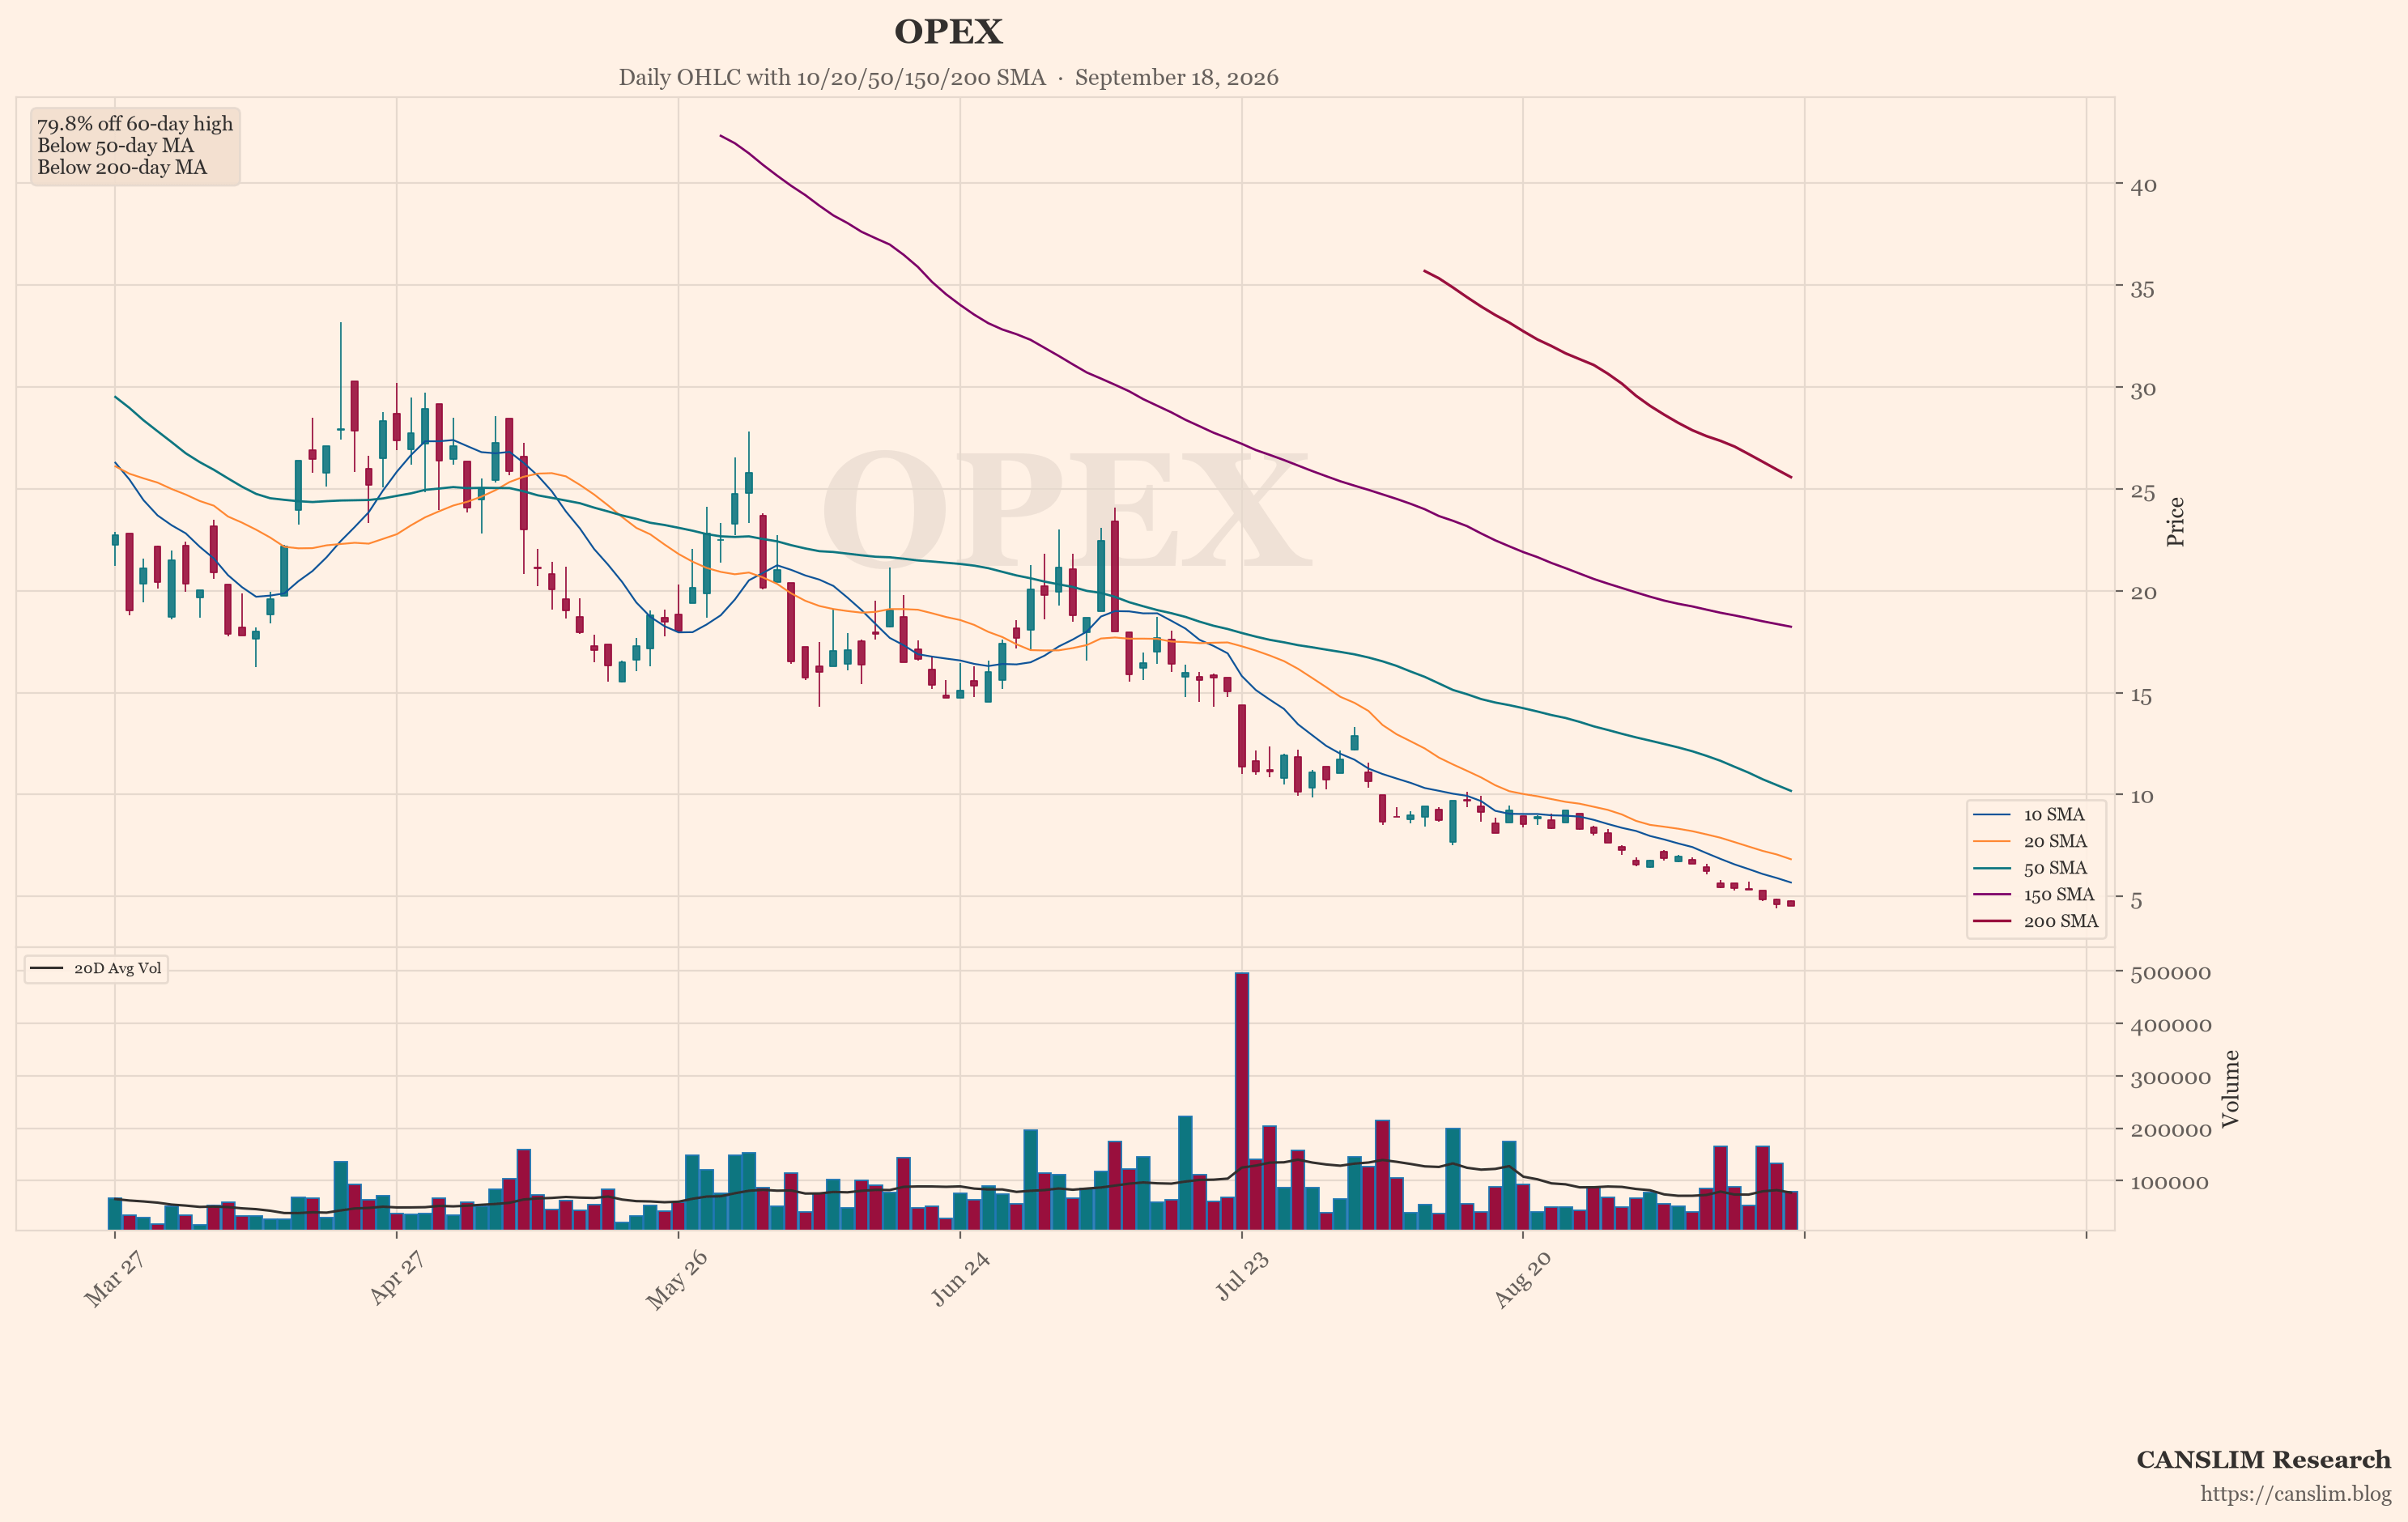
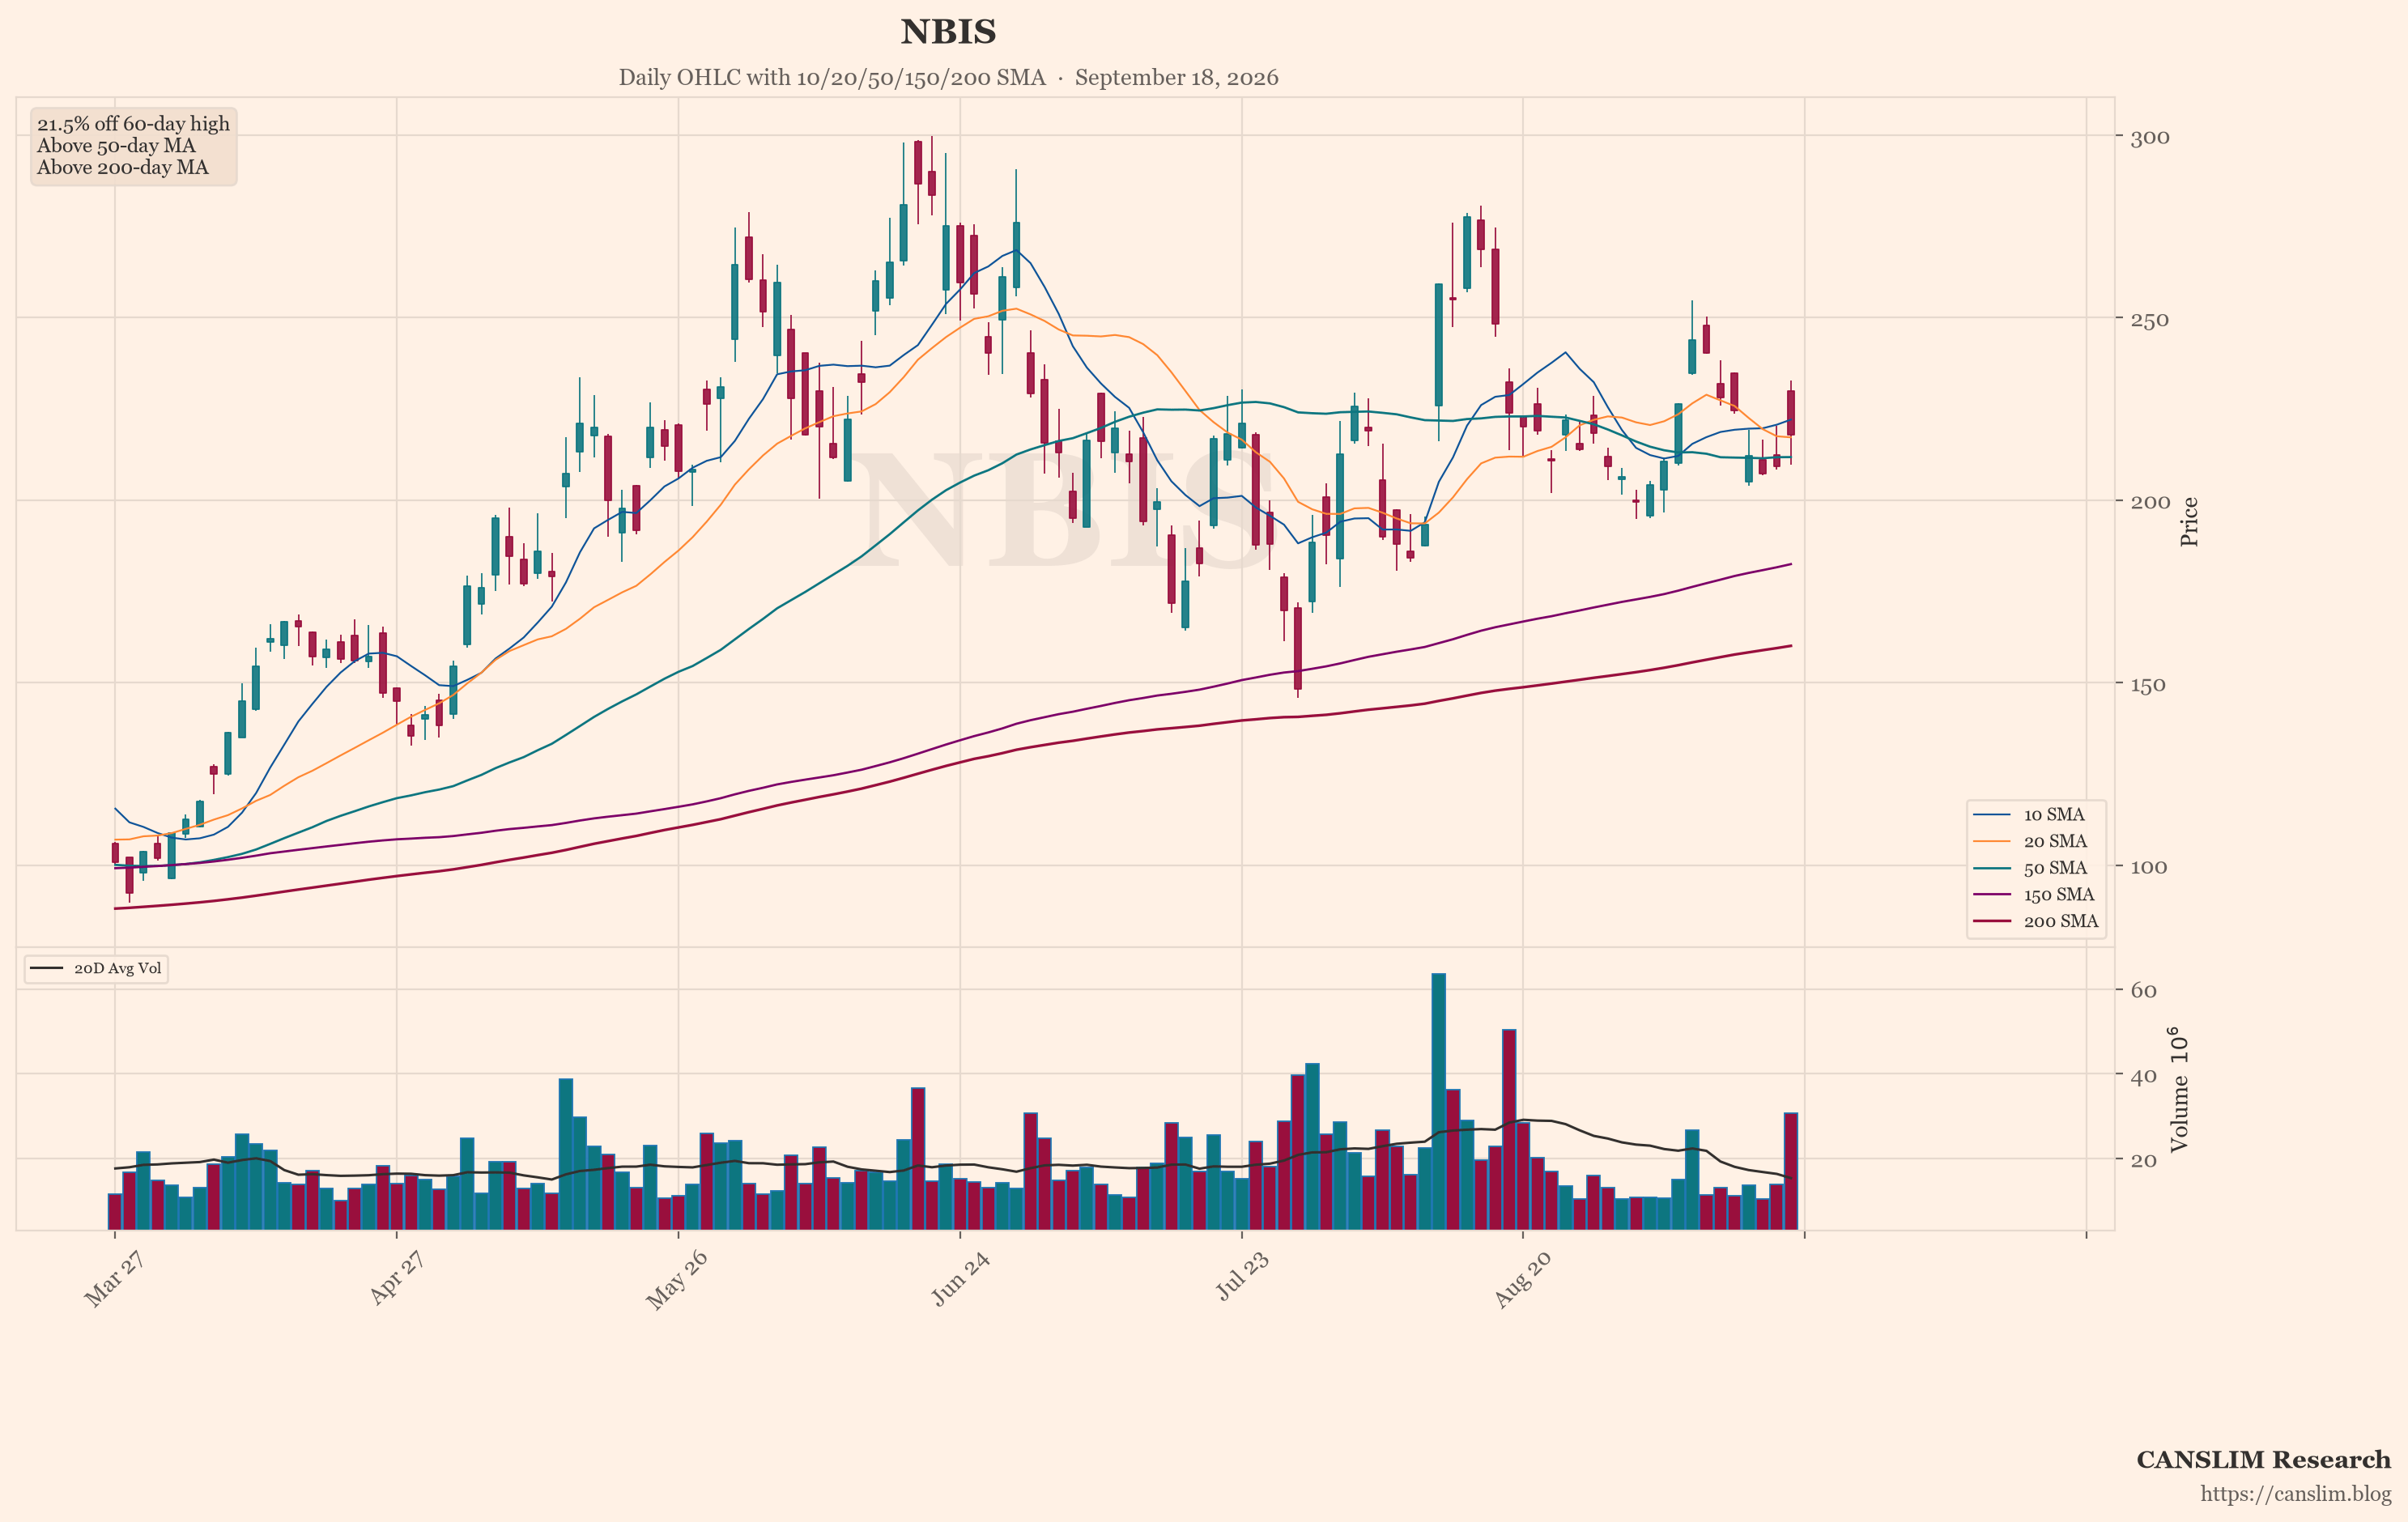
The featured chart, DRAM, shows the weakest technical pattern right now. That fits the story. Memory names carry the most hype and the most competitive risk. If DRAM cannot hold its base while MU and SNDK run, that is a warning. Weak charts in hot groups often break first.
Where This Leaves the Growth Investor
The market is not broken. The S&P 500 is only 1.9% from its high. AI spending remains a powerful tailwind. But three pressures are building: a hawkish Fed, record diesel, and thin breadth. The week is light on U.S. data. Watch oil headlines, Treasury yields and Middle East news. Watch Okta's analyst meeting. Watch earnings from Costco, General Mills, Darden, Paychex, Cintas and KB Home. Also watch Washington. The plan for an "AI Force" and an AI czar adds regulatory uncertainty to the market's best story. Stay with leaders. Cut losers fast. Let the chart, not the crowd, tell you when to buy.
Sources: market news brief & global social sentiment data. Updated 2026-09-20 22:00 HKT. For educational purposes only — not investment advice.
Discover more from CANSLIM Research
Subscribe to get the latest posts sent to your email.