Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
Box's Q2 beat masks a worrying slowdown: revenue growth fell to 9% from 11%, and AI revenue remains unquantified. Billings jumped 17%, but retention is stuck at 106%. Is the AI story real or just spin? The full analysis reveals what management is hiding. #Box #Earnings
The Lede and the Real Story
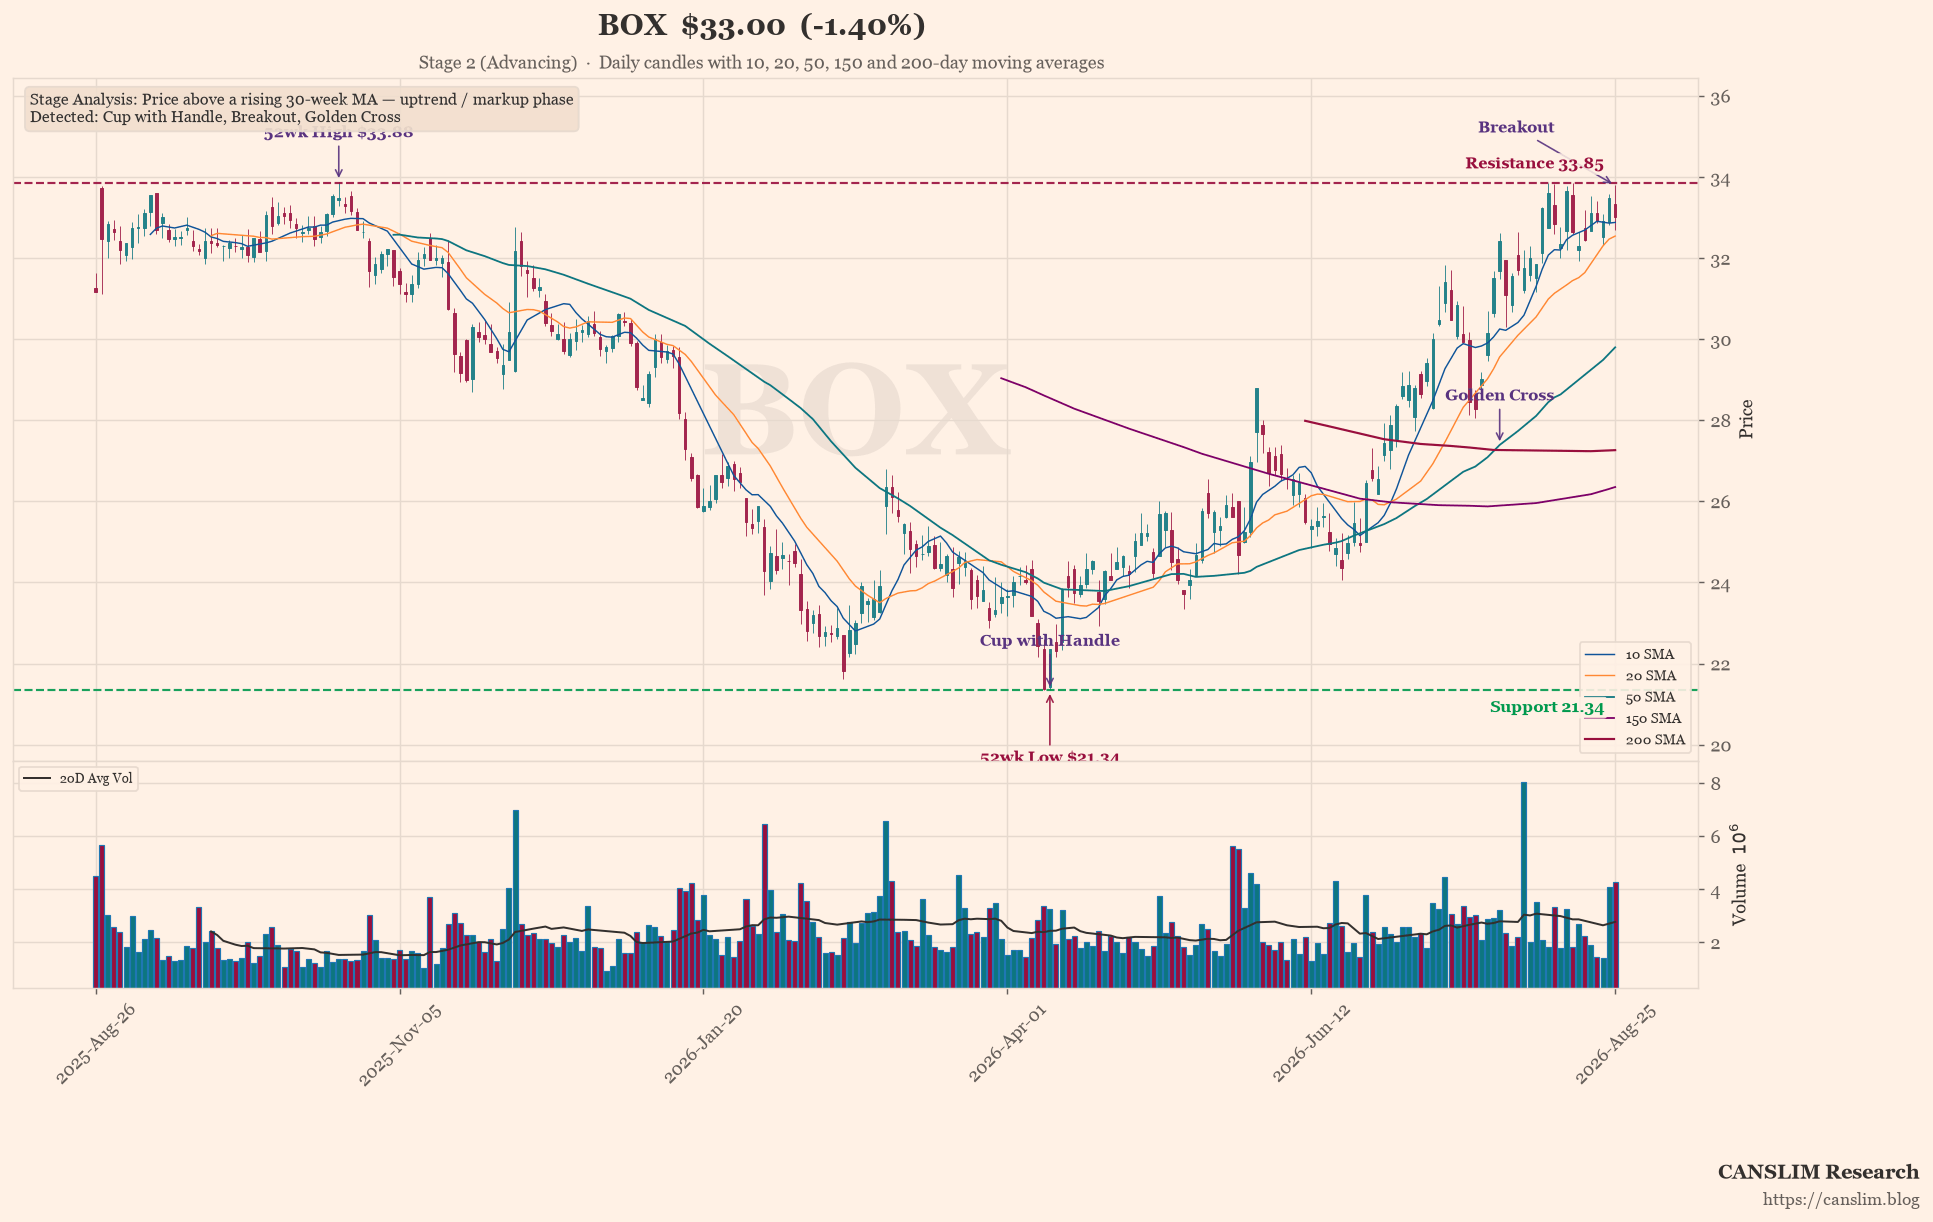
Box Inc. reported second-quarter fiscal 2027 results that, on the surface, looked like another steady beat: revenue of $321.1 million, up 9% year-over-year, and billings growth of 17%. The company raised its full-year outlook, and management touted “strong AI adoption” as the engine of growth. But beneath the polished numbers, the transcript reveals a company struggling to translate its AI narrative into durable acceleration. Revenue growth actually decelerated from 11% in the prior quarter to 9% now, and the much-hyped net retention rate of 106% is barely above the 105% reported last quarter—hardly the hockey-stick inflection investors have been promised. The real story is that Box is a mature, single-digit-growth software vendor dressing up modest gains with AI buzzwords, while its core content management business faces mounting competitive pressure from Microsoft, Google, and a wave of AI-native startups. The stock’s after-hours decline of 1.4% to $33.00 suggests the market is starting to see through the spin.
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion