Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
Intuit's 14% revenue growth hides a customer acquisition stall—the stock dropped 10% after hours. FY27 guidance of 9-10% growth is a quiet admission of trouble. Watch QuickBooks subscriber adds next quarter. The AI story is a distraction; the customer story is the real test.
The Lede and the Real Story
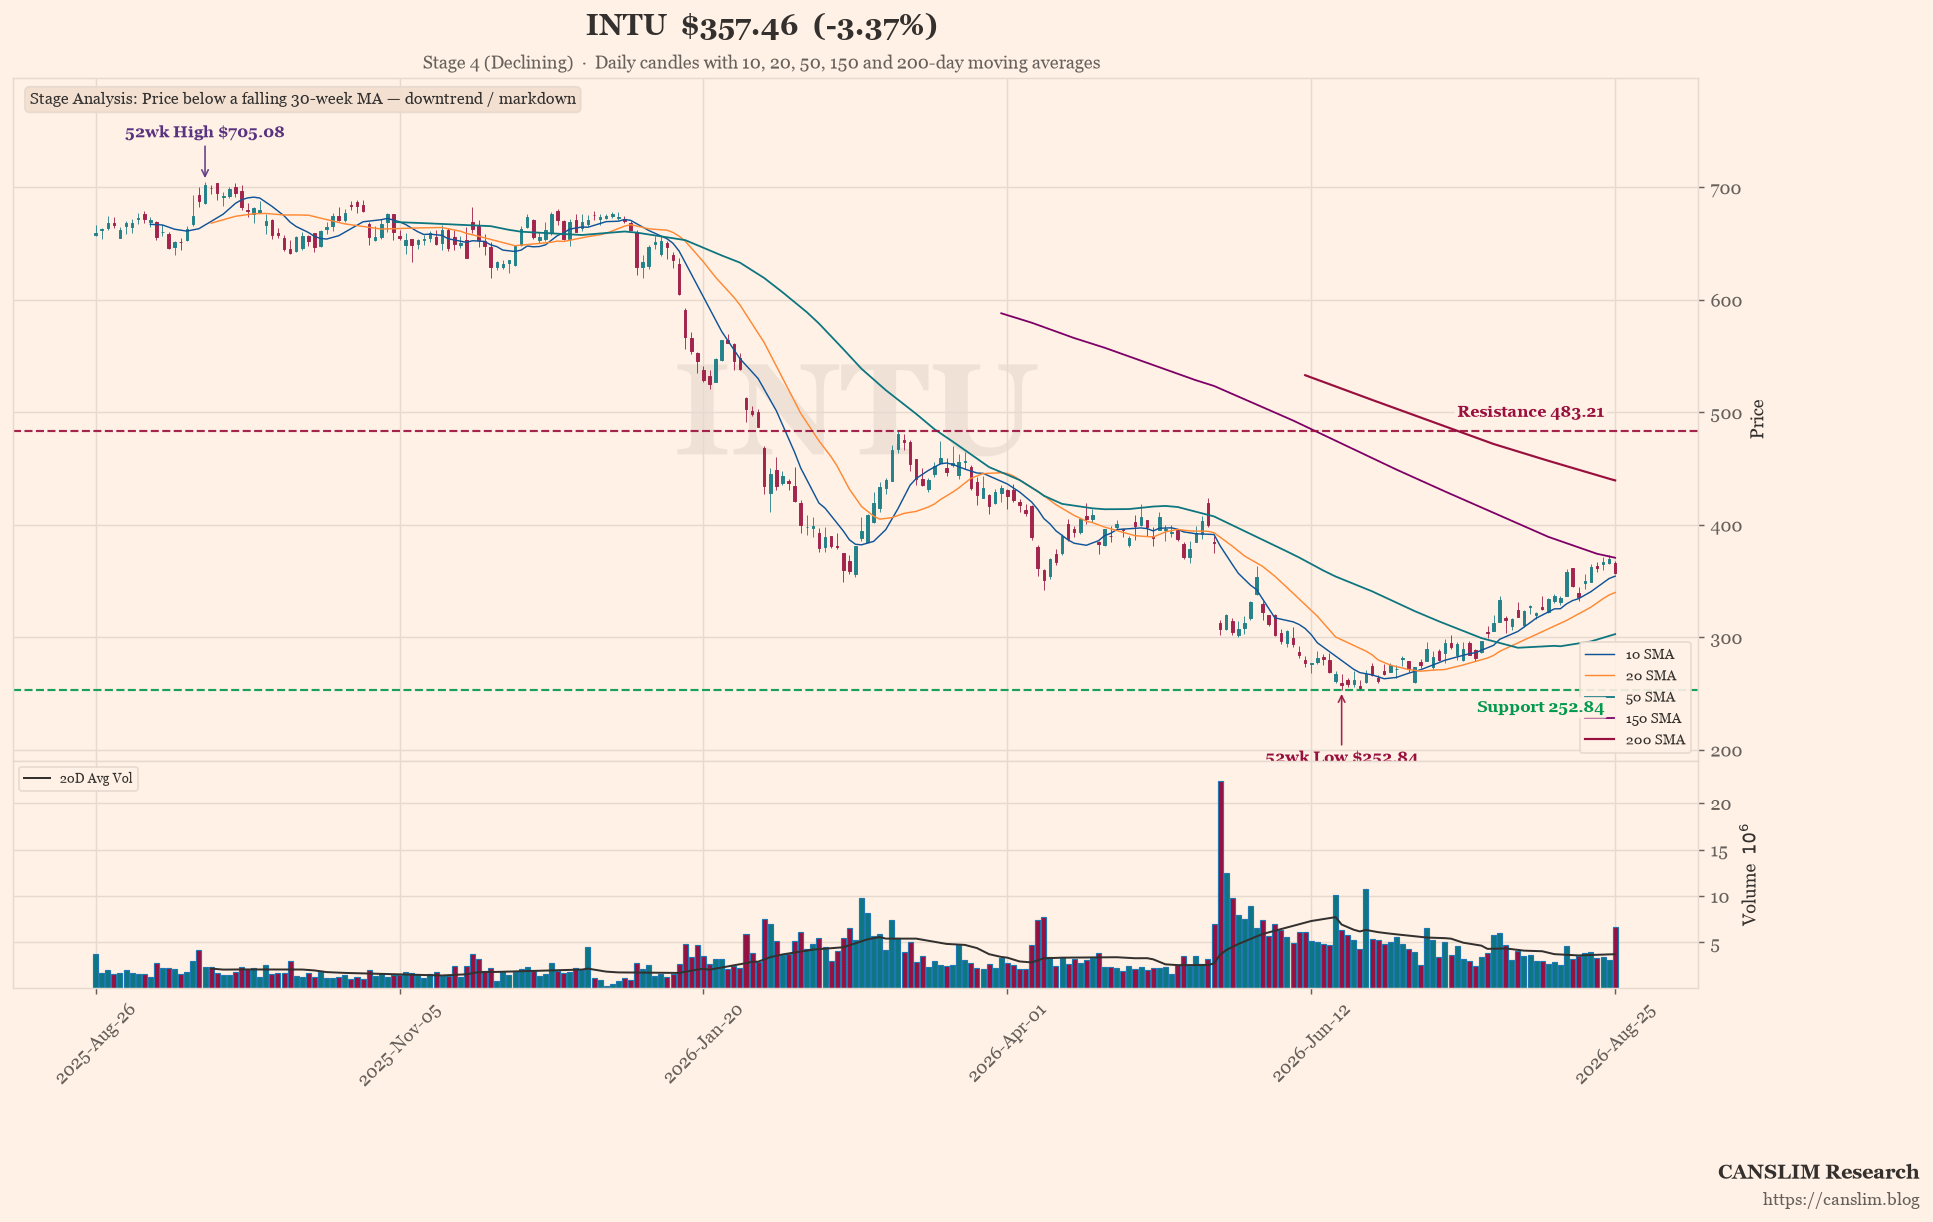
Intuit closed fiscal 2026 with a headline that looked, on its face, like another year of flawless execution: revenue up 14% to $21.4 billion, GAAP and non-GAAP EPS both up 20%, and operating margins expanding again. The stock, however, told a different story. In after-hours trading following the August 26 call, shares dropped nearly 10%, erasing roughly $35 billion in market value. That is not the reaction of a market rewarding a beat-and-raise quarter. That is the reaction of investors who read past the spin and saw the rot underneath.
The real story is not the 14% topline growth—it is the confession buried in CEO Sasan Goodarzi’s prepared remarks: “in key parts of our business, we need to grow new customers at a faster pace.” That single sentence, delivered almost as an aside, is the most honest thing said on the call. For a company that has spent five years selling an AI-driven “platform” narrative, the admission that customer acquisition is stalling is not a footnote—it is the thesis. The market’s violent reaction suggests investors agree: Intuit’s growth is increasingly a function of price hikes and cross-selling to existing users, not new customer wins. And that model has a ceiling.
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion