Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
Nutanix's Q4 beat hides a slowdown: revenue growth decelerated to ~9%, and FY27 guidance was conspicuously absent. Supply chain excuses are wearing thin—new drivers like AI are still 'nascent.' Is this a plateau or a pause? Read the full deep dive to see why the stock may be a sell.
The Lede and the Real Story
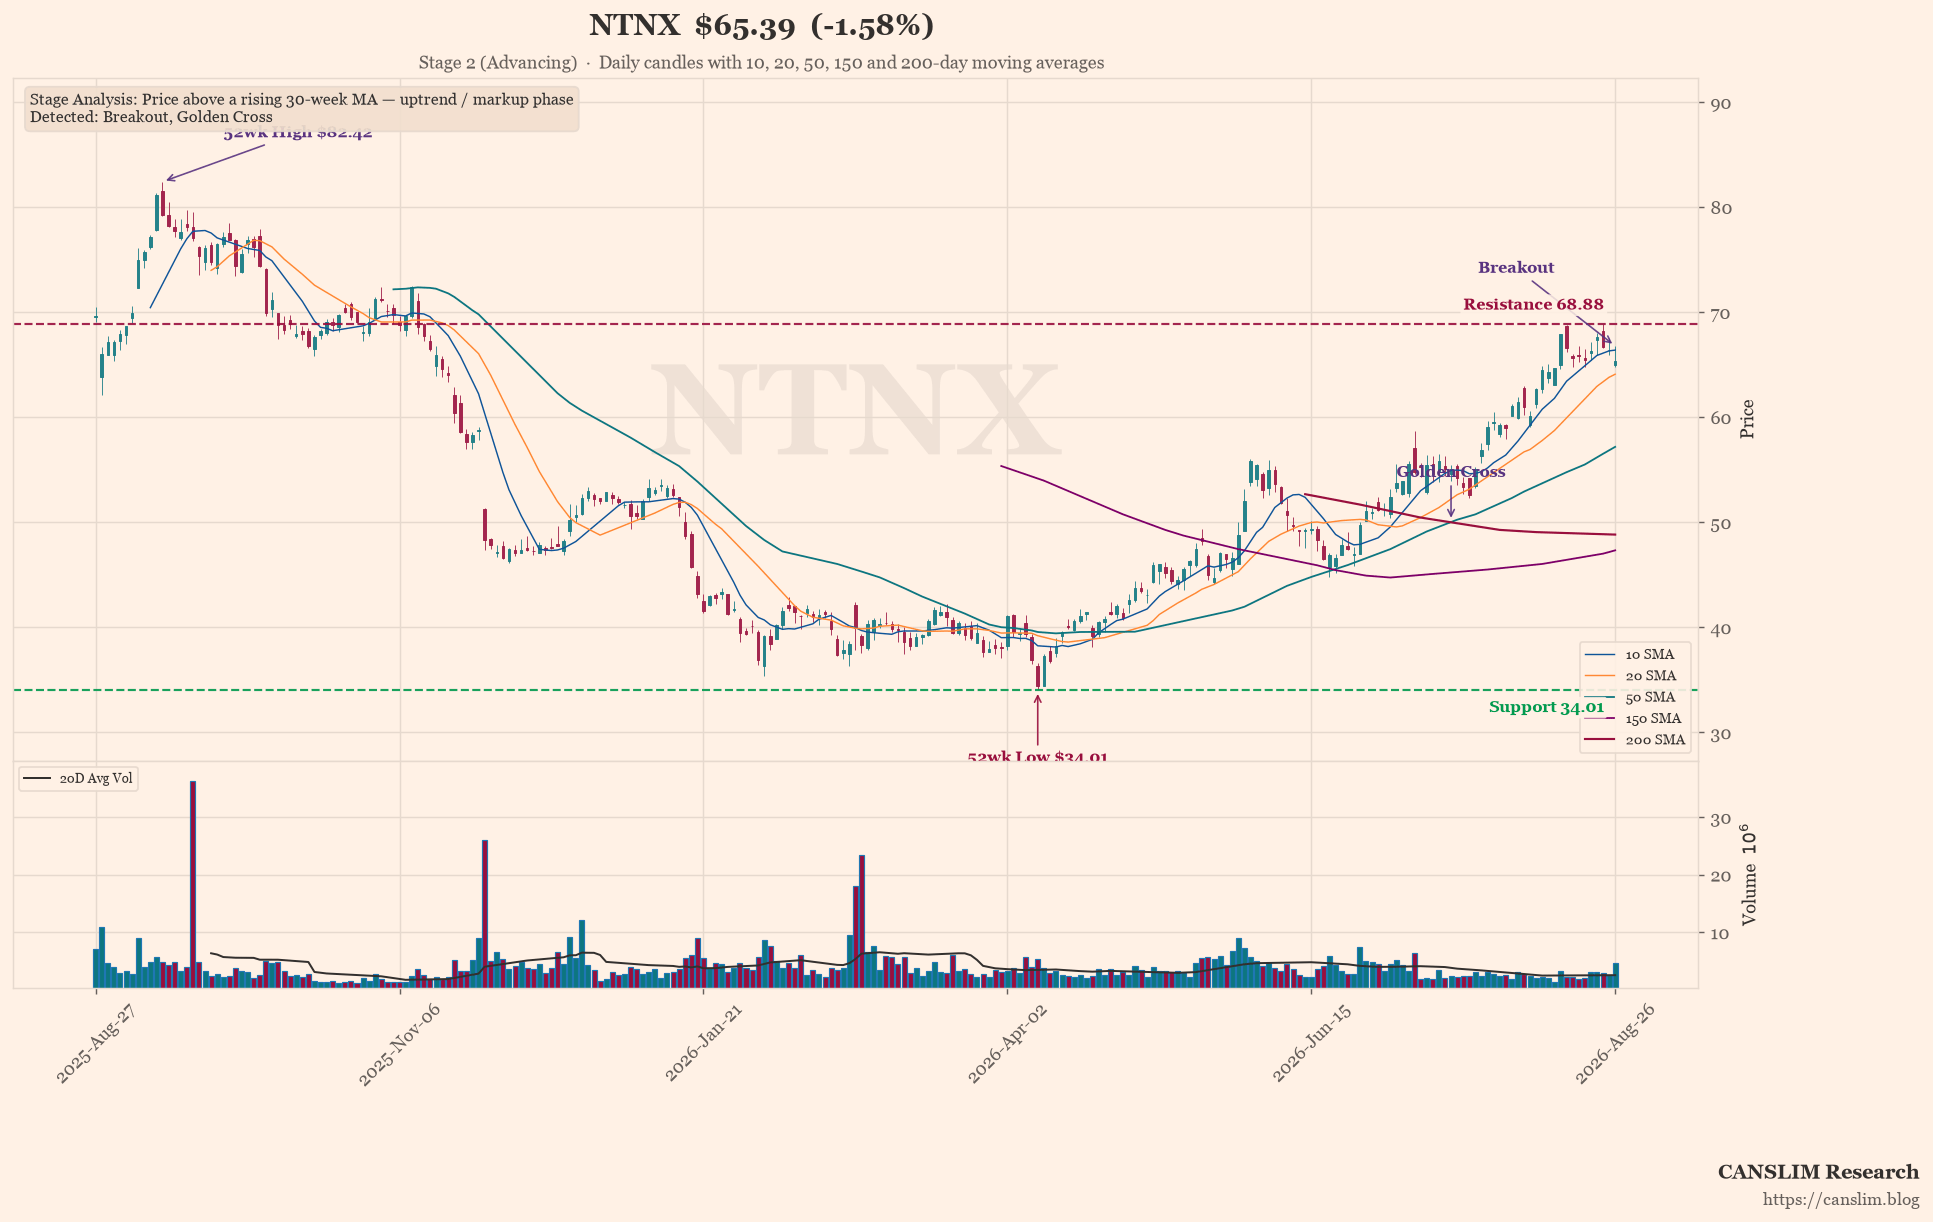
Nutanix closed fiscal 2026 with a headline beat: revenue of $2.85 billion, up 12% year-over-year, and ARR of $2.55 billion, up 16%. The company touted “record” results and a “strong finish,” but beneath the polished numbers lies a more troubling story. The fourth quarter’s revenue growth decelerated to roughly 9% year-over-year (from $703 million in Q3 to an implied ~$740 million in Q4), and the company’s own guidance for fiscal 2027—which management declined to provide on the call—suggests the momentum is fading. The real story is that Nutanix is leaning on a familiar crutch—supply chain disruptions—to explain away a slowdown in core demand, while its much-hyped new growth drivers (external storage, NC2, Kubernetes) are still too small to move the needle. Investors should ask: Is this a temporary hiccup or a structural plateau?
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion
Discover more from CANSLIM Research
Subscribe to get the latest posts sent to your email.