Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
Okta's Q2 beat masks a core slowdown: revenue growth slipped to 11%, and AI products remain a promise, not revenue. Record bookings are non-GAAP spin. With NRR missing and Microsoft looming, the 20% pop is a sell signal. Read the full breakdown.
The Lede and the Real Story
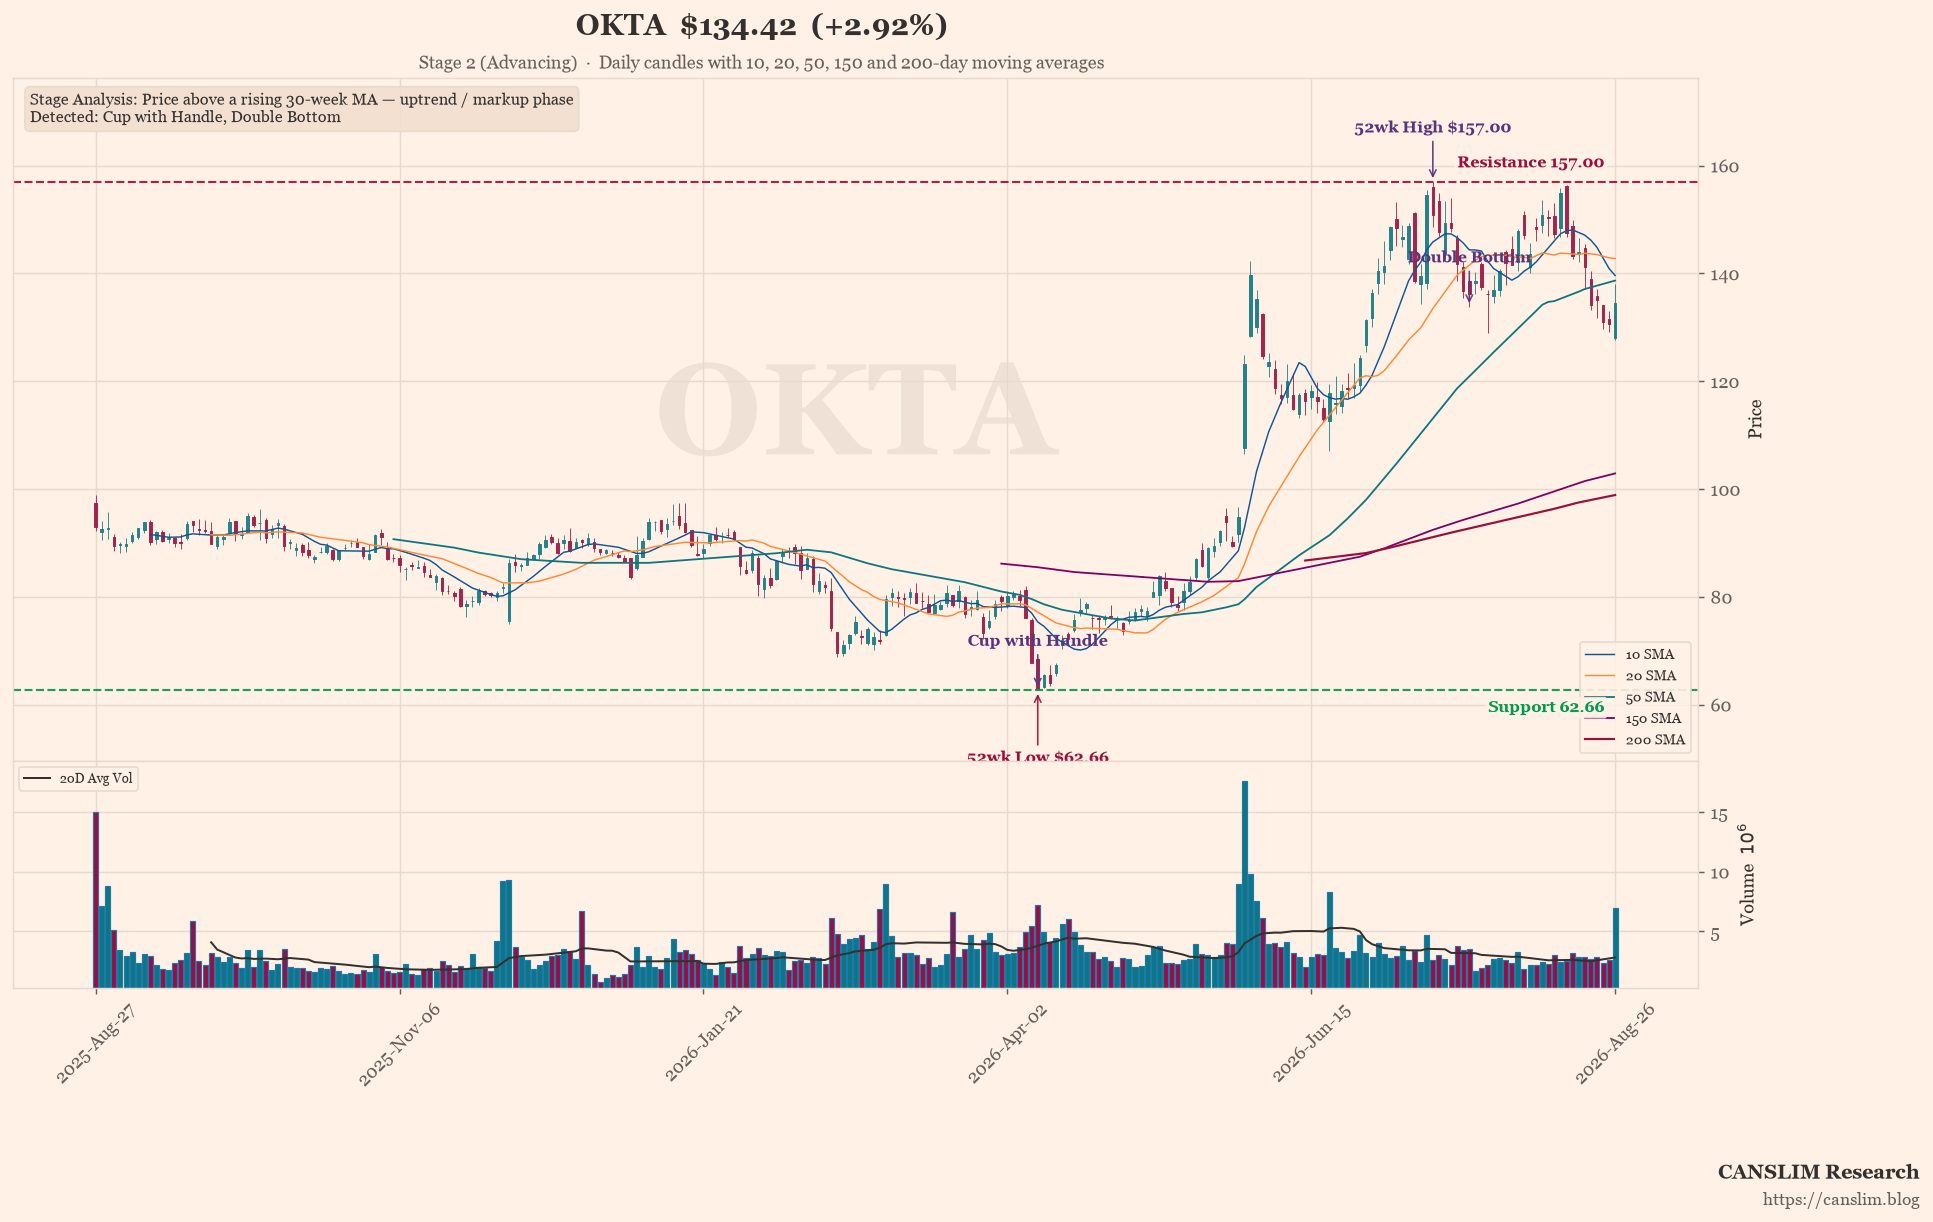
Okta’s Q2 FY2027 earnings call was a masterclass in narrative control. The headline numbers look strong: revenue hit $793 million, up 11% year-over-year, and non-GAAP EPS came in at $0.97, beating estimates by $0.12. Management touted “record Q2 bookings” and “strong enterprise growth,” while raising full-year guidance. The stock jumped 20% in after-hours trading, suggesting investors bought the story. But beneath the polished surface, the transcript reveals a company grappling with a decelerating core business, a reliance on AI buzzwords rather than tangible revenue, and a leadership team that dodged pointed questions about the sustainability of its growth.
The real story is not the beat—it’s the quality of that beat. Revenue growth of 11% is a slowdown from the 12% posted last quarter, and the company’s flagship workforce identity product is maturing. The “record bookings” figure, while impressive, is a non-GAAP metric that management controls, and the AI security products—touted as the next growth engine—contributed only a sliver of revenue. The call was heavy on optimism and light on specifics, with executives deflecting questions about customer concentration, competitive pressure, and the path to sustained double-digit growth. This is a company at a crossroads, and the earnings call revealed more about its anxieties than its achievements.
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion
Discover more from CANSLIM Research
Subscribe to get the latest posts sent to your email.