Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
Xiaomi's Q2 2026: Revenue fell, profits plunged 32% sequentially, but EV deliveries surged 28.2%. Management dodged shipment numbers and margin questions. Is the EV story masking a shrinking core? Read the full breakdown to see what the call didn't say.
The Lede and the Real Story
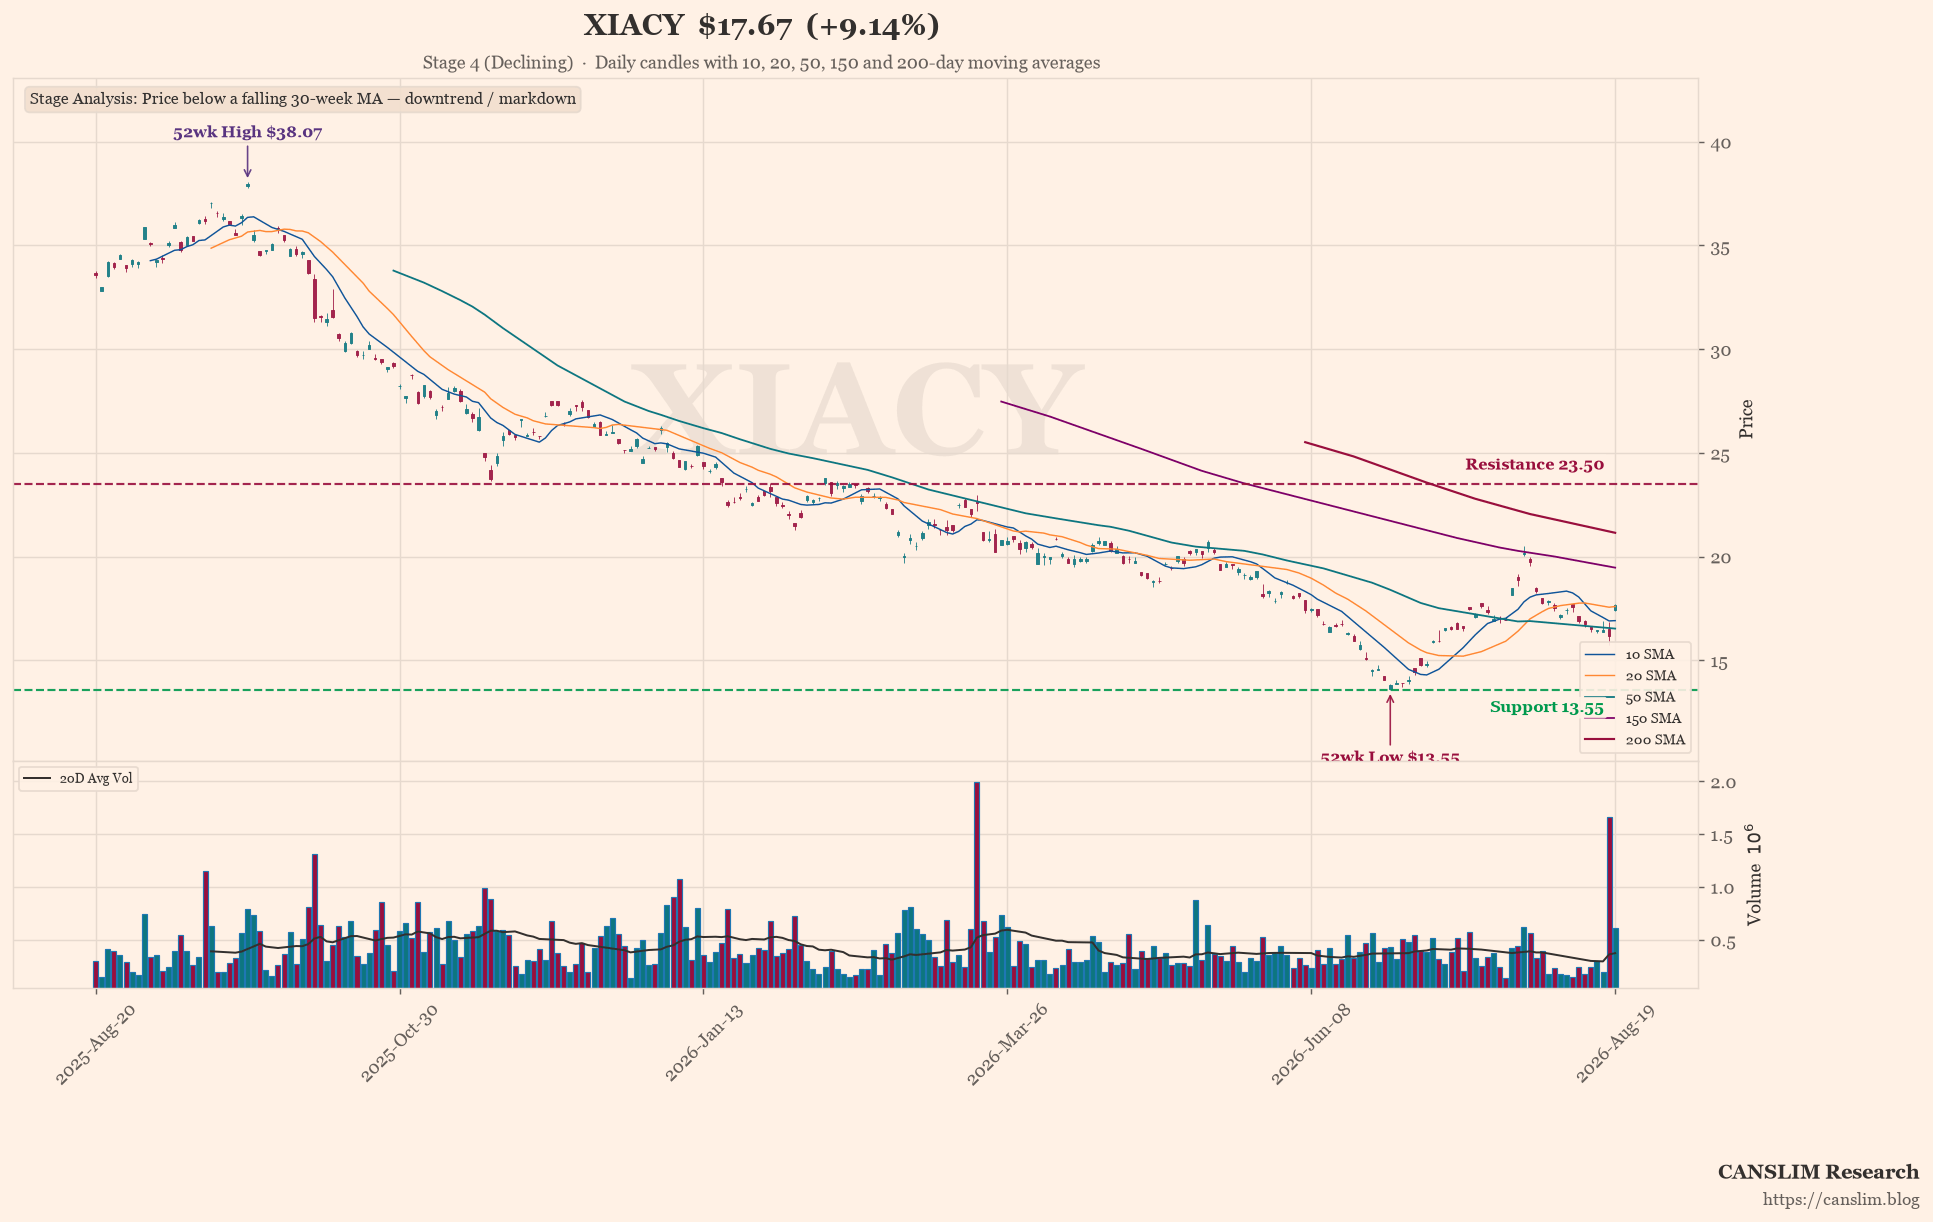
Xiaomi’s Q2 2026 earnings call was a masterclass in selective storytelling. The headline numbers—RMB 108.9 billion in revenue and RMB 6.2 billion in adjusted net profit—were framed as evidence of a company in robust health, with management touting a record smartphone average selling price (ASP) and a 28.2% year-over-year surge in EV deliveries. But scratch the surface and a different picture emerges: revenue actually declined year-over-year, and adjusted net profit fell sharply from the prior quarter’s RMB 9.1 billion to RMB 6.2 billion—a 32% sequential collapse. The stock’s after-hours reaction—a 9.14% jump to $17.67—suggests investors bought the spin, but the numbers tell a more troubling story.
The real story is that Xiaomi’s core smartphone and IoT businesses are stagnating, and the EV segment—the supposed growth engine—is burning cash while contributing only a fraction of overall revenue. Management’s emphasis on EV growth and AI buzzwords masks a fundamental problem: the company’s traditional hardware margins are being squeezed, and its new bets have yet to prove they can generate sustainable profits. This is not a growth story; it’s a transition story with serious execution risks.
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion