Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
Home Depot beat Q2 estimates with $47.9B revenue and $4.92 EPS, but the stock's muted +2% move tells the real story. Pro growth went unmentioned, margins stayed flat, and guidance wasn't raised. The DIY engine is fine, but the Pro engine is stalling. Is this beat a peak? Read the full breakdown.
The Lede and the Real Story
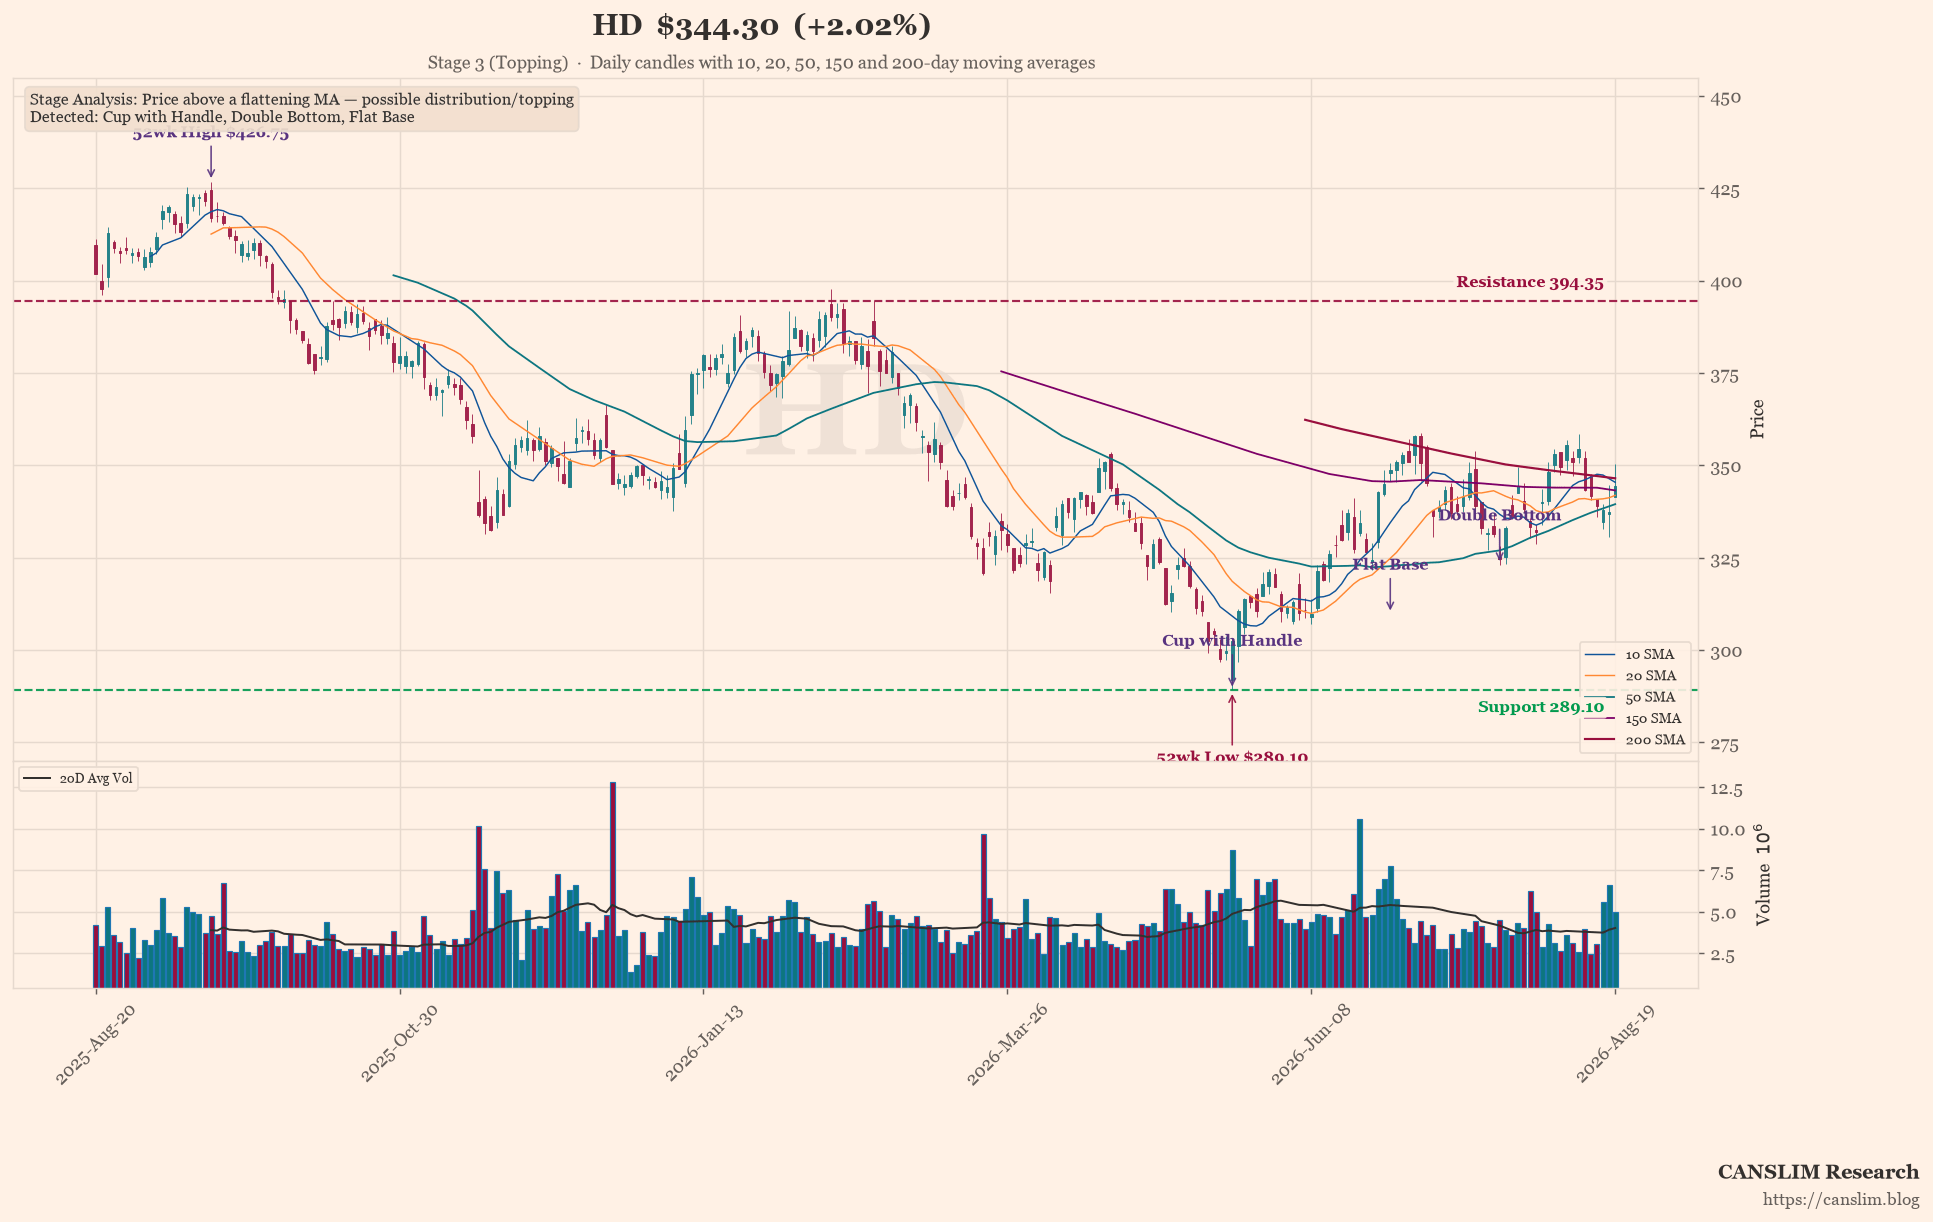
Home Depot reported a headline-beating second quarter: revenue of $47.86 billion, up 5.7% year-over-year, and earnings per share of $4.92, a 4% surprise above consensus. The stock rose 2% in after-hours trading. Management called it ‘broad demand and operational investments.’ But beneath the surface, the quarter reveals a company at a critical inflection point, where the optics of a beat are masking a deceleration in the very engine that has driven its post-pandemic growth: the Pro customer.
The real story is not the beat; it is the silence around Pro sales growth, the absence of the CEO from the call, and a guidance reaffirmation that feels increasingly like a floor, not a ceiling. While DIY demand appears stable, the transcript shows executives dodging direct questions about Pro momentum, a segment they have spent billions and years courting. The tension is between a management team projecting confidence and a balance sheet and Q&A that whisper of a slowdown in high-margin, big-ticket transactions. Investors are left to wonder if this beat is a peak or a plateau.
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion
Discover more from CANSLIM Research
Subscribe to get the latest posts sent to your email.