Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
Hesai's Q2 EPS missed by 90% ($0.01 vs $0.07), yet stock rose 2.58% on robotics hype. New 'Kosmo' and actuation modules are immaterial; core lidar margins under pressure. Is the narrative masking execution failure? Read the full breakdown.
The Lede and the Real Story
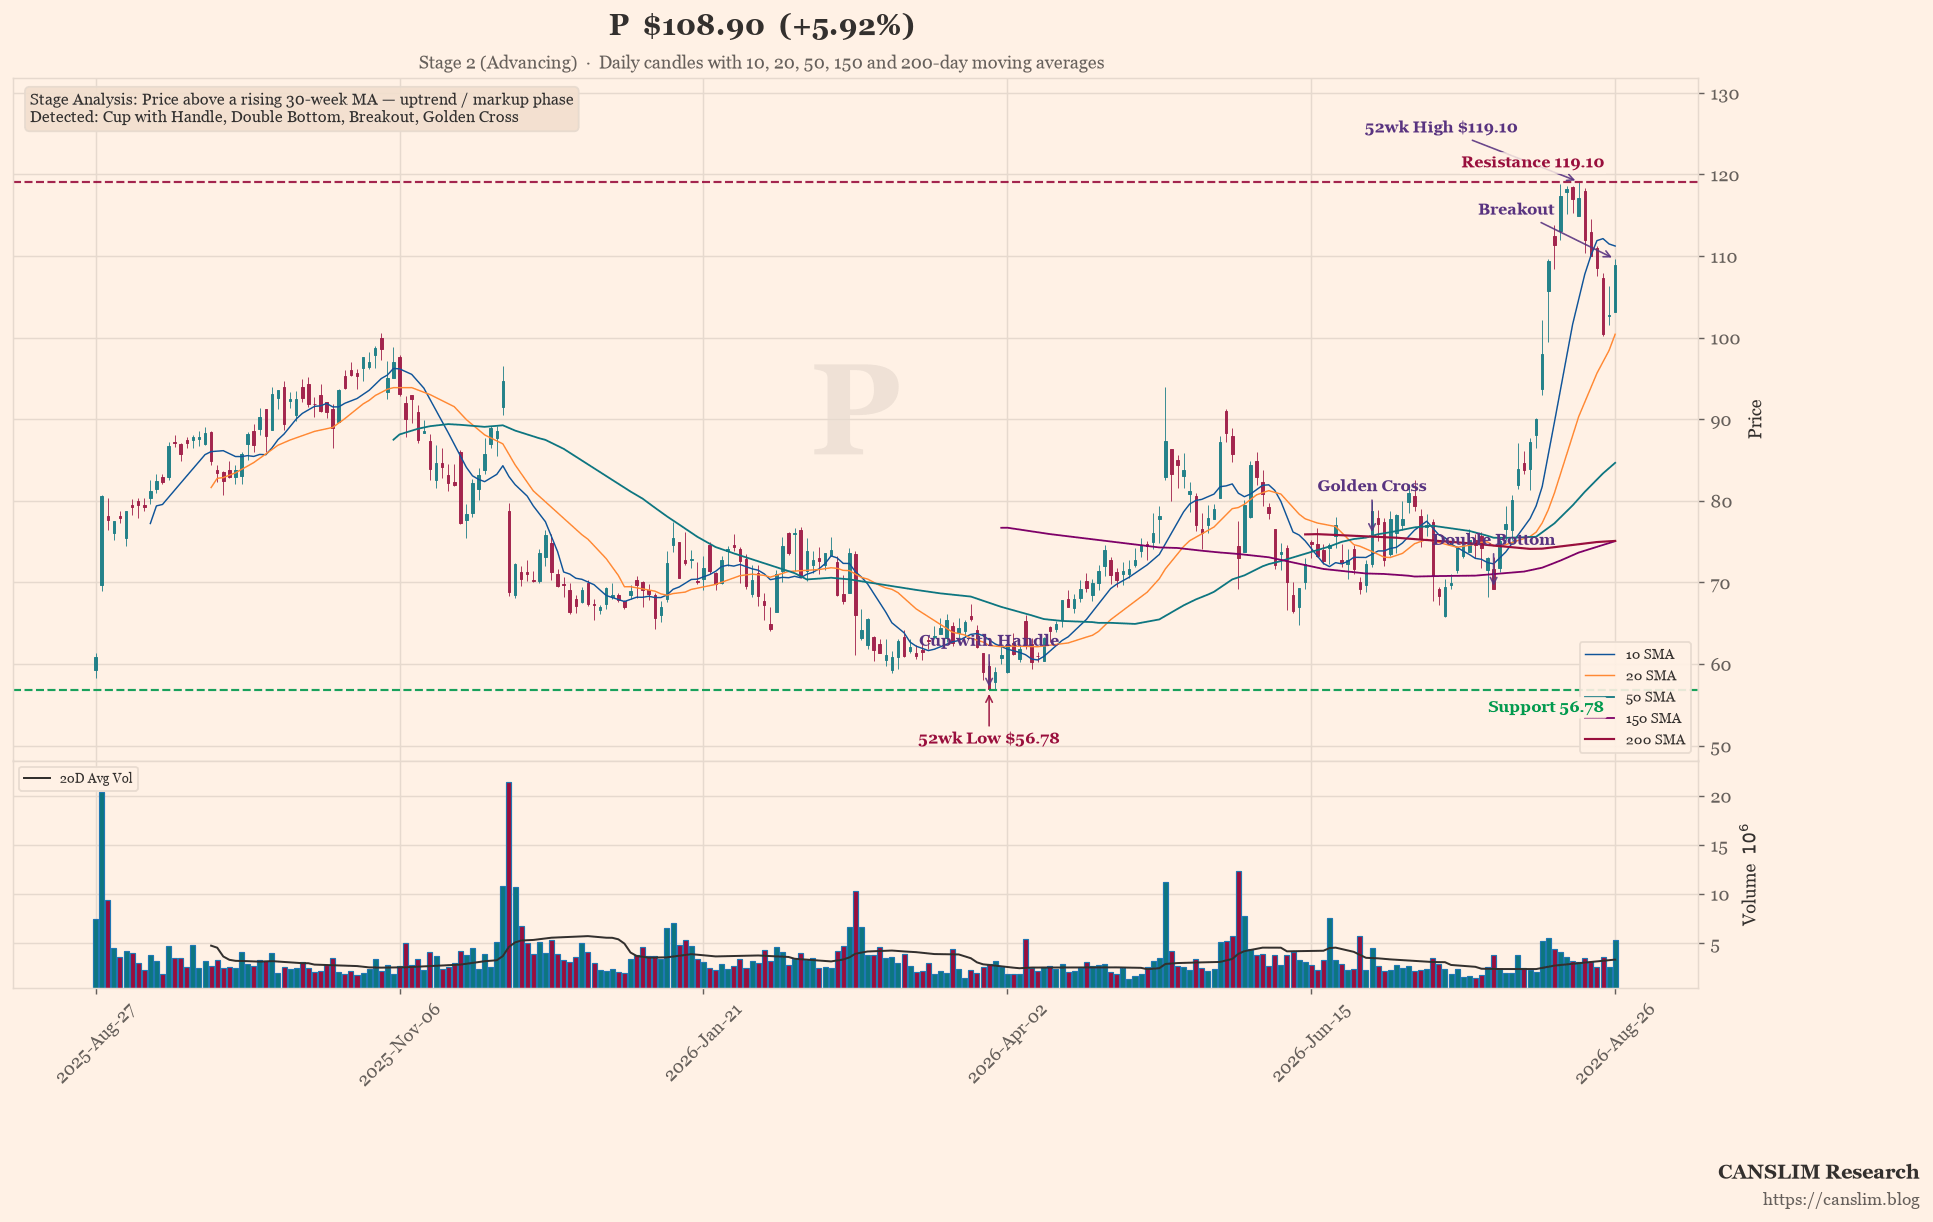
Hesai Group’s second-quarter 2026 earnings call was a masterclass in narrative engineering. The company beat revenue estimates by a hair—$126.7 million against a $126.0 million consensus—and shipped a record number of lidar units. But the headline number that matters most, earnings per share, collapsed to just $0.01, an 89.8% miss against the $0.07 analysts expected. That is not a rounding error; it is a 90% shortfall. Management buried this under a flood of buzzwords: ‘full stack infrastructure platform,’ ‘spatial intelligence,’ ‘Kosmo Shift,’ and ‘robotic actuation modules.’ The real story is that Hesai’s core lidar business is growing, but the company is spending aggressively on new ventures that have yet to prove they can generate meaningful, profitable revenue. The stock’s after-hours move—up 2.58% to $19.10—suggests retail investors bought the hype, but the EPS miss signals a deeper problem: costs are spiraling faster than the new businesses can offset. This is a company at a crossroads, and the earnings call was less about transparency and more about selling a future that hasn’t arrived.
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion
Discover more from CANSLIM Research
Subscribe to get the latest posts sent to your email.