Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
Semtech's record quarter hides a $160M one-time gain from selling its cellular business. Data center growth is real, but margins are flat and debt remains. Is this a genuine turnaround or a dressed-up divestiture? Read the full breakdown to see what management didn't say.
The Lede and the Real Story
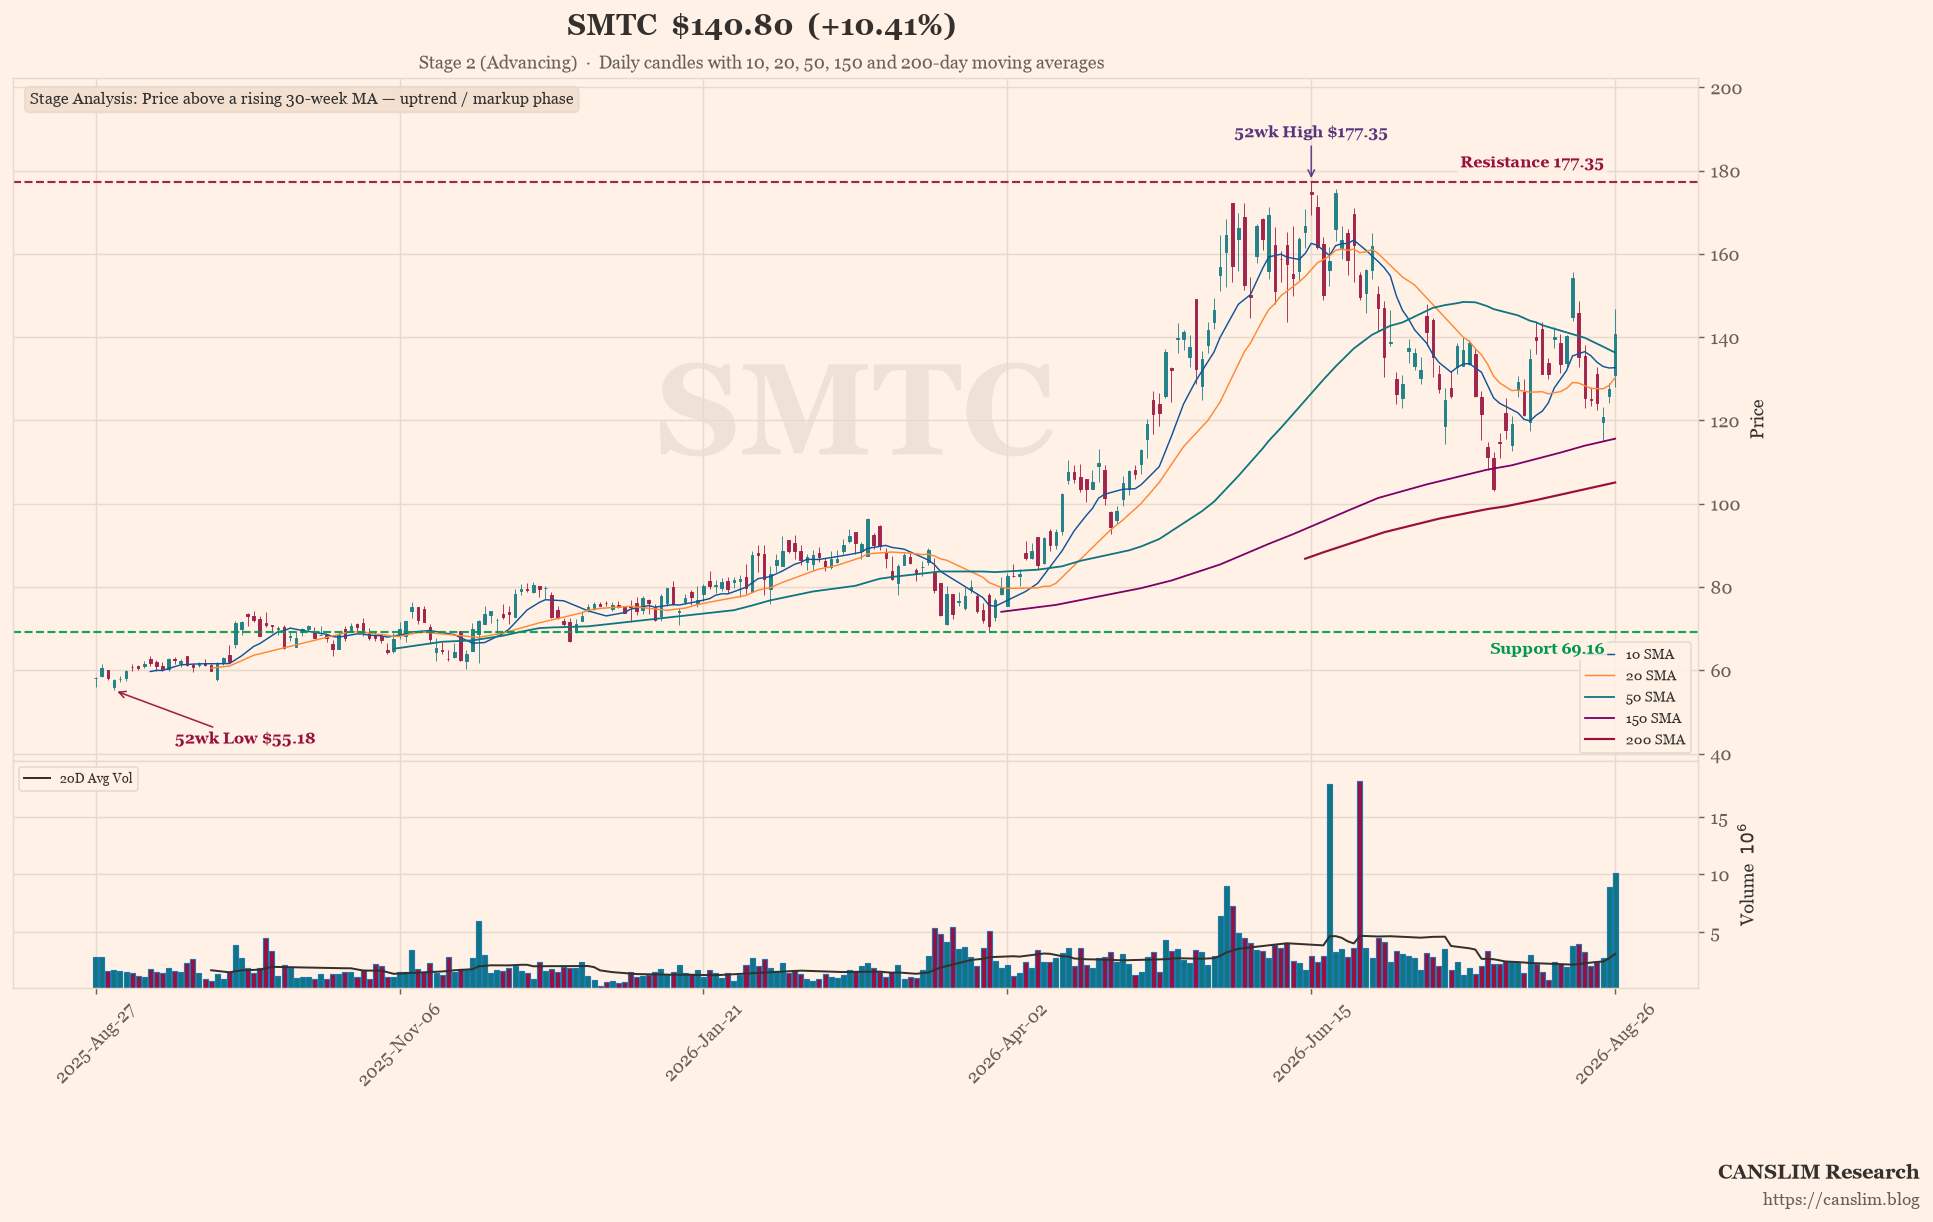
Semtech’s headline numbers for Q2 FY2027 look spectacular: revenue of $341.9 million, up 33% year-over-year, and non-GAAP EPS of $0.71, beating estimates by nearly 16%. The stock jumped 10.4% after hours. But beneath the record sales and margin expansion lies a far messier story. The company reported net income of $160.1 million — yet that figure is inflated by a one-time gain from the sale of its cellular module business, a divestiture that management quietly announced in the same release. Strip out that gain, and the underlying profitability is far thinner than the optics suggest.
The real story is that Semtech is in the middle of a portfolio transformation, selling off legacy IoT hardware to double down on data center and LoRa. That pivot is working — data center revenue is booming — but the company is also facing margin compression in its core Signal Integrity segment, a shrinking IoT Systems business, and a balance sheet still heavy with debt from the Sierra Wireless acquisition. Management’s scripted optimism glosses over these cracks, and the Q&A reveals a leadership team dodging questions about sustainability, competition, and the true quality of earnings.
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion
Discover more from CANSLIM Research
Subscribe to get the latest posts sent to your email.