Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
CrowdStrike's Q2 beat was real, but net new ARR is decelerating and AI revenue is still a mirage. Stock jumped 9% on hype, but the fundamentals say slowdown. Read the full breakdown before you buy the narrative.
The Lede and the Real Story
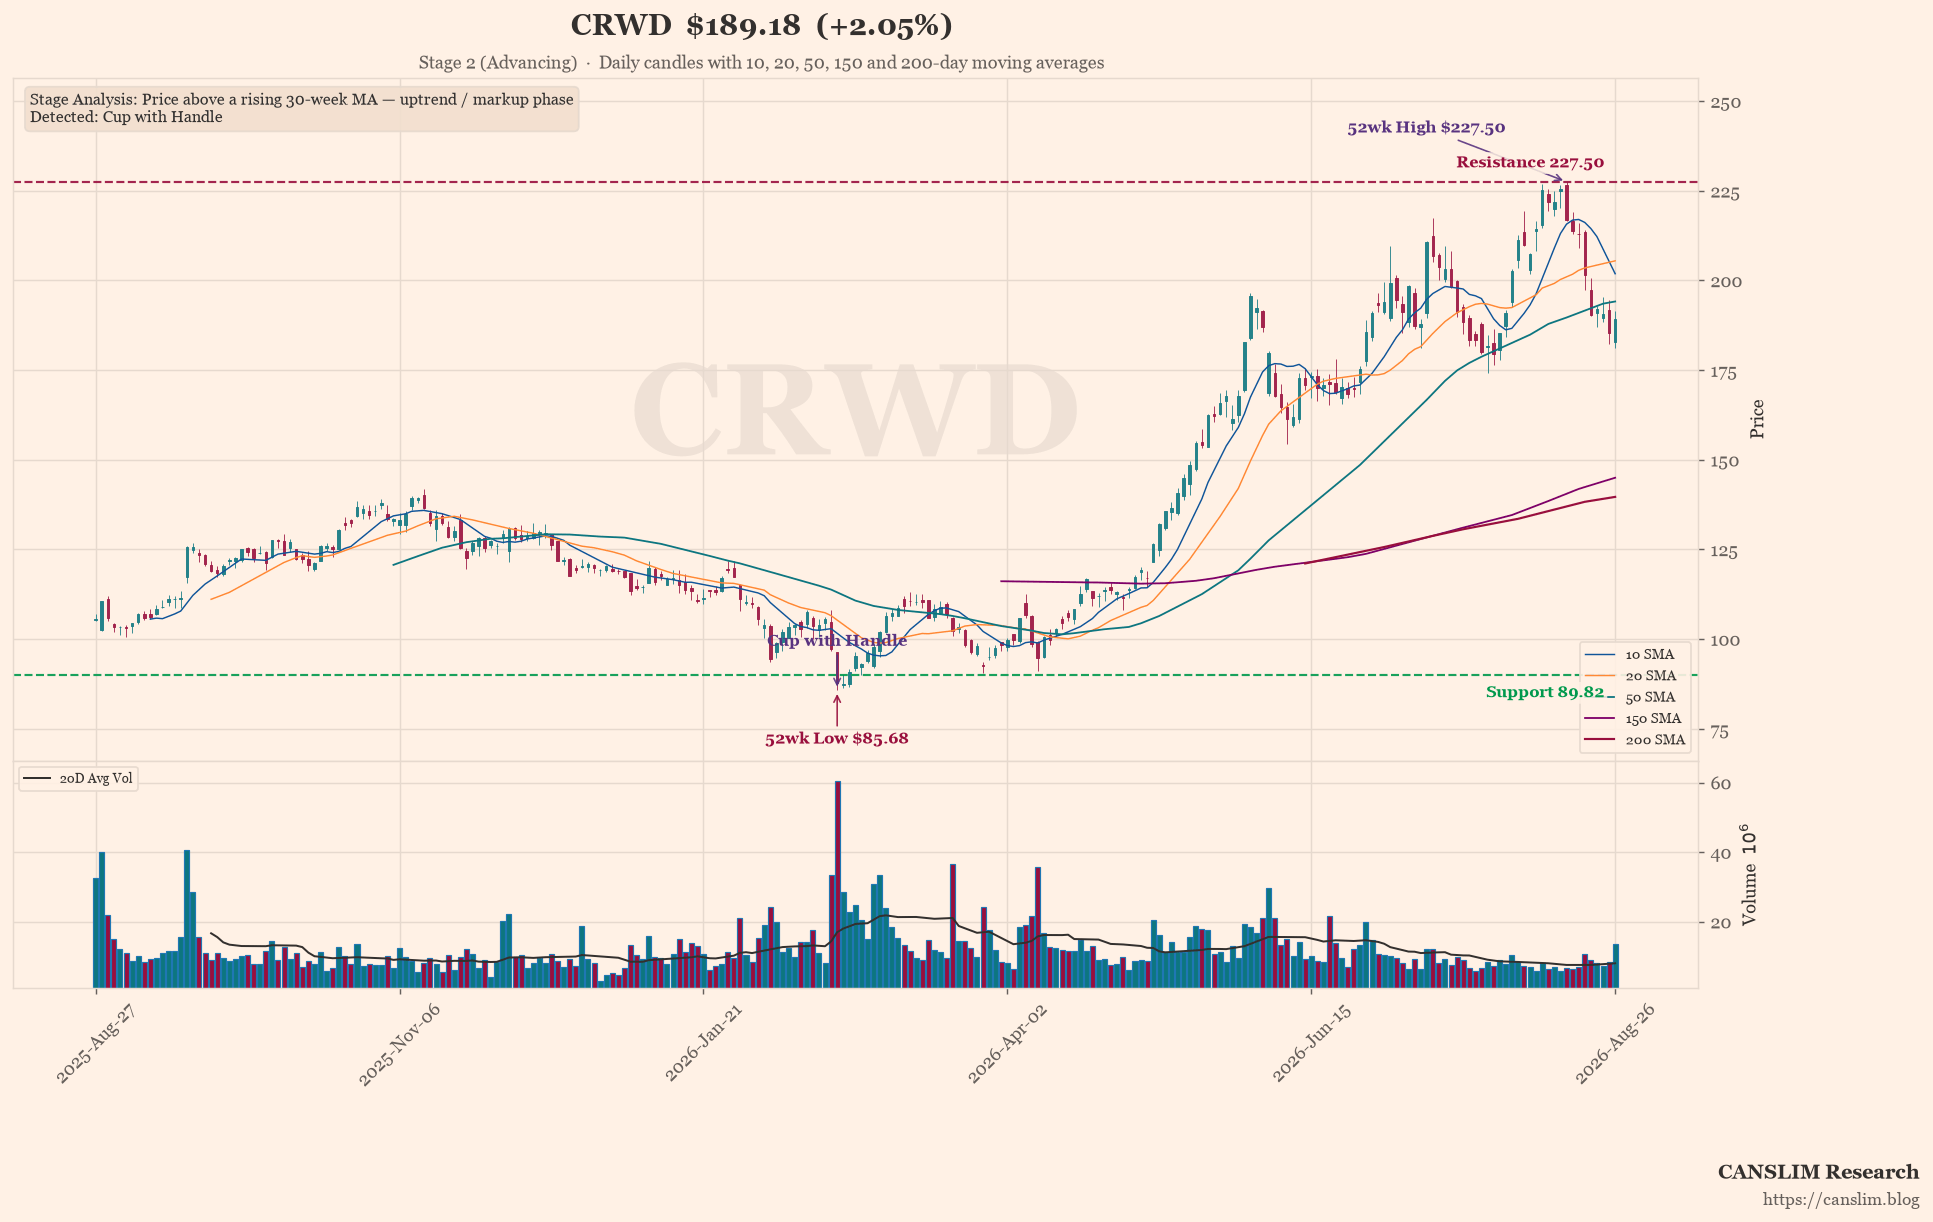
When CrowdStrike reported its fiscal second-quarter 2027 results on August 27, 2026, the headline was unmistakable: “Record Q2 growth and raised FY 2027 outlook highlight accelerating AI-driven demand.” The stock jumped 9.14% in after-hours trading to $206.76, and CEO George Kurtz opened the call with a triumphant narrative about the “Mythos moment” and the rise of “AI agents” as the newest adversary. But beneath the polished surface, the numbers tell a more complicated story. Revenue came in at $1.44 billion, up 26% year-over-year, and non-GAAP EPS of $0.29 beat estimates by a penny. Yet the growth rate is decelerating—from 26% in Q1 FY2027 to 22% in Q1 FY2026, and now to 26% again, but that’s a slowdown from the 30%+ growth the company posted in fiscal 2025. The real story isn’t the AI narrative; it’s the quiet erosion of net new ARR growth, the rising reliance on non-GAAP metrics, and a guidance raise that still implies a sharp deceleration in the second half. Investors are paying a premium for a story that’s increasingly at odds with the underlying fundamentals.
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion
Discover more from CANSLIM Research
Subscribe to get the latest posts sent to your email.