Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
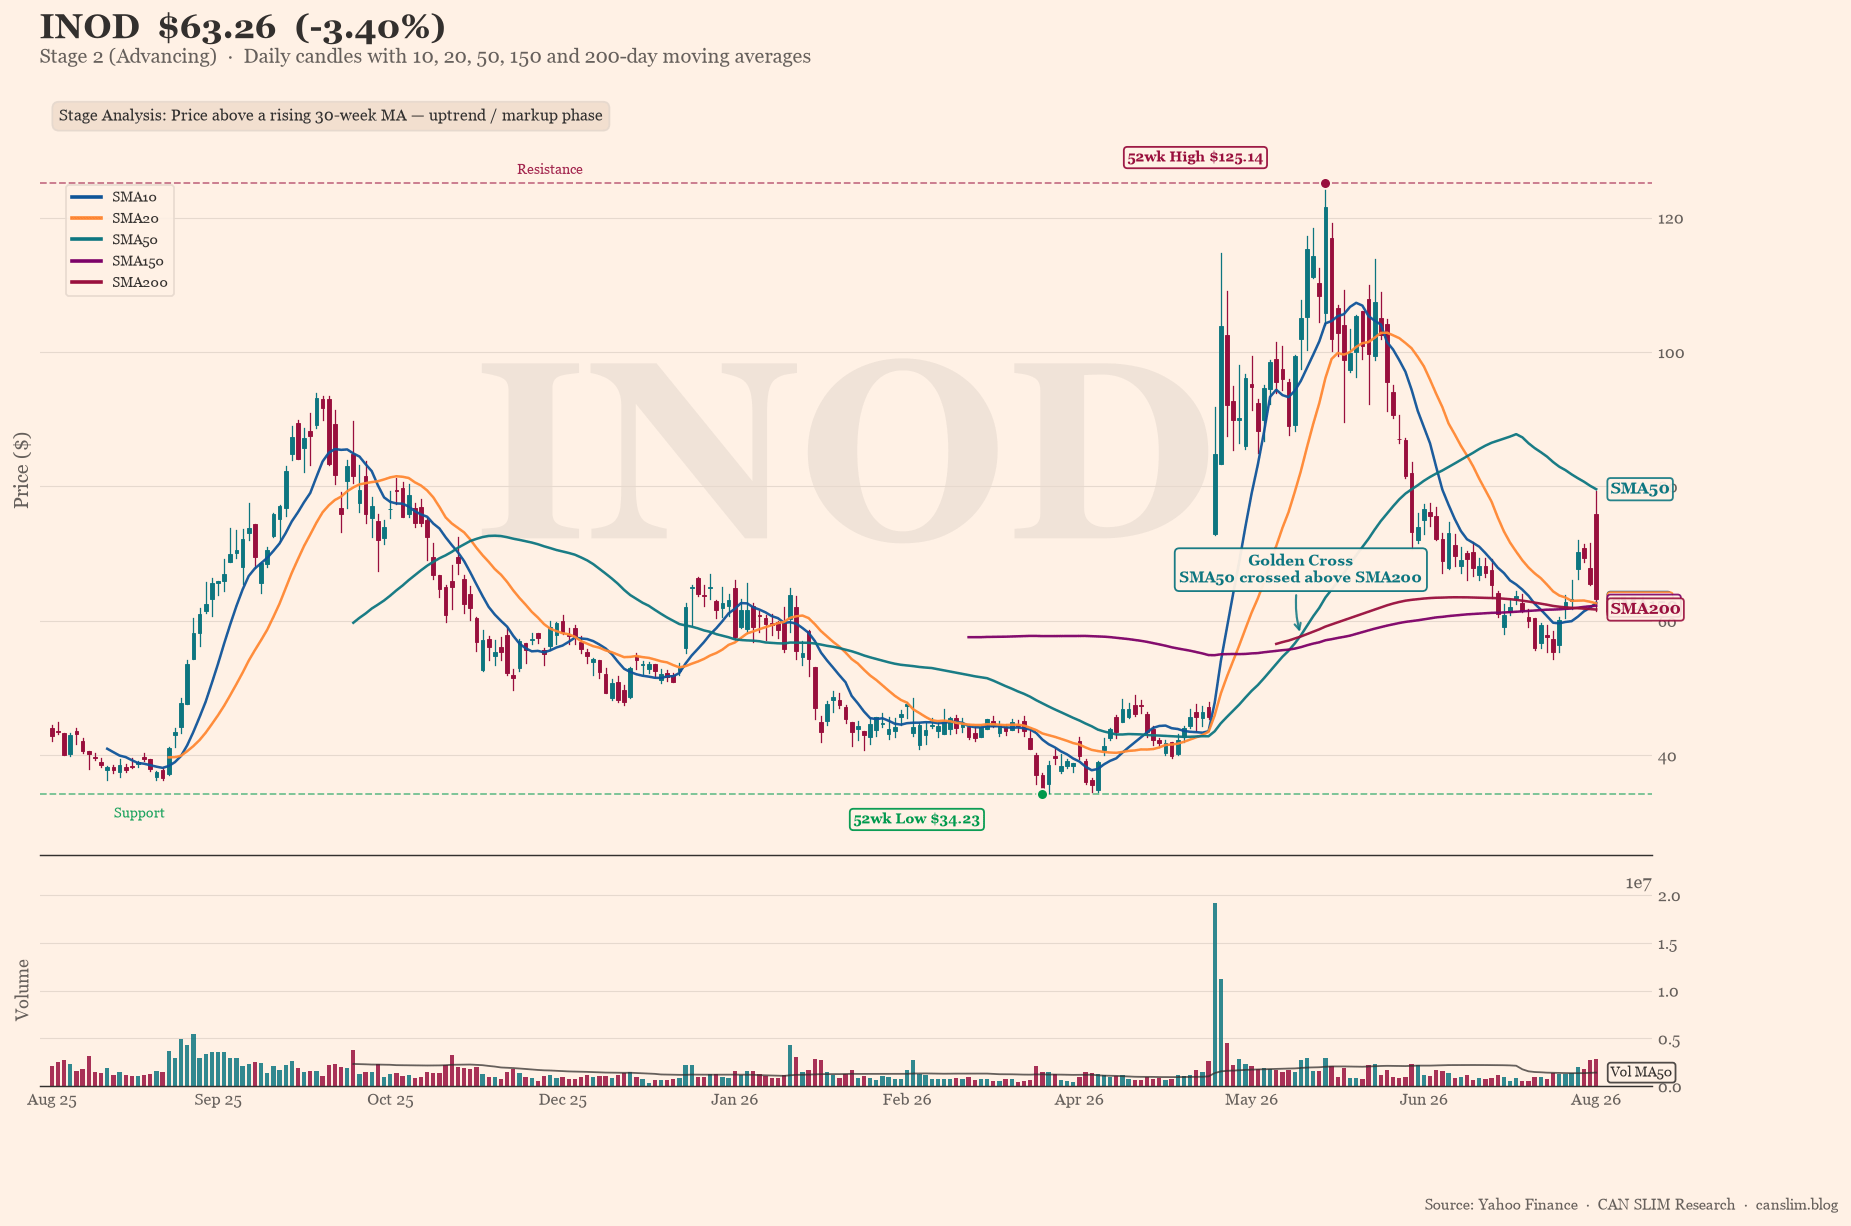
Innodata’s Q2 beat hides a leadership vacuum and a 2% sequential growth stall. EPS crushed estimates, but the stock fell 3.4% after hours—smart money is exiting. Can the new CEO sustain 58% growth without naming its mega-customer? Read the full breakdown.
The Lede and the Real Story
Innodata reported a headline-grabbing Q2 2026: revenue of $92.14 million, up 58% year-over-year, with adjusted EPS of $0.41 crushing consensus by 92%. Adjusted gross margin hit 49%, and adjusted EBITDA reached new highs. The stock, however, fell 3.39% in after-hours trading—a classic ‘sell the news’ reaction that hints investors are looking past the optics. The real story is not the growth—it’s the leadership transition announced quietly in the press release, the decelerating sequential growth (from 54% YoY in Q1 to 58% in Q2, but only $2 million in absolute revenue growth quarter-over-quarter), and the dependence on a single mega-customer that management refuses to name. The market is asking: Can this growth continue without the founder-CEO at the helm, and is the revenue quality as strong as the headline suggests?
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion
Discover more from CANSLIM Research
Subscribe to get the latest posts sent to your email.