Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
Qfin's Q2 miss: revenue down 7.3% sequentially, EPS misses by 8.5%, stock plunges 19%. Management hides take rate decline and dodges guidance. Is 'prudent risk management' just a cover for stagnation? Read the full breakdown.
The Lede and the Real Story
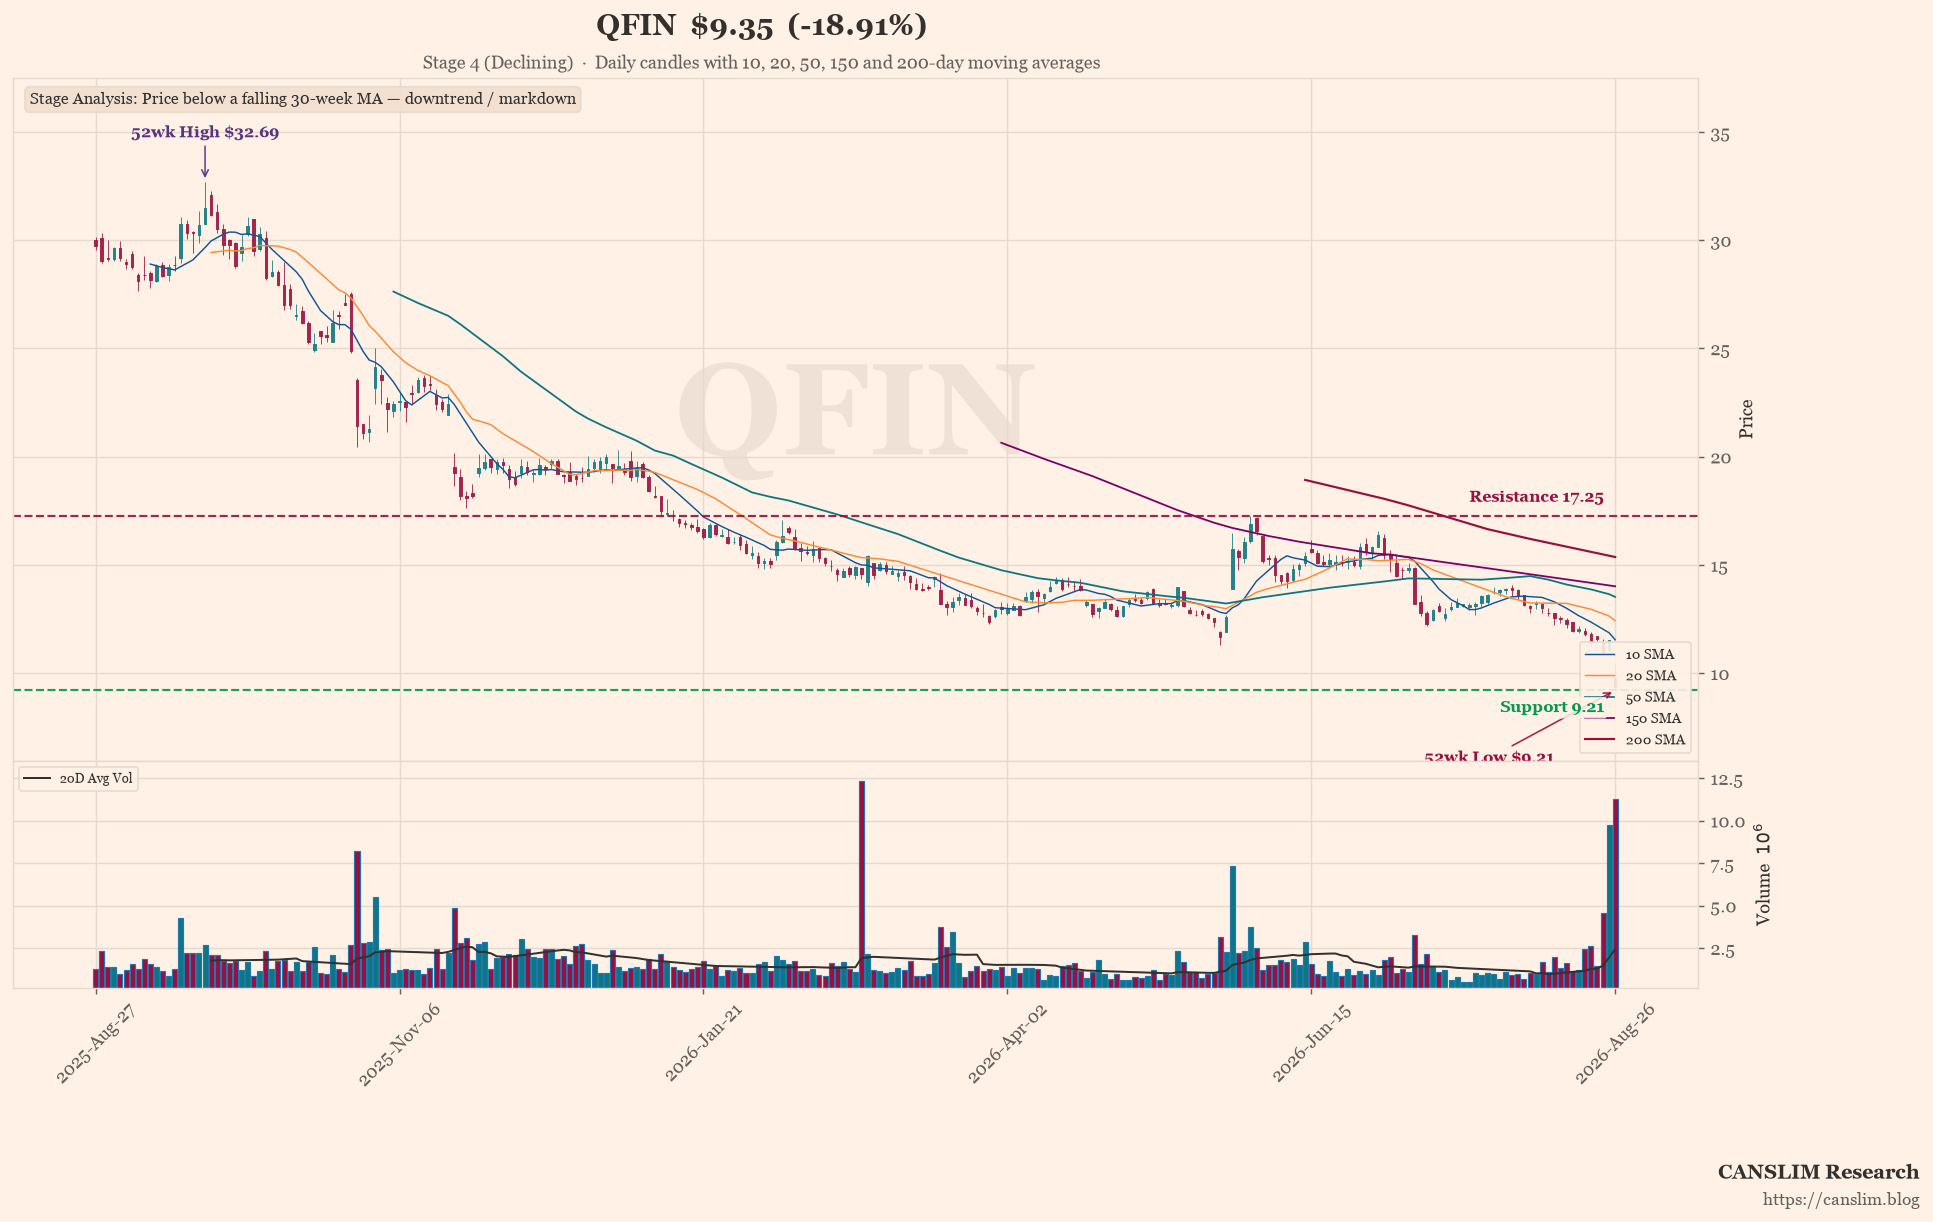
Qfin Holdings, the Shanghai-based AI credit-tech platform, reported second-quarter 2026 earnings that missed Wall Street’s expectations on both the top and bottom lines. Revenue came in at $524.93 million, a 6.67% miss against the $562.45 million consensus, while non-GAAP EPS of $0.97 fell 8.51% short of the $1.06 estimate. The stock reacted violently, plunging 18.91% in after-hours trading to $9.35. Management’s narrative is one of prudent risk management in a tough macro environment—but the numbers tell a more uncomfortable story: Qfin’s loan origination volume fell 2.5% sequentially to RMB 63.4 billion, and revenue dropped 7.3% sequentially from $566.58 million in Q1. The real story is that Qfin’s ‘prudence’ is starting to look like stagnation, and the company’s reliance on a shrinking consumer credit market is catching up with it. The market is punishing Qfin not for a one-off miss, but for a pattern of declining volumes and a lack of credible growth drivers.
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion