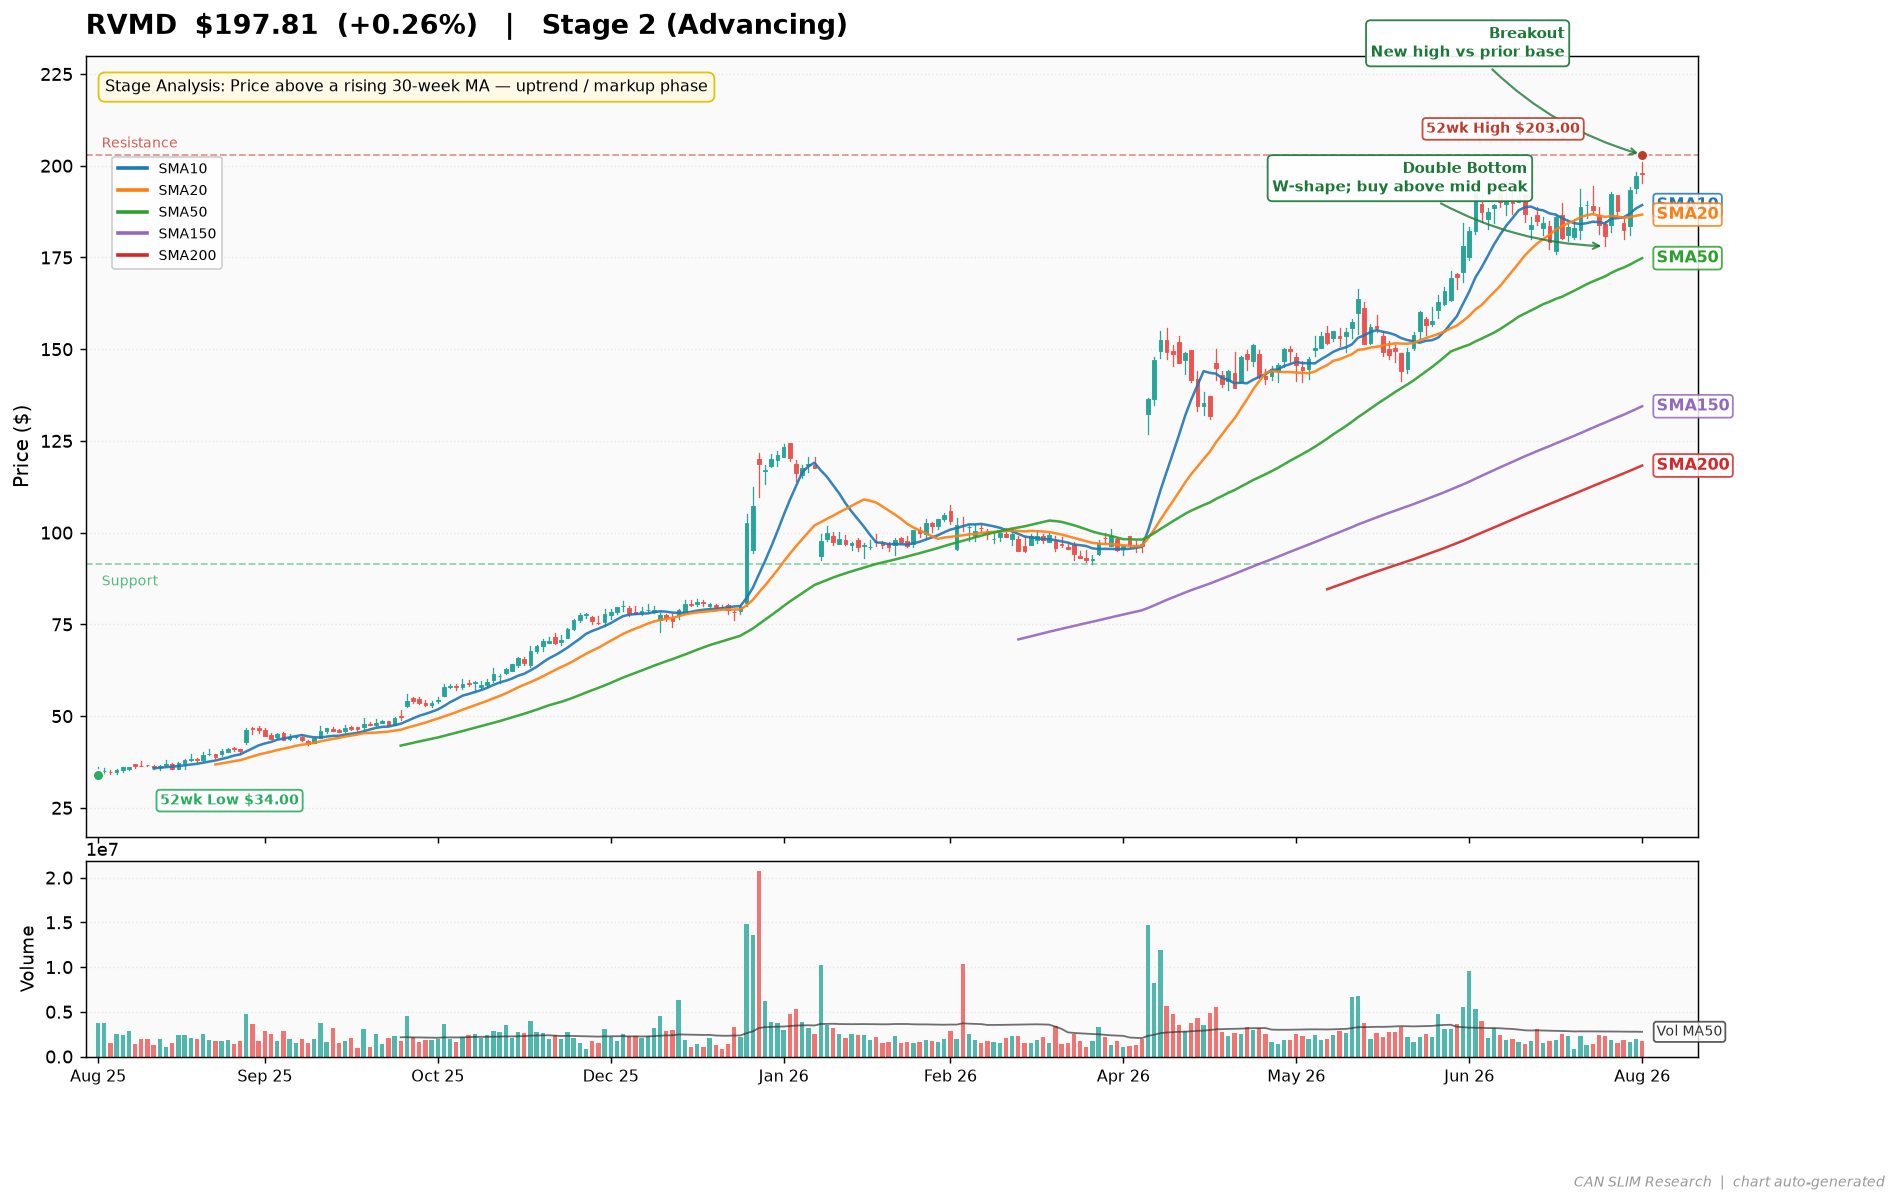
The headline from Revolution Medicines’ Q2 2026 earnings call is one of triumph: a “paradigm-shifting” Phase III result in pancreatic cancer, FDA acceptance of its NDA, and a war chest of $3.9 billion in cash. But beneath the celebratory tone lies a more troubling reality. The company’s net loss ballooned to $644 million in Q2 2026, a staggering 160% increase from the $248 million loss recorded in the same quarter last year. This is not a company merely investing for growth; it is a company burning cash at an alarming rate, with R&D expenses up 76% year-over-year to $395 million and G&A expenses exploding 168% to $110 million.
The real story is the widening chasm between the company’s clinical ambitions and its financial discipline. While management touts the accelerated launch of daraxonrasib and a robust pipeline, the numbers reveal a different narrative: a clinical-stage biotech that has yet to generate a single dollar of revenue, now spending at a pace that would exhaust even its massive cash reserves in roughly 18 months if the burn rate continues to accelerate. The 49.81% earnings miss (actual EPS of -$3.06 vs. estimate of -$2.04) is not a rounding error; it is a signal that the company’s cost structure is spiraling out of control even as it approaches its most critical commercial milestone.
Continue Reading With a Free Account
Create a free account to see the full scanned list, new entries and chart analysis. No card needed.
Create Free AccountContinue With GoogleAlready registered? Sign in