Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
ACM Research’s Q2 beat is a mirage: 36% revenue growth is China-dependent, and EPS was flattered by a one-time gain. With 80%+ revenue from China, the geopolitical risk is a ticking bomb. Read the full analysis to see why the ‘multi-product’ story is a distraction.
The Lede and the Real Story
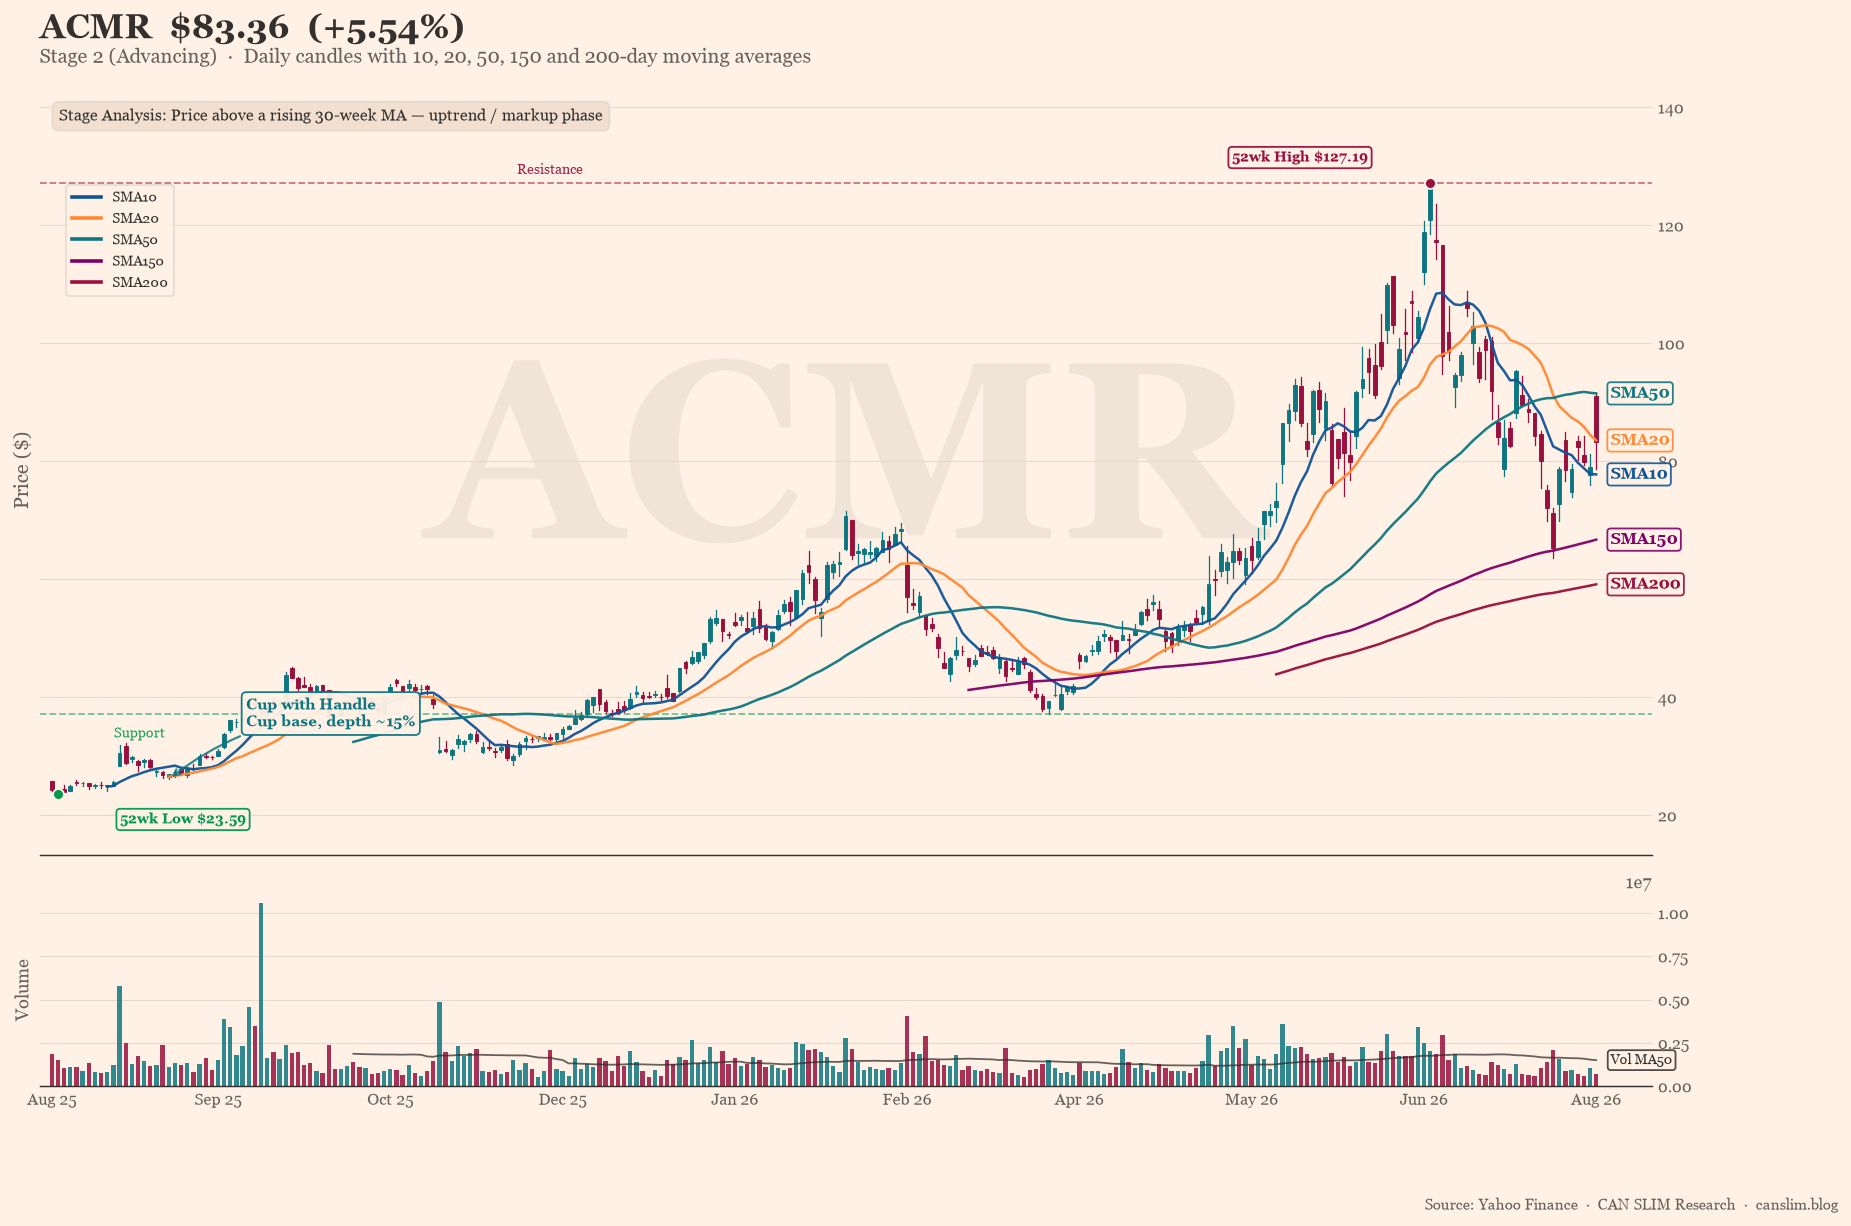
ACM Research reported a headline-grabbing second quarter: revenue surged 36% year-over-year to $292.92 million, beating analyst estimates by nearly 9%, and non-GAAP EPS of $0.61 crushed expectations by 45.7%. Management raised full-year guidance to $1.125–$1.175 billion, implying 25% growth. On the surface, this is a growth story firing on all cylinders. But beneath the optics lies a more uncomfortable reality: the company’s growth is increasingly tied to a single, politically fraught market—China—and the margin expansion that drove the EPS beat is not the clean operational story it appears to be.
The real story is that ACM’s revenue surge is almost entirely dependent on Chinese semiconductor fabs racing to build capacity before export controls tighten further. While management touts diversification into ECP and advanced packaging, the geographic concentration is a ticking time bomb. The 36% revenue growth is impressive, but it comes with a 150% surge in ECP and packaging—categories that are still a small base and are heavily China-centric. The EPS beat, meanwhile, was flattered by a one-time gain from the ACM Shanghai share sale, which raised $110 million in Q1. Strip that out, and the ‘clean’ earnings picture is far less spectacular.
Investors are buying a narrative of a multi-product global champion, but the numbers tell a story of a company that is, for now, a China play with a U.S. listing. The question is not whether Q2 was good—it was—but whether the growth is sustainable when the geopolitical winds shift.
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion