Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
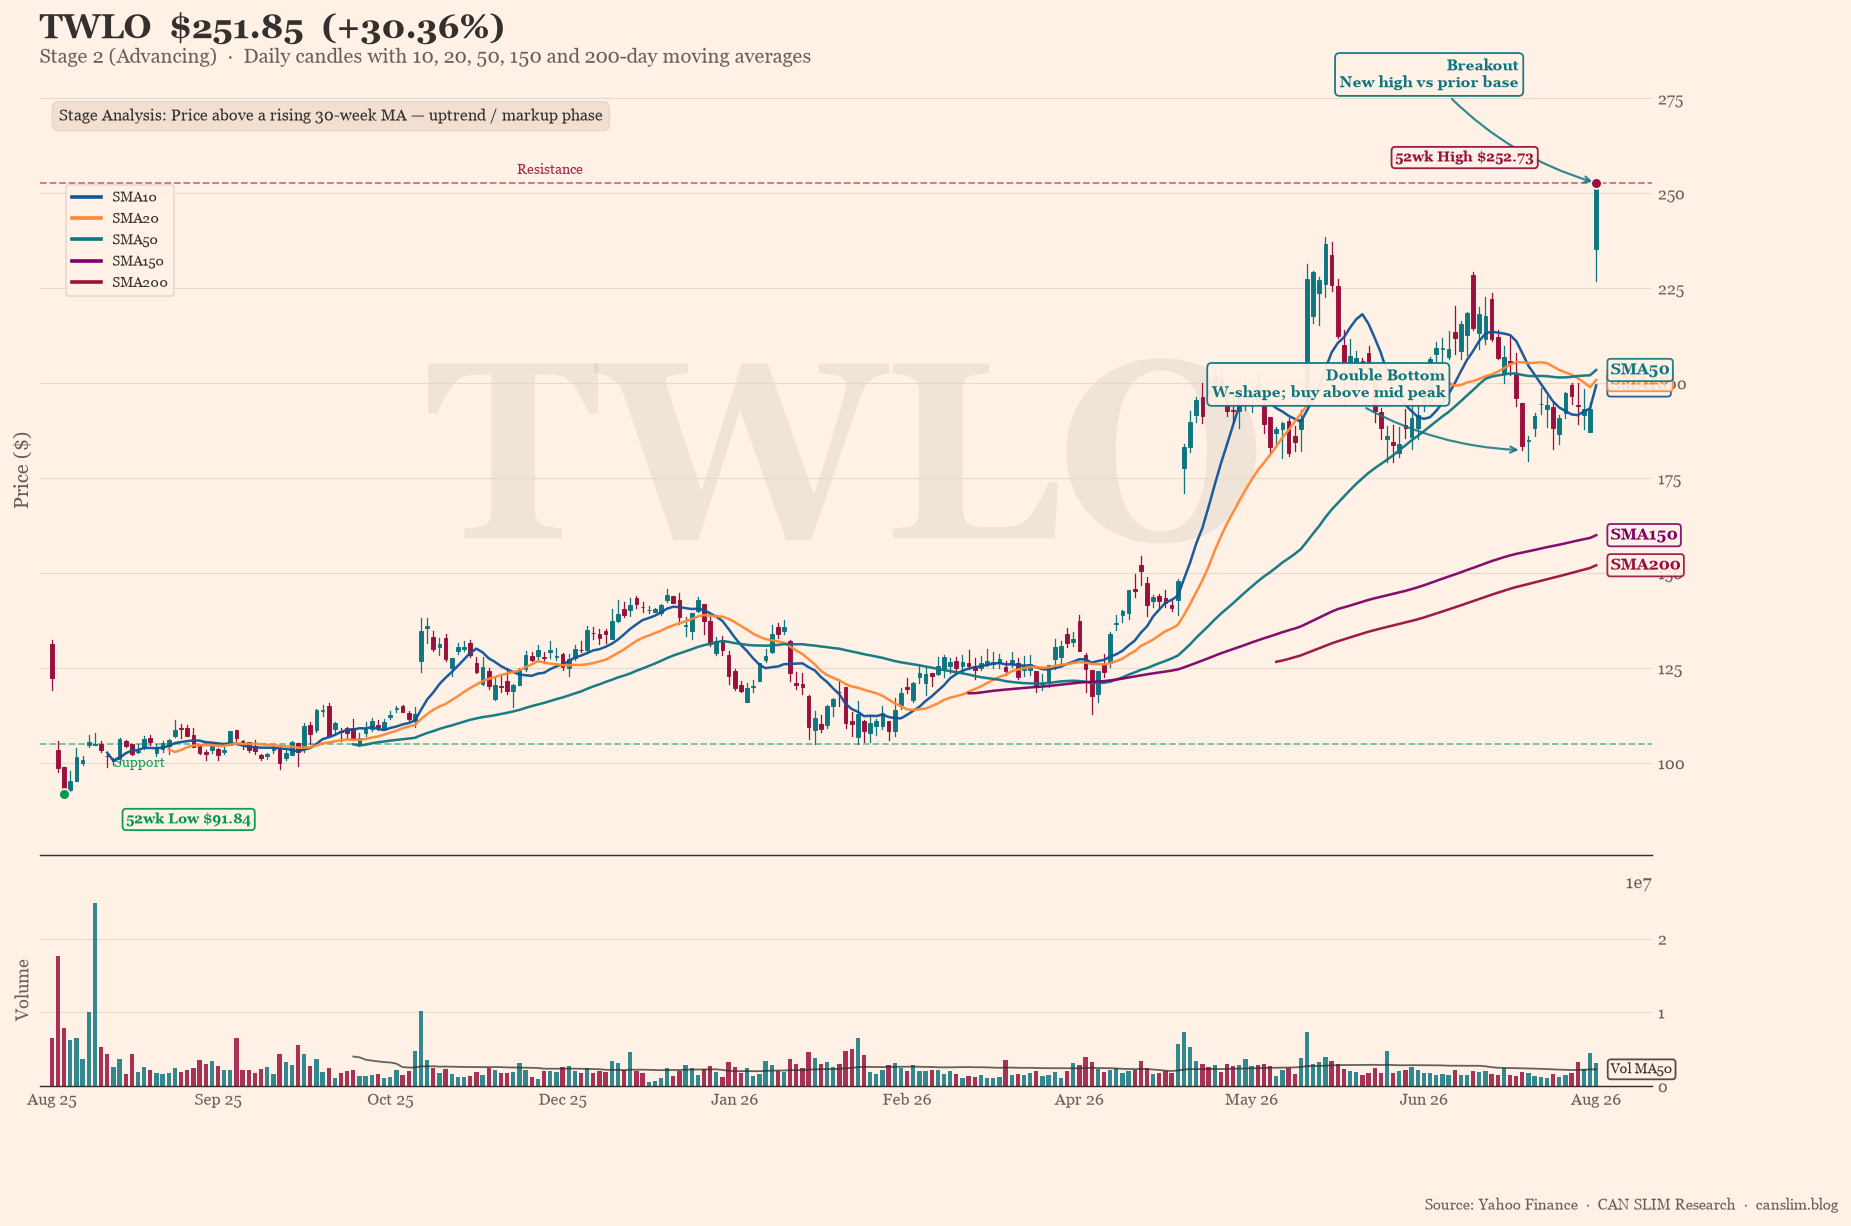
Twilio’s Q2 beat hides a shrinking core: 22% reported growth is flattered by acquisitions, while AI revenue remains unquantified. EPS beat is non-GAAP, with $235M in stock comp. Is the 30% pop justified? Read the full breakdown.
The Lede and the Real Story
Twilio’s Q2 2026 earnings call was a masterclass in narrative control. The headline numbers are undeniably strong: revenue hit $1.50 billion, up 22% year-over-year on a reported basis, with non-GAAP EPS of $1.47 beating estimates by 11%. Organic growth accelerated to 17%, and the company raised full-year guidance. The stock popped 30% after hours, a clear retail and institutional stamp of approval. But beneath the AI-infused optimism lies a more uncomfortable truth: the core communications business—the one that generates the vast majority of revenue—is growing at a fraction of the touted rate, and the company’s celebrated profitability is increasingly a product of cost-cutting, not top-line vigor.
The real story is the widening gap between the AI narrative and the underlying economics. Management leaned heavily on ‘AI-driven demand’ and ‘voice reimagined through AI,’ yet the actual numbers reveal that the legacy messaging and voice products—which still dominate the revenue mix—are growing in the low single digits. The 22% reported growth is flattered by acquisitions and a one-time benefit from carrier fee pass-throughs. When you strip those out, the organic growth of 17% is still respectable, but it masks a core that is barely keeping pace with inflation. The question investors should be asking is not whether Twilio is a good company, but whether it is a good growth stock at 12x forward sales.
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion