Andrew
General educational commentary only, generated automatically with AI. Not investment advice or a recommendation to buy, sell or hold any security. Capital is at risk.
Broad Index Gains Follow Midterm Result
U.S. stocks rose sharply on Wednesday after Democrats won control of Congress, according to the news brief. The Dow gained 3.0%, its strongest day in 18 months, as reported by MarketWatch. The S&P 500 added 1.6% and the Nasdaq rose 1.4%. Oil prices fell and long-term Treasury yields reached eight-week lows, The Wall Street Journal reported. The brief says investors are betting that divided government could limit policy surprises. It also says they expect pressure to end the Iran war, which may reduce energy and geopolitical risks.
Technology Shares Stay under Pressure
The rally did not lift every part of the market. The news brief says AI and semiconductor shares remain under pressure. Investors are questioning whether heavy data-center spending will produce returns soon enough. A research firm, cited by MarketWatch, argues that easy, broad-based gains from the AI trade may be over. The same report says stock selection may matter more now. The Wall Street Journal describes how a data-center backlash could play into the hands of some large platforms if development slows and weaker competitors are squeezed. The brief notes this does not remove the risk of further valuation pressure.
Oil, Yields and the Iran Question
Oil prices stayed below $100 as traders weighed Iran diplomacy and supply, The Wall Street Journal reported. Treasury yields fell to eight-week lows as markets digested the midterm results. But the brief says markets may be too quick to assume geopolitical risk is fading. A strategist told MarketWatch that a prolonged war in Iran is the market's real "black swan." A longer conflict could reverse the drop in oil and revive inflation concerns. The brief states the market may be underestimating that risk.
Online Sentiment Tilts Cautious on Growth Themes
Online sentiment comes from unverified posts by anonymous retail users, which may include rumour or speculation and has not been checked. In these posts, tone around AI and semiconductor themes appears more cautious than it was earlier in the year, based on the source summary. Some posts discuss whether the AI trade has changed character. Others focus on the gap between index-level strength and weakness in chip-related names. This is theme-level chatter only. It is not institutional flow, confirmed positioning or "smart money." One reading is that retail discussion is reflecting the same split the news brief describes: broad relief at the index level, and doubt inside technology.
Options Pricing and the Jobs Report Test
The brief cites CNBC International TV, where Scott Nations said options markets may be too quick to price out risk after the election rally. Reduced downside protection could leave markets exposed to upcoming data and policy surprises. Friday's U.S. jobs report is described as a near-term test for the rally and for interest rate expectations. The brief also lists what to watch: moves in oil and Treasury yields, and whether AI weakness spreads beyond chips and infrastructure. These are risks and uncertainties, not forecasts.
A Chart Screen Flags One Name for Weakness
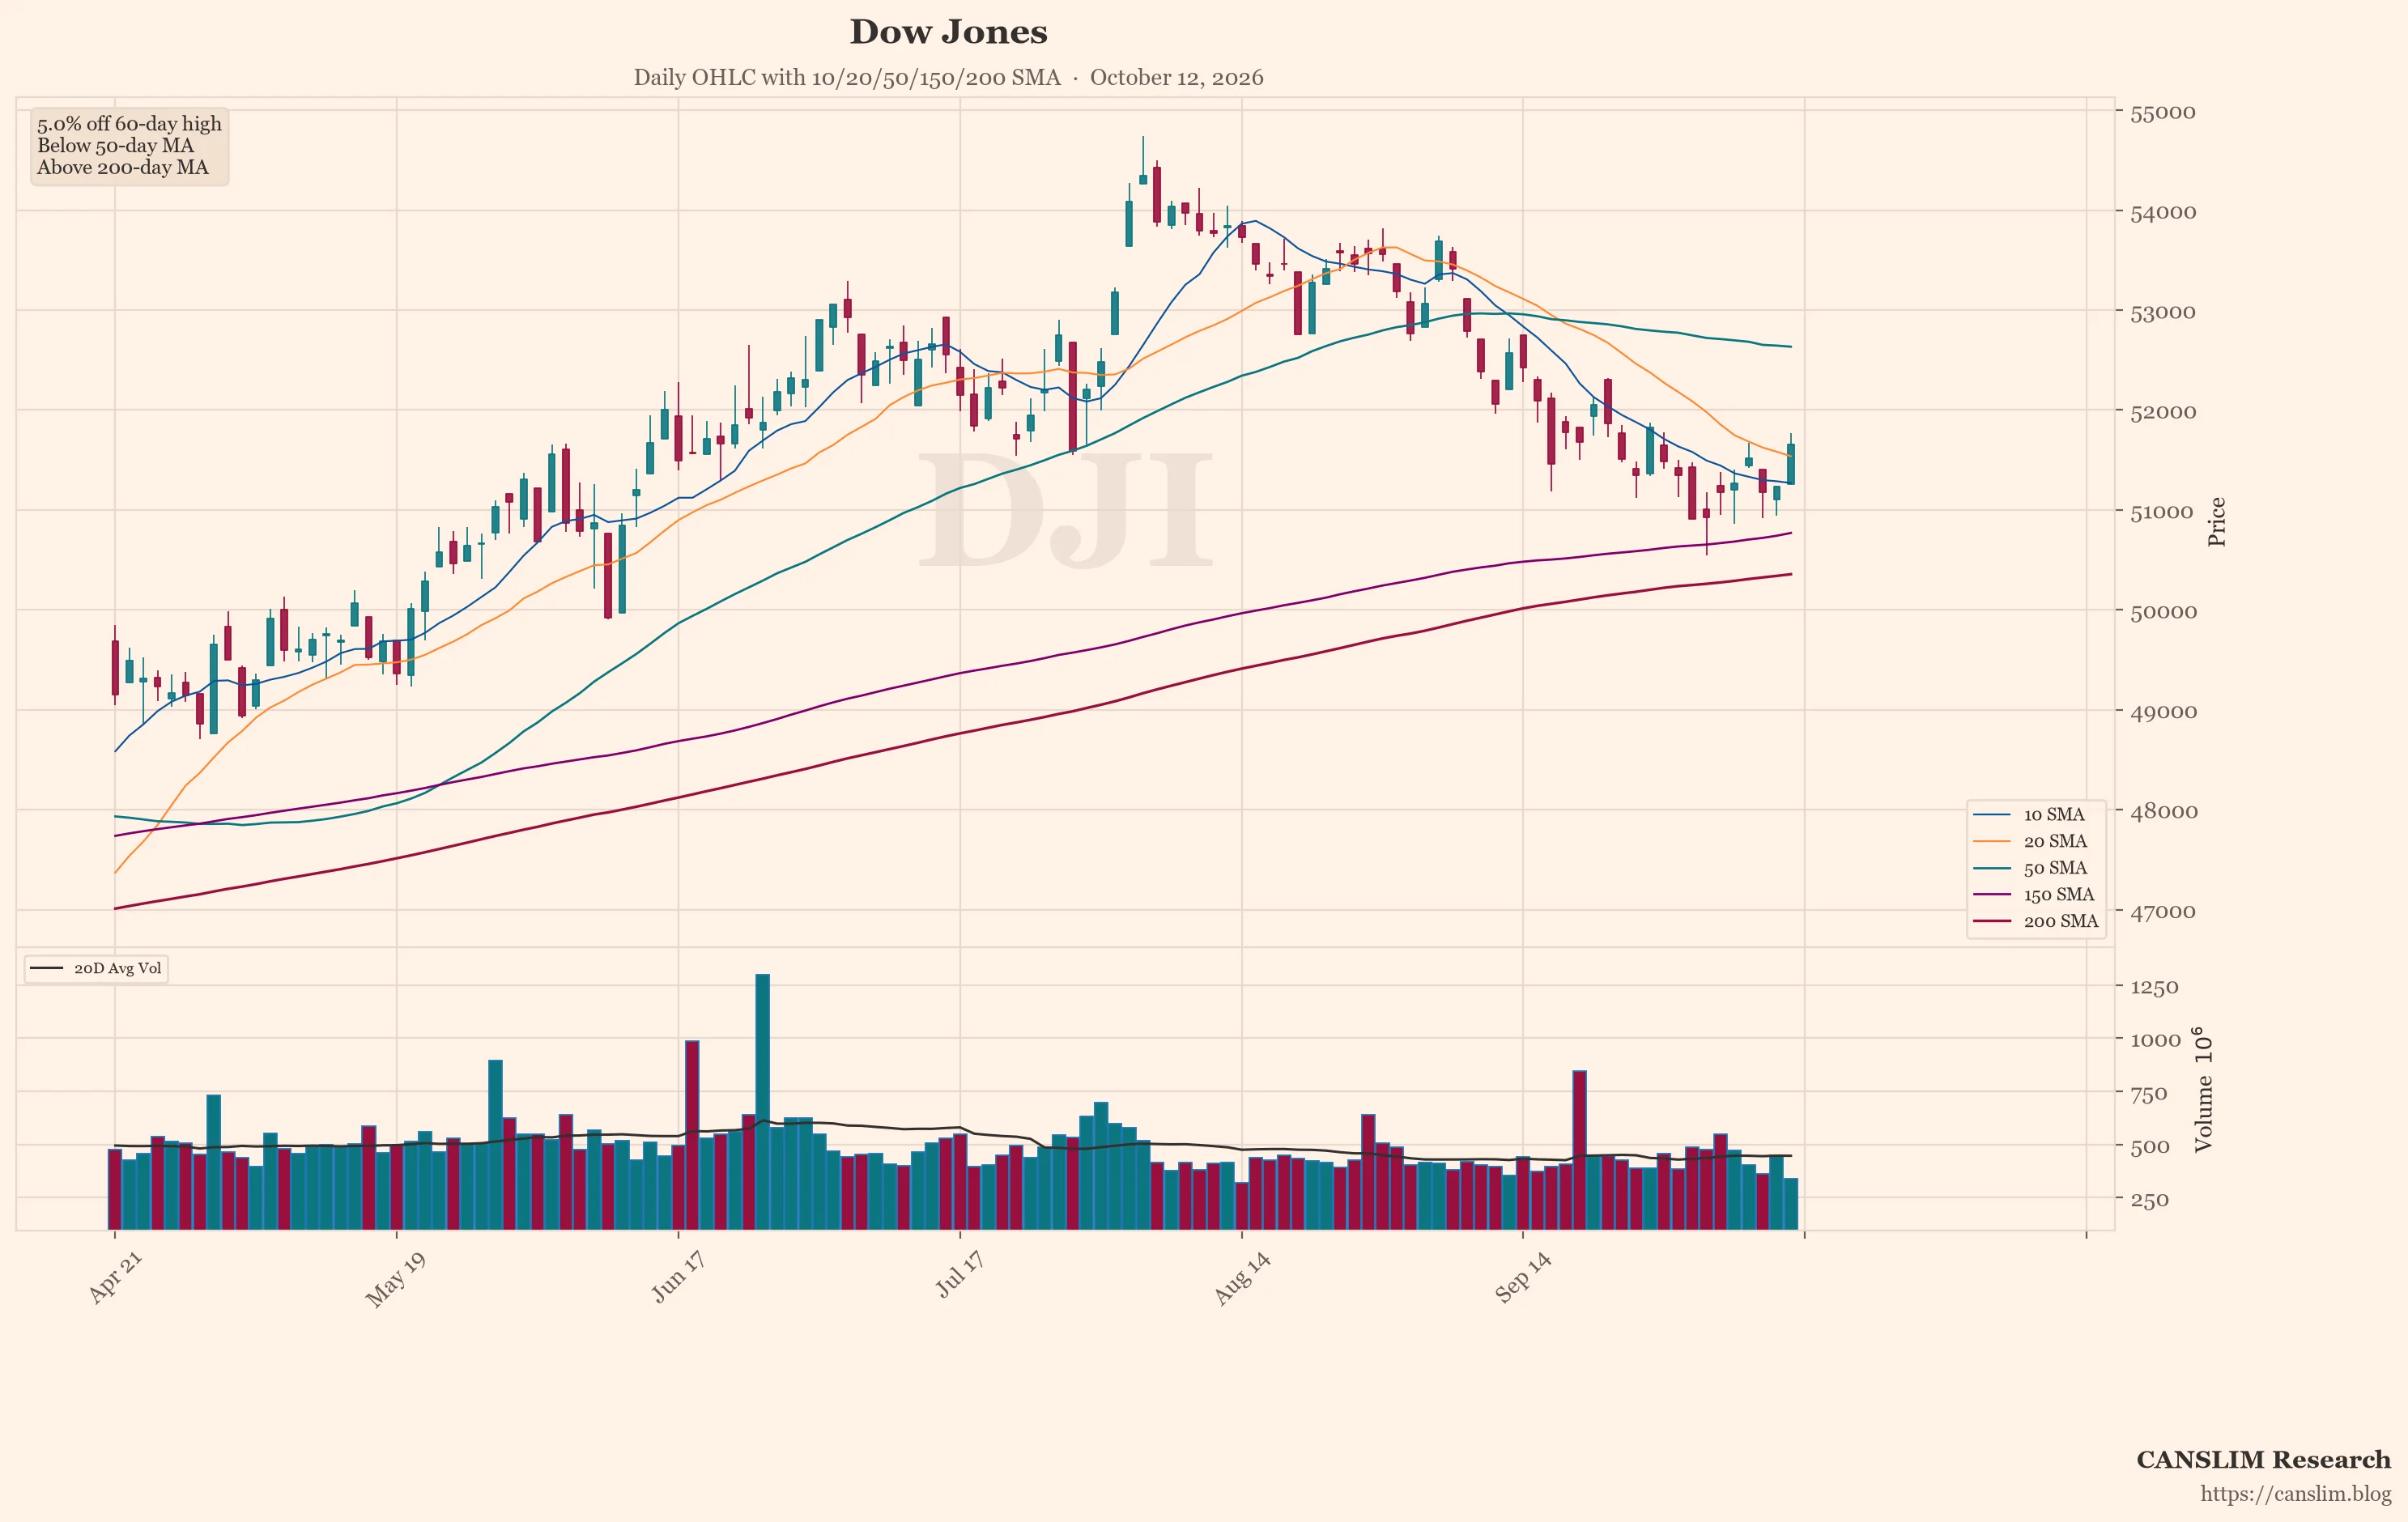
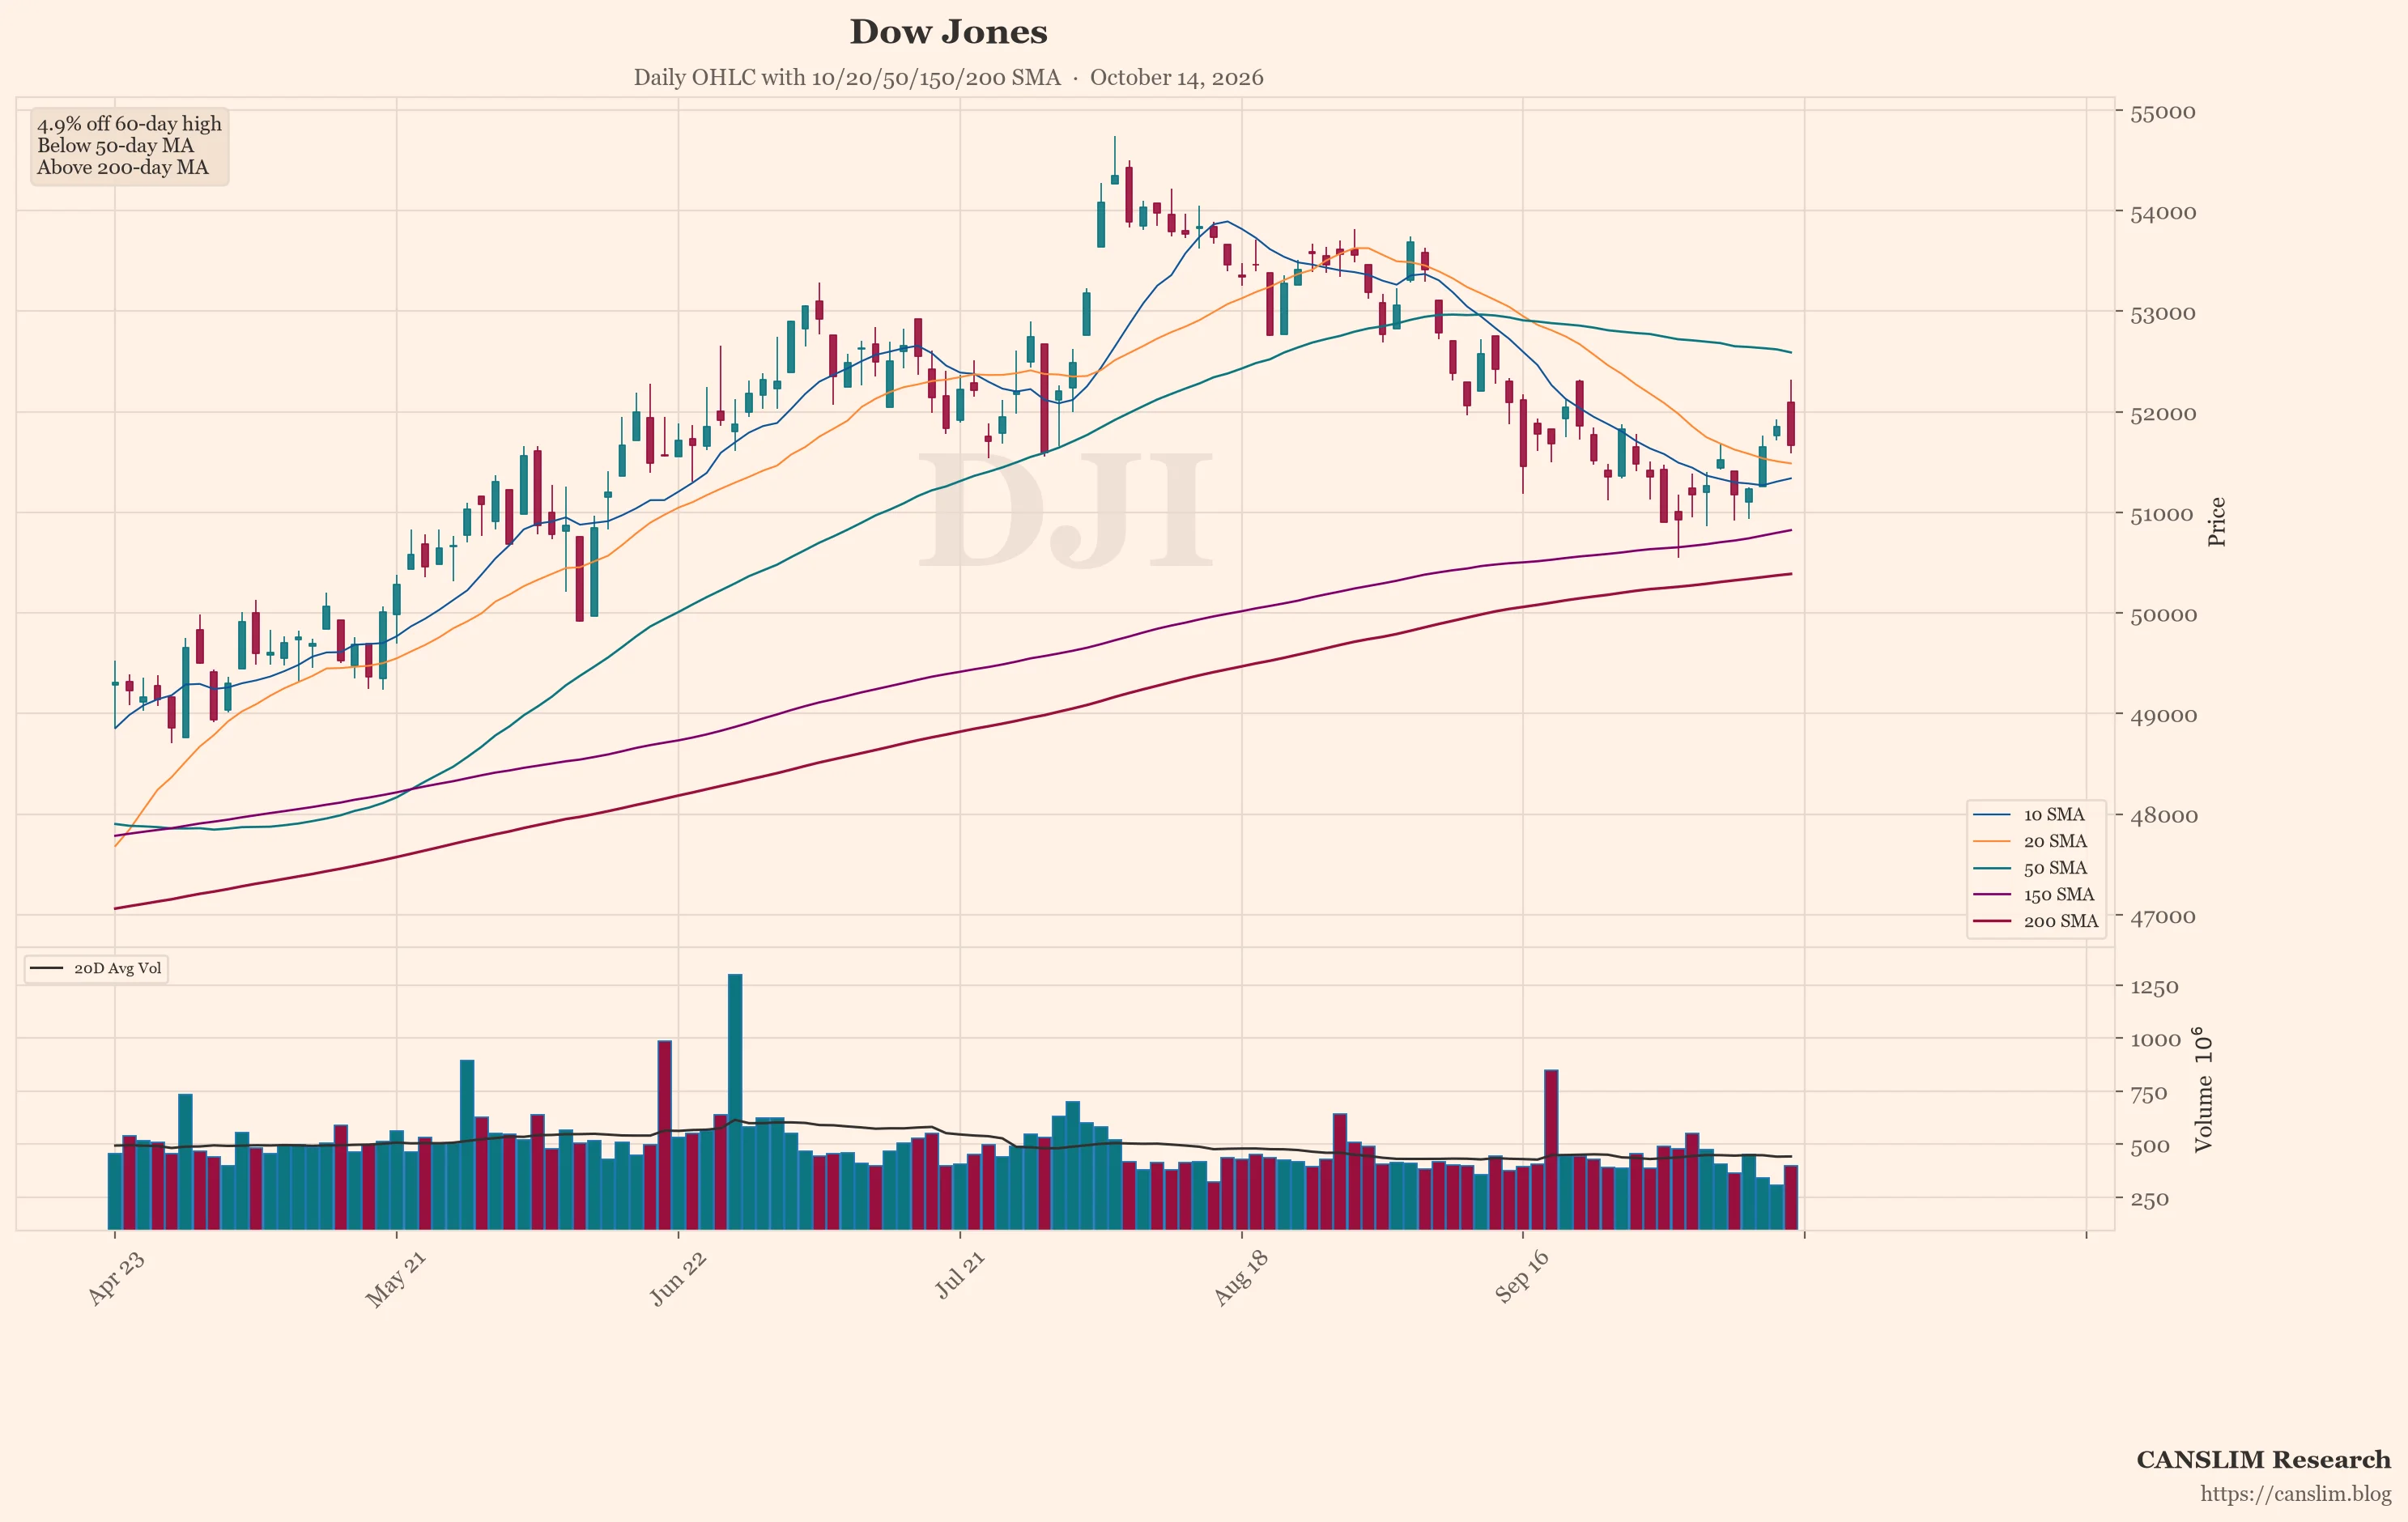
The featured chart shows TV. An automated technical screen picked it because, among the indices and stocks it checked, it showed the most weakness on a few measures. These include distance from its recent high, position versus its 50-day and 200-day moving averages, and down days on higher volume. This is one screen and not a full view of the company or the market. Past price patterns do not predict future results. The reading is factual, not a signal about what may come next.
Mixed Signals Leave the Outlook Unsettled
The sources describe two forces pulling in different directions. Index-level relief followed the midterm result, with the Dow's 3.0% gain and lower oil and yields. At the same time, AI and semiconductor shares remain weak, and a research firm questions the old broad AI trade. The brief flags several risks: a longer Iran war, a possible reversal in oil, thinner options protection, and Friday's jobs report. Online sentiment, which is unverified, appears cautious on growth themes. Conditions may stay mixed while data and policy news arrive.
Sources: a third-party AI-generated market news summary, and an AI summary of unverified posts by anonymous retail users online. This article was written by an AI language model from those summaries and published automatically without human review. Updated 2026-11-05 22:00 HKT.
CANSLIM Research (canslim.blog) is an independent educational publisher. It is not licensed or registered as a broker, investment adviser, research analyst or asset manager in any jurisdiction. This article is general information for education only. It is not investment advice, a research report, an investment recommendation, or an offer or solicitation to buy or sell any security, and it does not consider any reader's objectives, financial situation or needs. No ticker, chart, heading or technical comment is a suggestion to buy, sell, hold or short. Figures come from third-party sources, are not independently verified, and may be incomplete, out of date or wrong. Online sentiment may include rumour, speculation or coordinated posting. Past performance and past price patterns do not predict future results. Investing involves risk, including the loss of capital. This article is not updated after publication. Laws differ by country; seek advice from a licensed professional in your jurisdiction before making any investment decision.