Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
Cisco's record Q4 hides a decelerating order book and vague AI revenue. Stock popped 2.86% after hours, but the real story is in what they didn't say. Is the AI super cycle real or a mirage? Read the full analysis to see the cracks beneath the spin.
The Lede and the Real Story
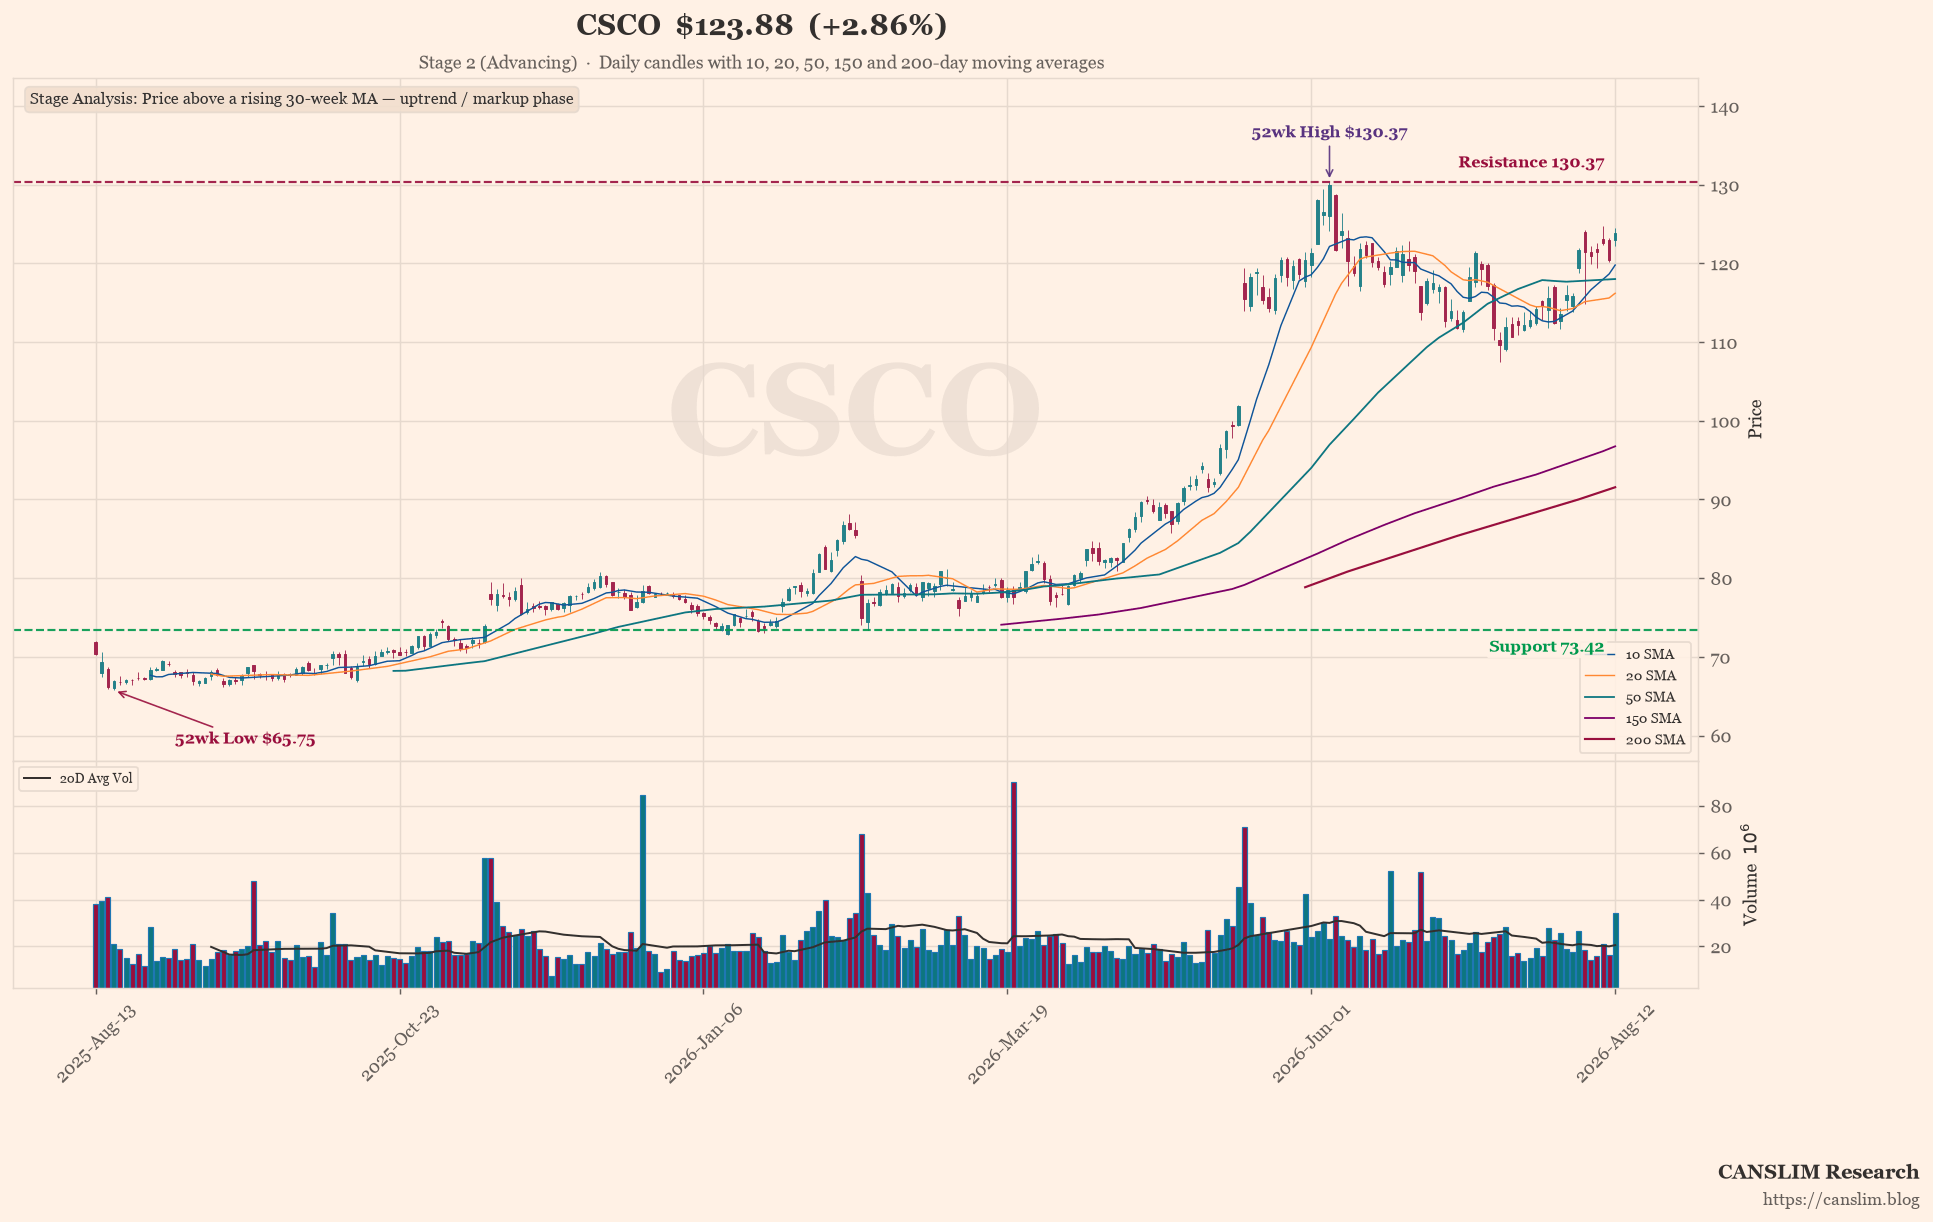
Cisco Systems closed fiscal 2026 with a headline that would make any CEO salivate: record revenue of $63 billion, up 12% year-over-year, and a Q4 that management called “very strong.” The stock popped 2.86% in after-hours trading to $123.88, and the press release screamed “record revenue and earnings growth driven by AI and networking.” But beneath the polished surface lies a more complicated story—one of a company that is riding an AI wave it didn’t create, while its core business shows signs of strain that the scripted remarks conveniently gloss over.
The real tension this quarter is not whether Cisco grew—it did, and impressively—but whether that growth is sustainable, high-quality, and broad-based. The Q4 transcript reveals a company leaning heavily on the “agentic AI” narrative to justify a networking super cycle, yet the numbers tell a more nuanced tale. Product orders grew 35% year-over-year in Q3, but Q4’s revenue of $17 billion (the transcript cuts off mid-sentence, but the estimate was $16.84 billion) suggests a deceleration from the 12% growth rate that carried the full year. Meanwhile, non-GAAP EPS of $1.17 beat estimates by a hair, but the quality of that earnings power is questionable—driven by buybacks and cost cuts rather than organic operational leverage.
The story beneath the spin is that Cisco is a mature networking giant that has hitched its wagon to the AI infrastructure boom, but the boom is concentrated in a handful of hyperscaler customers, and the company’s traditional enterprise and service provider markets are not growing at the same clip. Management’s forward guidance for FY2027—”double-digit” growth—is a promise, not a guarantee, and the transcript shows they were unwilling to provide specific numbers, a tell that they may be less confident than their rhetoric suggests.
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion
Discover more from CANSLIM Research
Subscribe to get the latest posts sent to your email.