Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
CoreWeave’s Q2 revenue doubled to $2.6B, but a $626M net loss and $640M interest expense reveal a debt-fueled growth story. The $104B backlog masks customer concentration risks. Can they cover interest costs? The real story is in the balance sheet. Read the full analysis.
The Lede and the Real Story
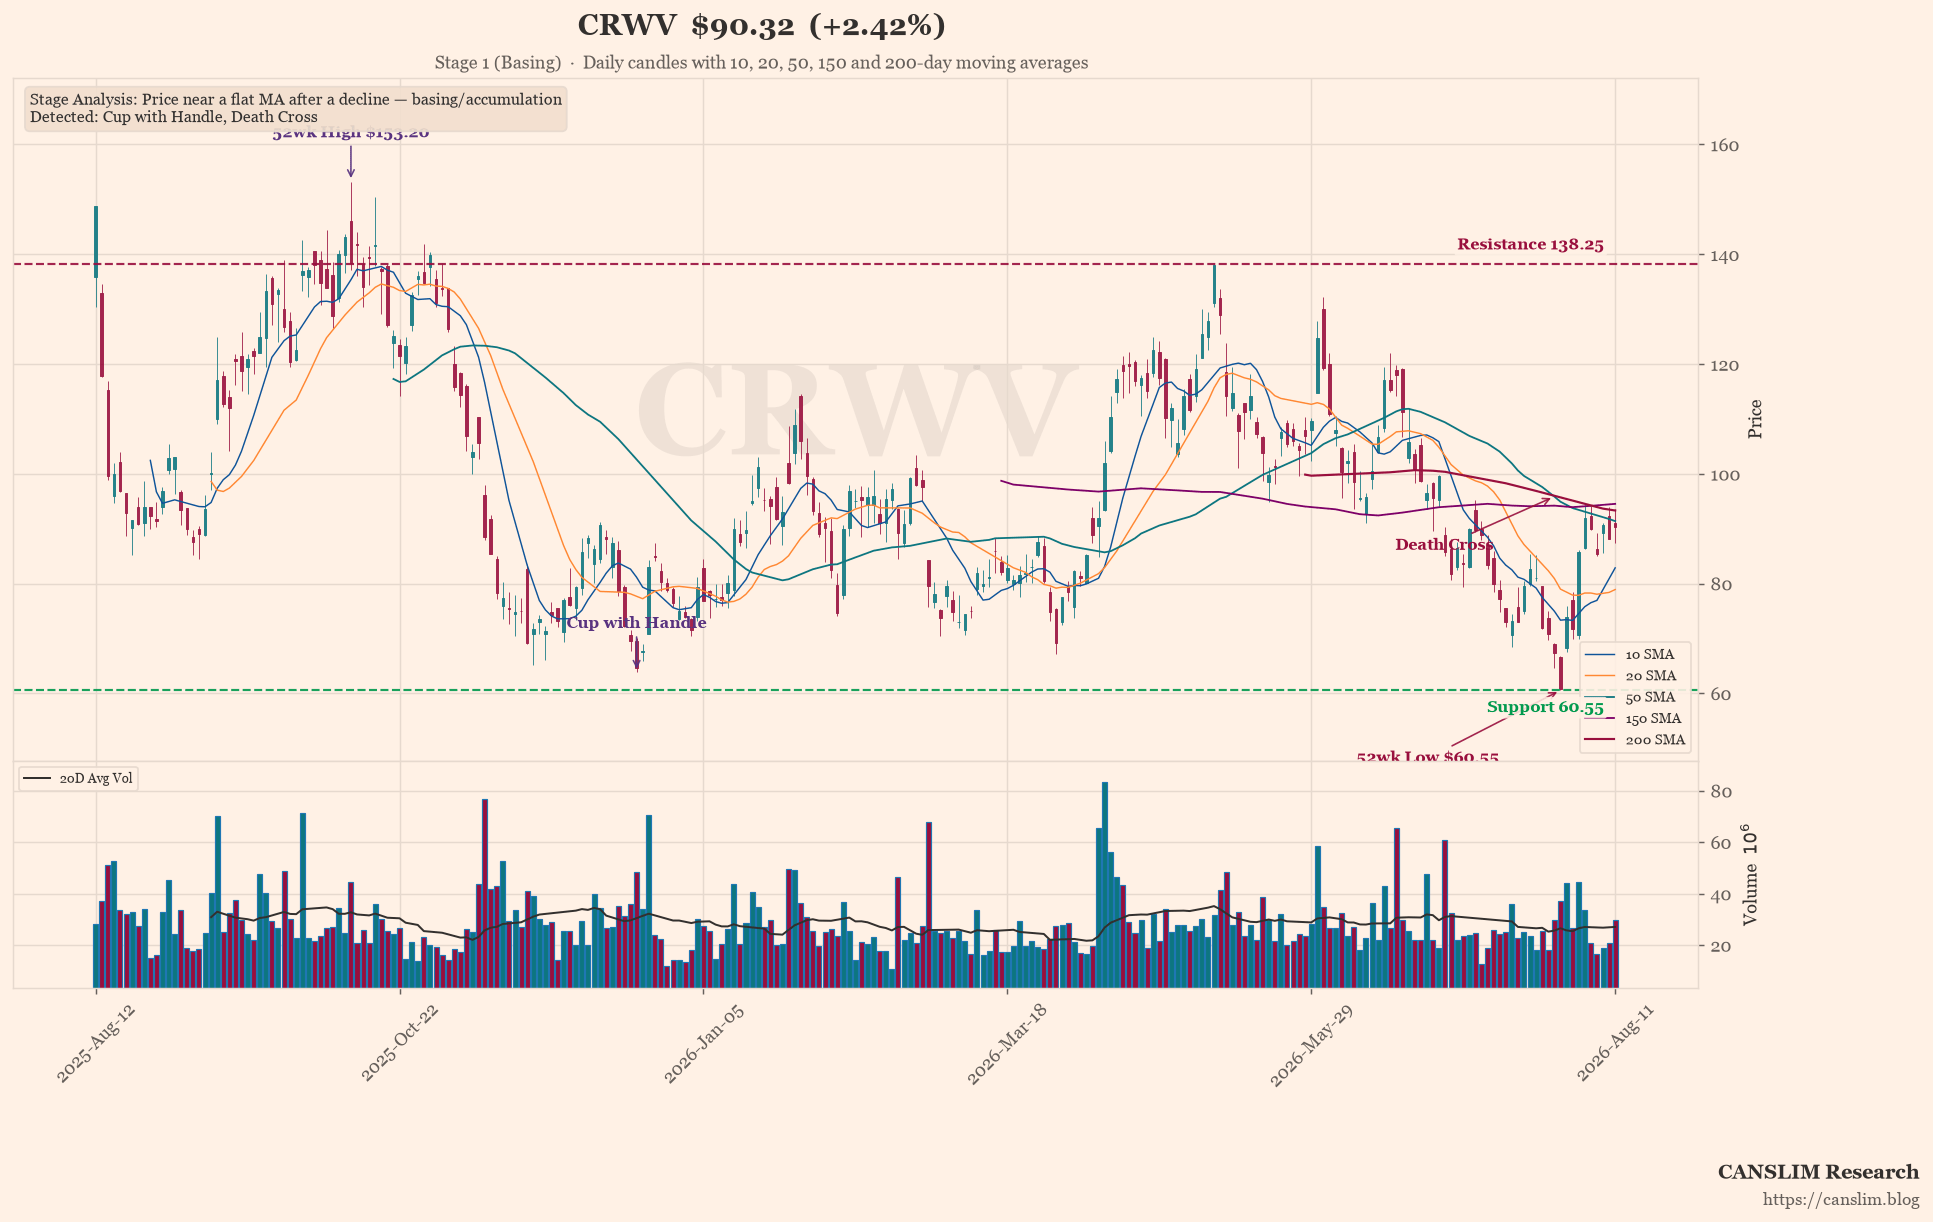
CoreWeave reported a headline-grabbing quarter: Q2 2026 revenue of $2.6 billion, up 112% year-over-year, with adjusted EBITDA of $1.5 billion (a 59% margin) and a backlog that management claims has swollen to $104 billion. The stock popped 2.42% in after-hours trading, and the company raised its full-year revenue guidance to $12.4–$13.2 billion. On the surface, this is a hypergrowth AI infrastructure story firing on all cylinders.
But beneath the polished numbers lies a far more uncomfortable reality. CoreWeave is not a profitable company by any conventional measure. It posted a net loss of $626 million in the quarter, driven by $640 million in interest expense — a figure that has more than doubled from $267 million a year ago. The company is funding its breakneck expansion almost entirely through debt, having raised $18 billion in Q2 alone, and its adjusted operating income of just $128 million (a razor-thin 5% margin) is dwarfed by the interest bill. The real story is not growth; it’s the widening chasm between the company’s operational earnings and the cost of the capital required to sustain that growth. Investors are being sold a narrative of AI-driven prosperity, but the balance sheet tells a tale of a highly leveraged bet on a future that may not materialize as quickly — or as profitably — as the script suggests.
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion
Discover more from CANSLIM Research
Subscribe to get the latest posts sent to your email.