 Andrew
General educational commentary only, generated automatically with AI. Not investment advice or a recommendation to buy, sell or hold any security. Capital is at risk.
Producer Prices Rise and Rate Fears Return
The news brief reports that October producer prices rose 0.3% month over month. This was a little less than the 0.4% forecast. However, the annual increase reached 6.5%. According to the brief, this is the largest annual gain since November 2022. Reuters reported the producer price data. The cooler monthly reading gave some relief. Still, the brief says it did not change the broader concern that inflation is broadening.
Fed Officials Signal More Hikes May Be Needed
Several Federal Reserve officials said inflation remains too high. Reuters reported that Daly said the Fed likely needs to raise rates amid worsening inflation. Reuters also reported that Collins said more rate hikes are coming, citing Bloomberg Television. The brief states that this is a headwind for stock valuations and for businesses that borrow money. The 10-year Treasury yield climbed above 5%, according to Seeking Alpha. The brief says this raises the hurdle for equities and adds pressure to technology shares.
Indexes Give Back Early Gains as AI Shares Slip
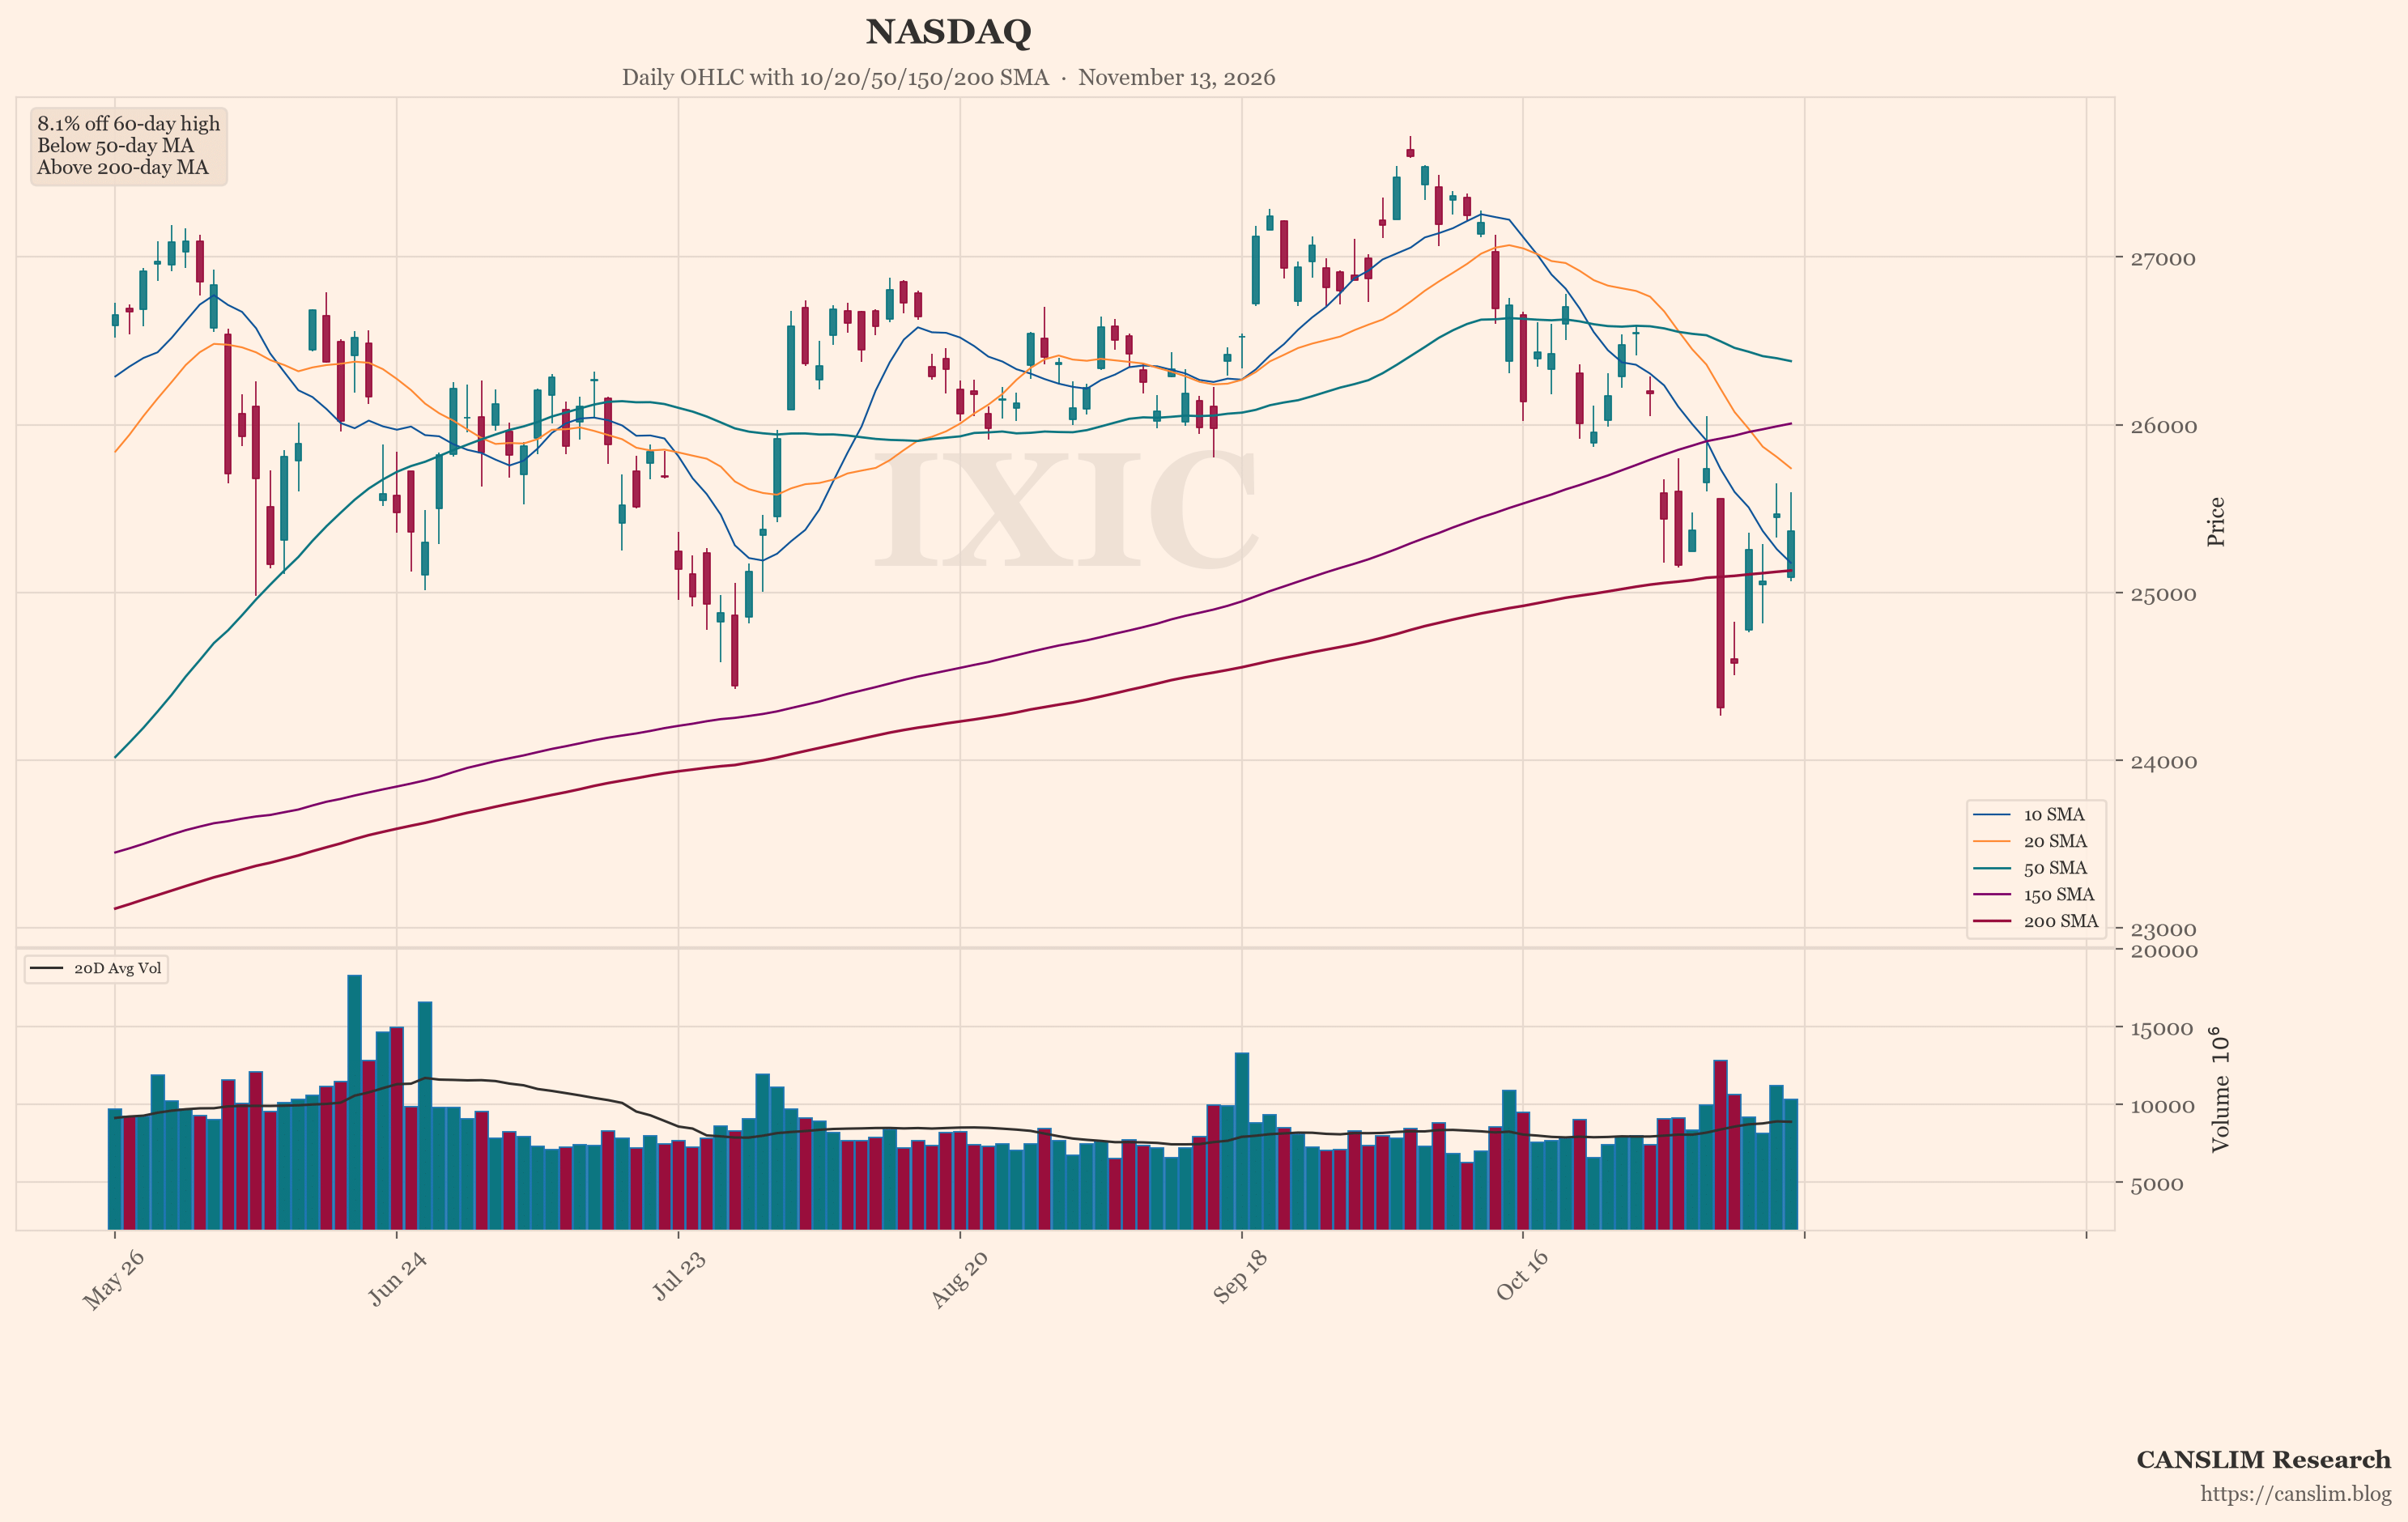
Stocks had a choppy session. The brief says stocks first took comfort from the PPI miss. Then the Nasdaq and S&P 500 fell as pressure returned to Nvidia and other AI-linked shares. FXEmpire reported that the Nasdaq broke below its 200-day moving average as Nvidia selling returned. Bitcoin slipped below $70,000, according to the WSJ. The brief links this to higher-rate expectations and weaker risk appetite. It also notes that AI remains a powerful investment theme. Data-center demand and chip supply-chain opportunities are still in focus. But the brief says investors are increasingly asking for clear earnings and efficient spending, not growth promises alone.
Energy Supply and Data-Center Demand Diverge
One bullish item in the brief concerns oil. It says oil supply moved above demand in October for the first time since the Iran war began. CNBC reported that Russian crude production rebounded after a Trump diesel deal, as oil markets returned to surplus. The brief says this could ease some energy-price pressure if the surplus persists. On the AI side, CNBC published a piece arguing that data-center slowdown concern is overblown. The brief keeps a neutral stance on this. It says data-center electricity demand and AI chip needs remain growth drivers, but spending discipline and earnings delivery now matter more.
Online Sentiment Tracks the Cautious Tone
Online sentiment is one input here. It comes from unverified posts by anonymous retail users, which may include rumour or speculation and has not been checked. In this material it is described at theme level only. The brief labels overall sentiment as bearish. Posts tracked in the brief lean cautious on rate-sensitive technology themes and on AI-linked names as a group. Crypto commentary also turned more defensive after the move below $70,000. This is not institutional flow or confirmed positioning. One reading is that retail tone is following the same inflation and yield headlines as the major indexes. Another reading is that theme-level caution can shift quickly when data changes.
Chart Screen Flags Producer Price Index Weakness
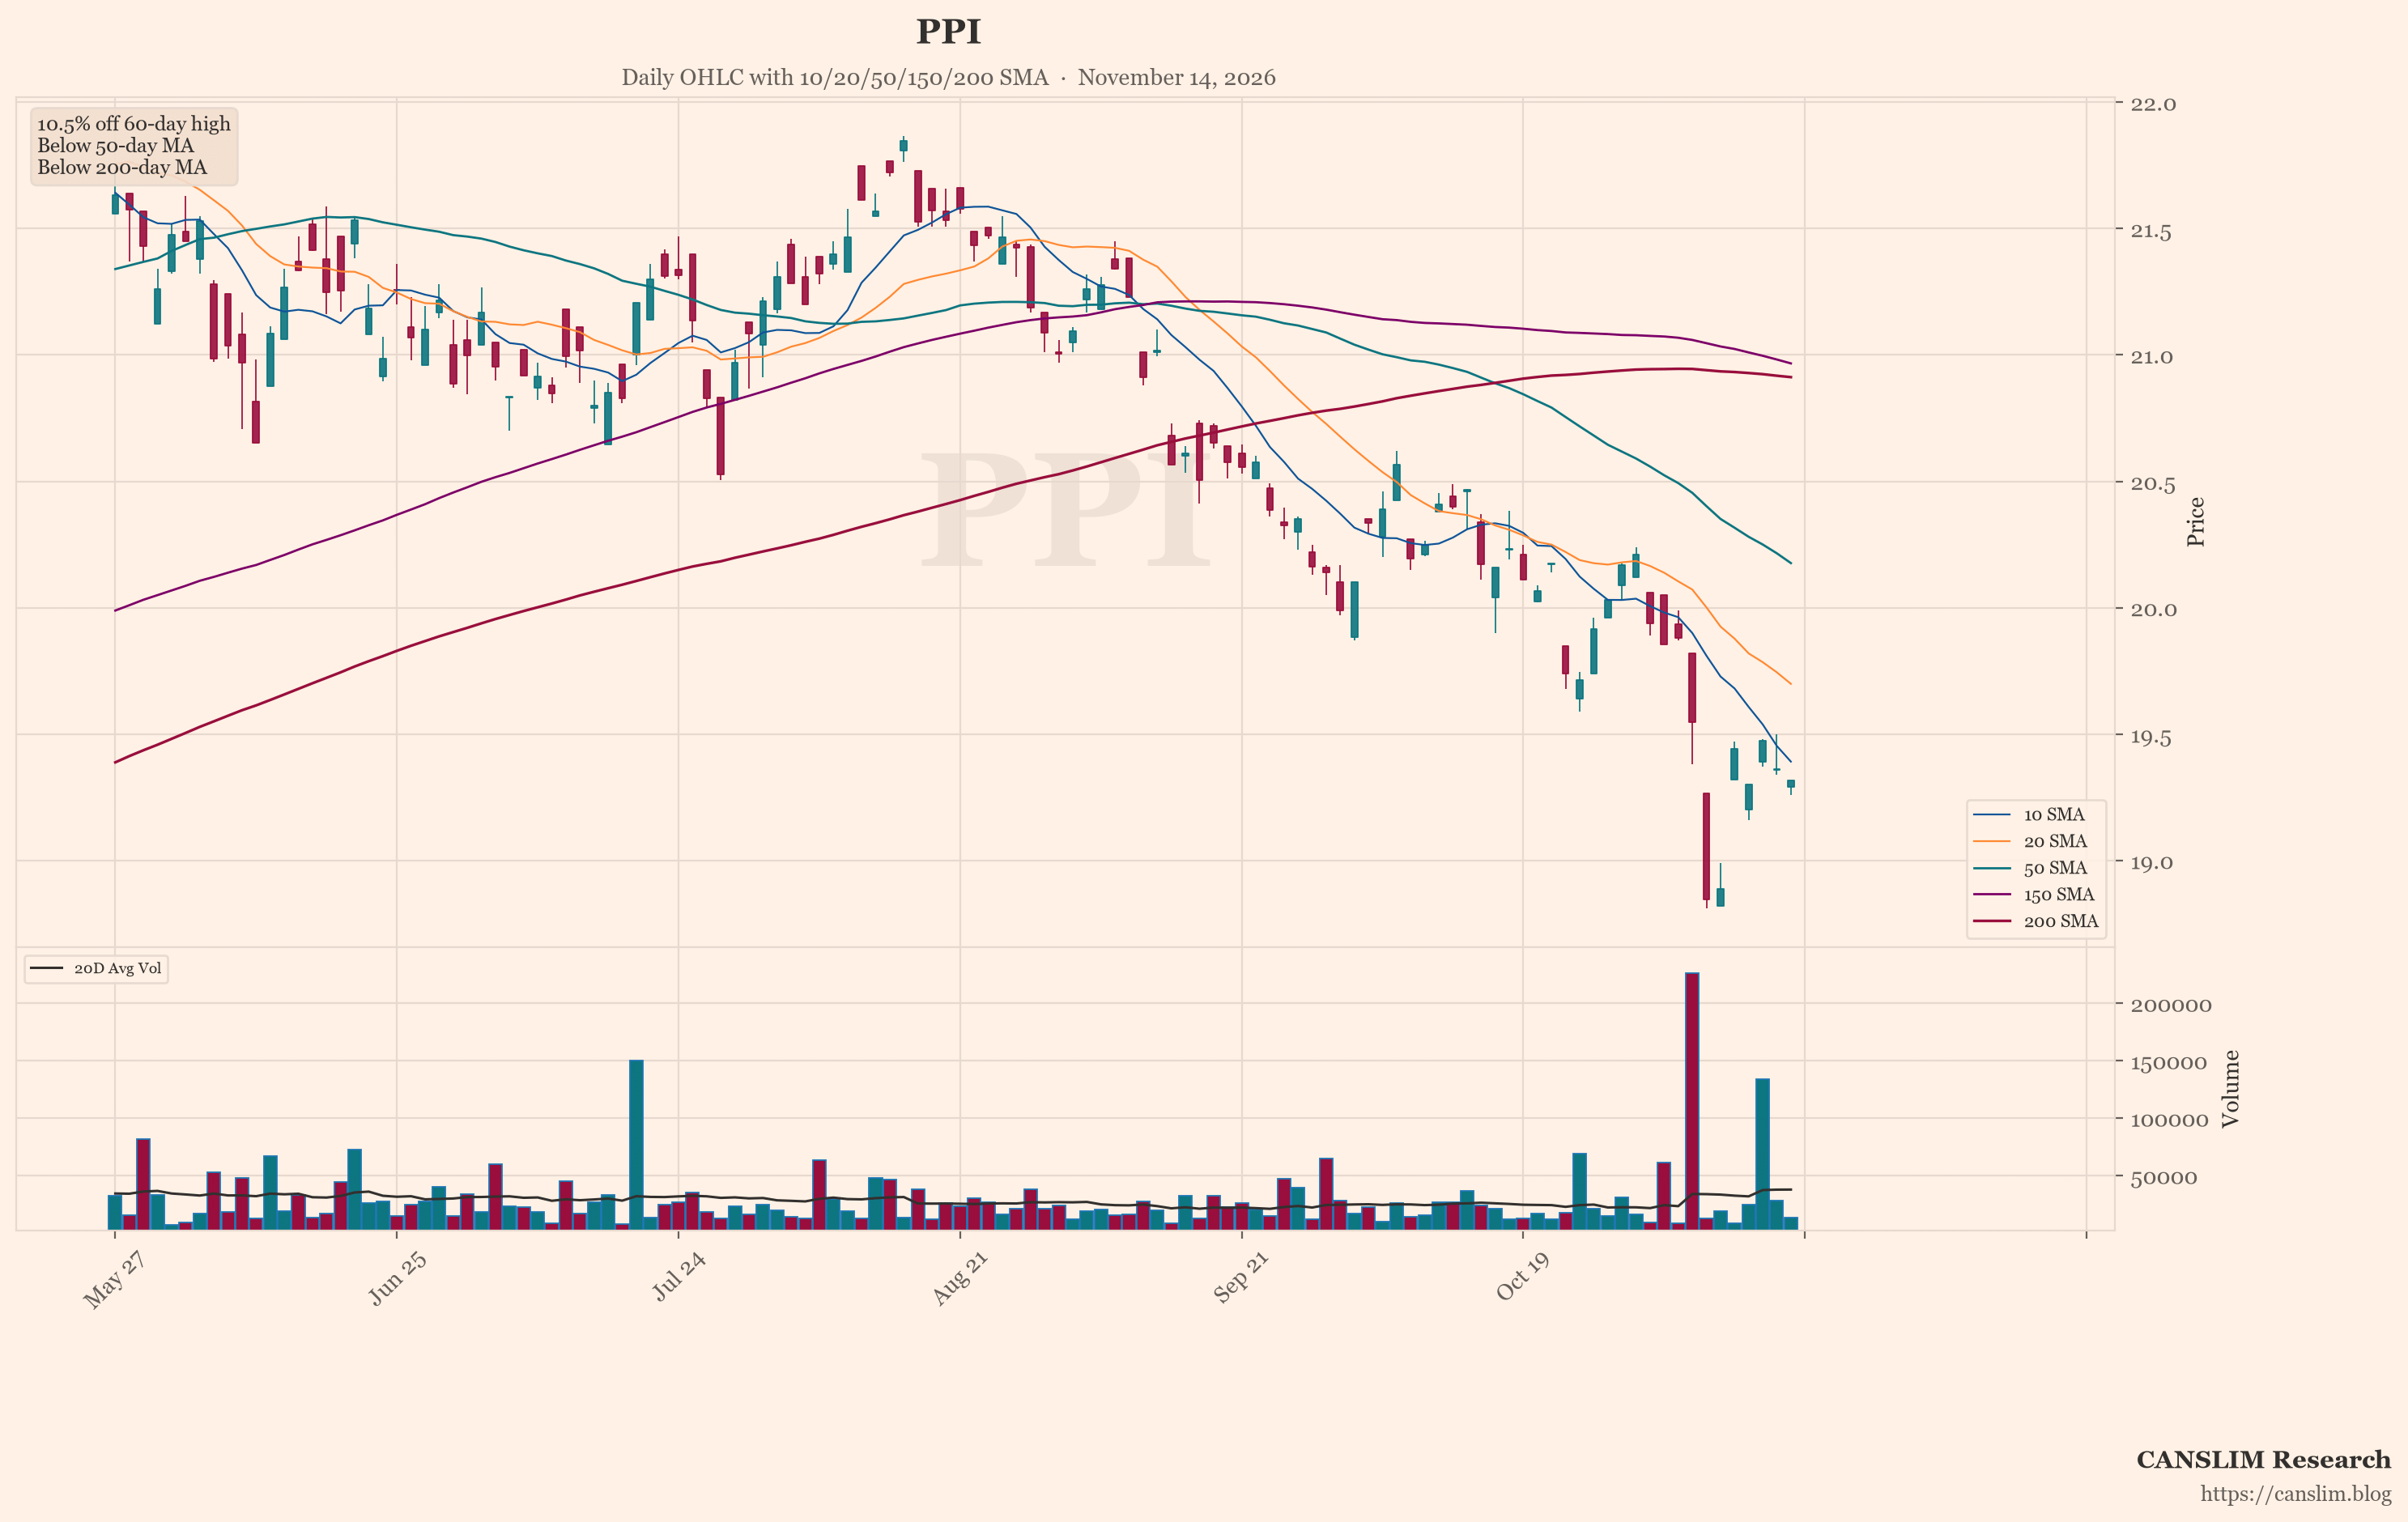
The featured chart shows the Producer Price Index (PPI). An automated technical screen picked it. Among the indices and stocks it checked, PPI showed the most weakness on a few measures. These were distance from its recent high, position versus its 50-day and 200-day moving averages, and down days on higher volume. This is a description of screen output, not a signal about any security. One screen is not a full view. Past price patterns do not predict future results.
Inflation Data and Yields Set the Tone
The brief points to several things to watch. These are upcoming Fed communications, inflation data, Treasury yields, and whether AI-related selling spreads beyond the biggest technology names. The balance of the material is cautious. Inflation is running at a multi-year high on an annual basis. Officials have signaled that more hikes may be needed. Yields above 5% pressure valuations. AI leadership is facing harder questions about earnings. Offsetting items include the softer monthly PPI reading and the oil surplus. The direction of yields and inflation data remains uncertain, and sentiment measures can change without notice.
Sources: a third-party AI-generated market news summary, and an AI summary of unverified posts by anonymous retail users online. This article was written by an AI language model from those summaries and published automatically without human review. Updated 2026-11-14 06:00 HKT.
CANSLIM Research (canslim.blog) is an independent educational publisher. It is not licensed or registered as a broker, investment adviser, research analyst or asset manager in any jurisdiction. This article is general information for education only. It is not investment advice, a research report, an investment recommendation, or an offer or solicitation to buy or sell any security, and it does not consider any reader's objectives, financial situation or needs. No ticker, chart, heading or technical comment is a suggestion to buy, sell, hold or short. Figures come from third-party sources, are not independently verified, and may be incomplete, out of date or wrong. Online sentiment may include rumour, speculation or coordinated posting. Past performance and past price patterns do not predict future results. Investing involves risk, including the loss of capital. This article is not updated after publication. Laws differ by country; seek advice from a licensed professional in your jurisdiction before making any investment decision.