Continue Reading With a Free Account
Create a free account to see the full scanned list, new entries and chart analysis. No card needed.
Create Free AccountContinue With GoogleAlready registered? Sign in
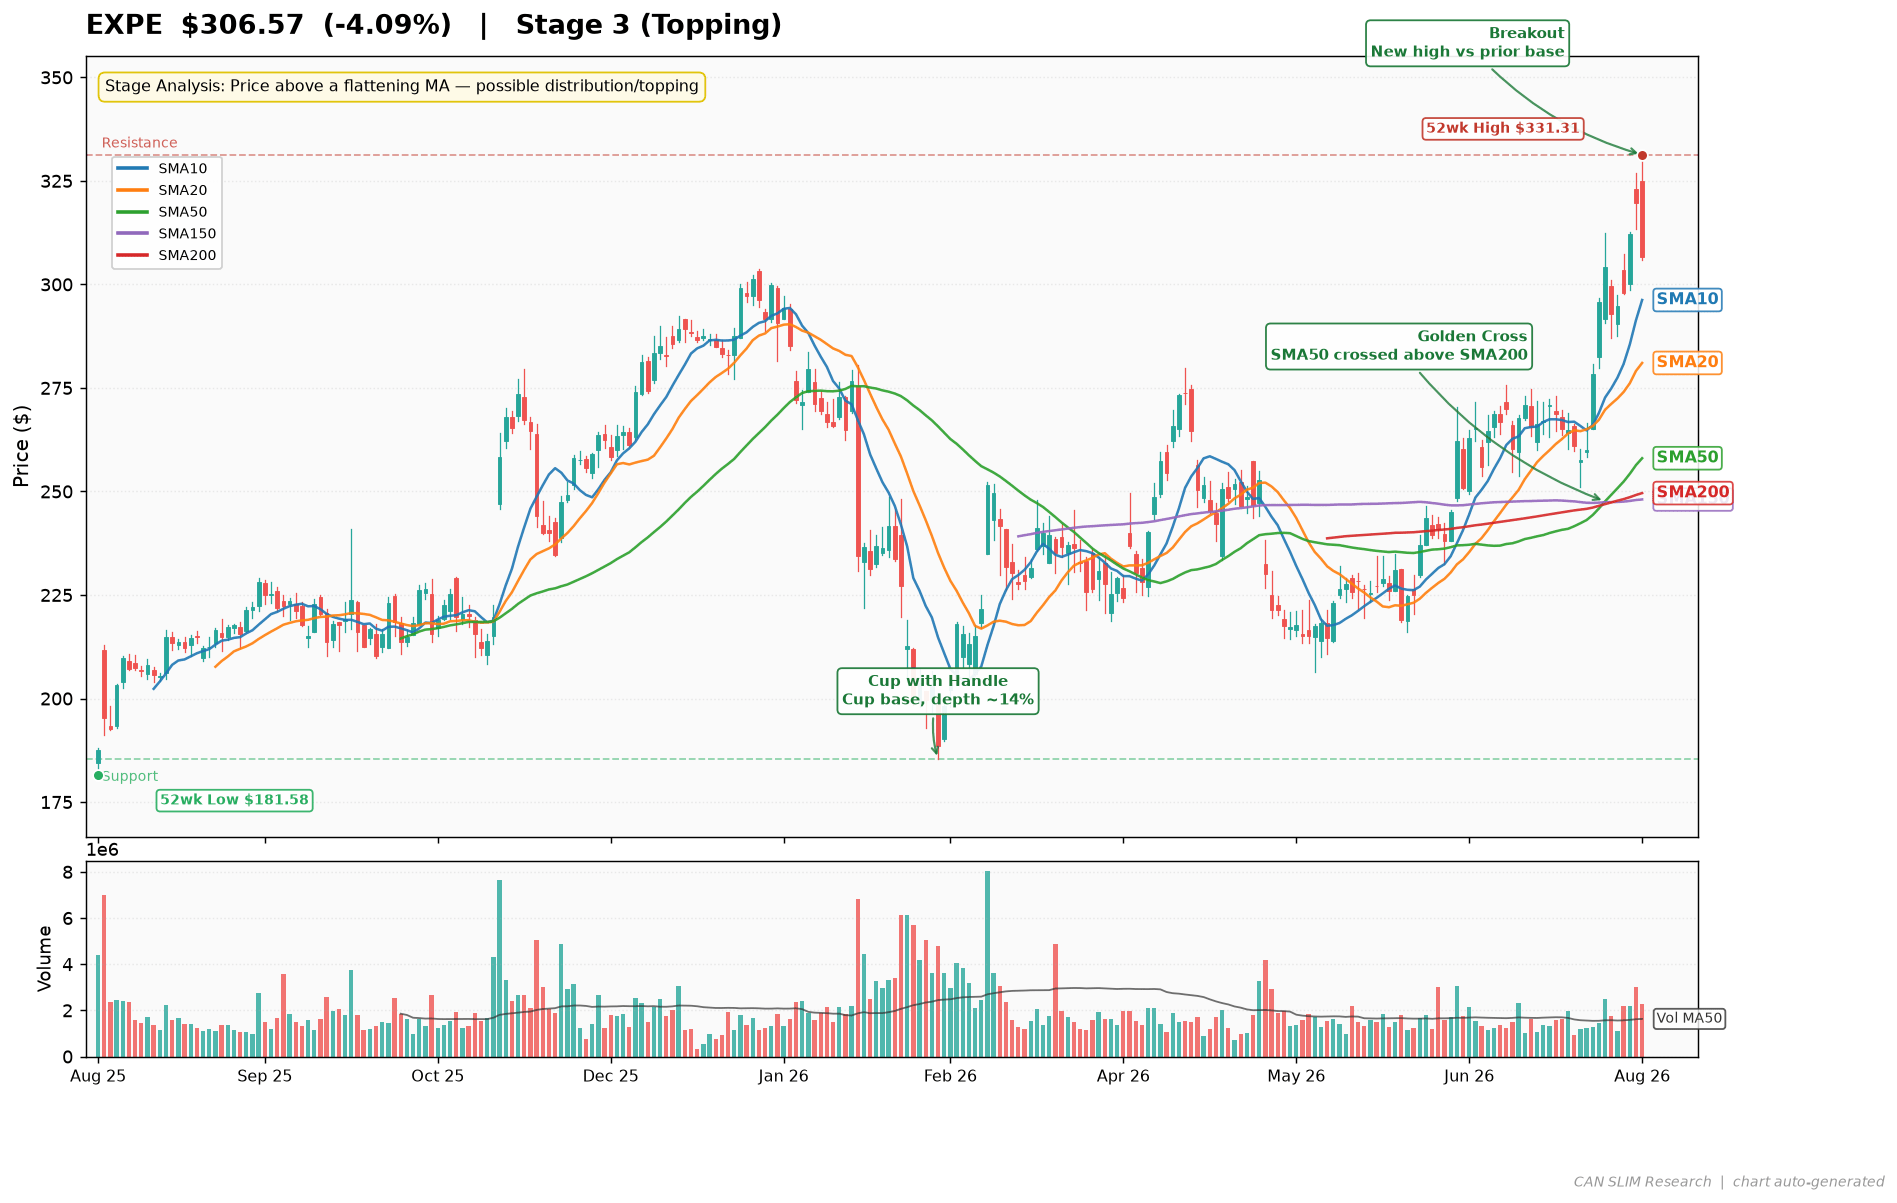
Expedia Group reported a headline-beating Q2 2026: revenue up 14% to $4.32 billion, adjusted EPS of $5.76 (a 10.4% beat), and adjusted EBITDA up 23% to $1.1 billion. Management raised full-year guidance and touted ‘the fifth consecutive quarter’ of top- and bottom-line outperformance. But beneath the polished numbers, a more troubling story emerges: the consumer B2C business—the company’s core—is decelerating, with bookings up just 8% versus 12% overall, and the company’s own guidance for Q3 implies a sharp slowdown to 5–8% revenue growth. Meanwhile, the EPS beat is flattered by a massive $900 million share repurchase in the quarter, which artificially boosted per-share earnings by roughly 8–10%.
1. the Lede and the Real Story
The real story is that Expedia is leaning on buybacks and B2B strength to mask a weakening consumer franchise, while Europe—a key market—is openly struggling. Investors should ask: is this a growth story or a financial-engineering story?
Inside the Full Analysis
- 🔒2. The Negative Space — What They Didn’t Say
- 🔒3. Script vs. Reality
- 🔒4. Evasion Tactics & The Hot Seat
- 🔒5. Excuses vs. Execution
- 🔒6. The CANSLIM Check
- 🔒The Bottom Line