Continue Reading
This article is for pass holders.
30-Day Pass$12.00One-time purchase · no auto-renewalBuy 30 DaysSave $24.00
365-Day Pass$120.00
Already a pass holder? Sign in · Continue with Google
In Short
Photronics beat Q3 estimates with $216M revenue and $0.50 EPS, but the Q&A reveals a fragile recovery: high-end IC is booming, yet FPD is stalling and guidance is cautious. Is this a real inflection or a dead-cat bounce? Read the full analysis.
The Lede and the Real Story
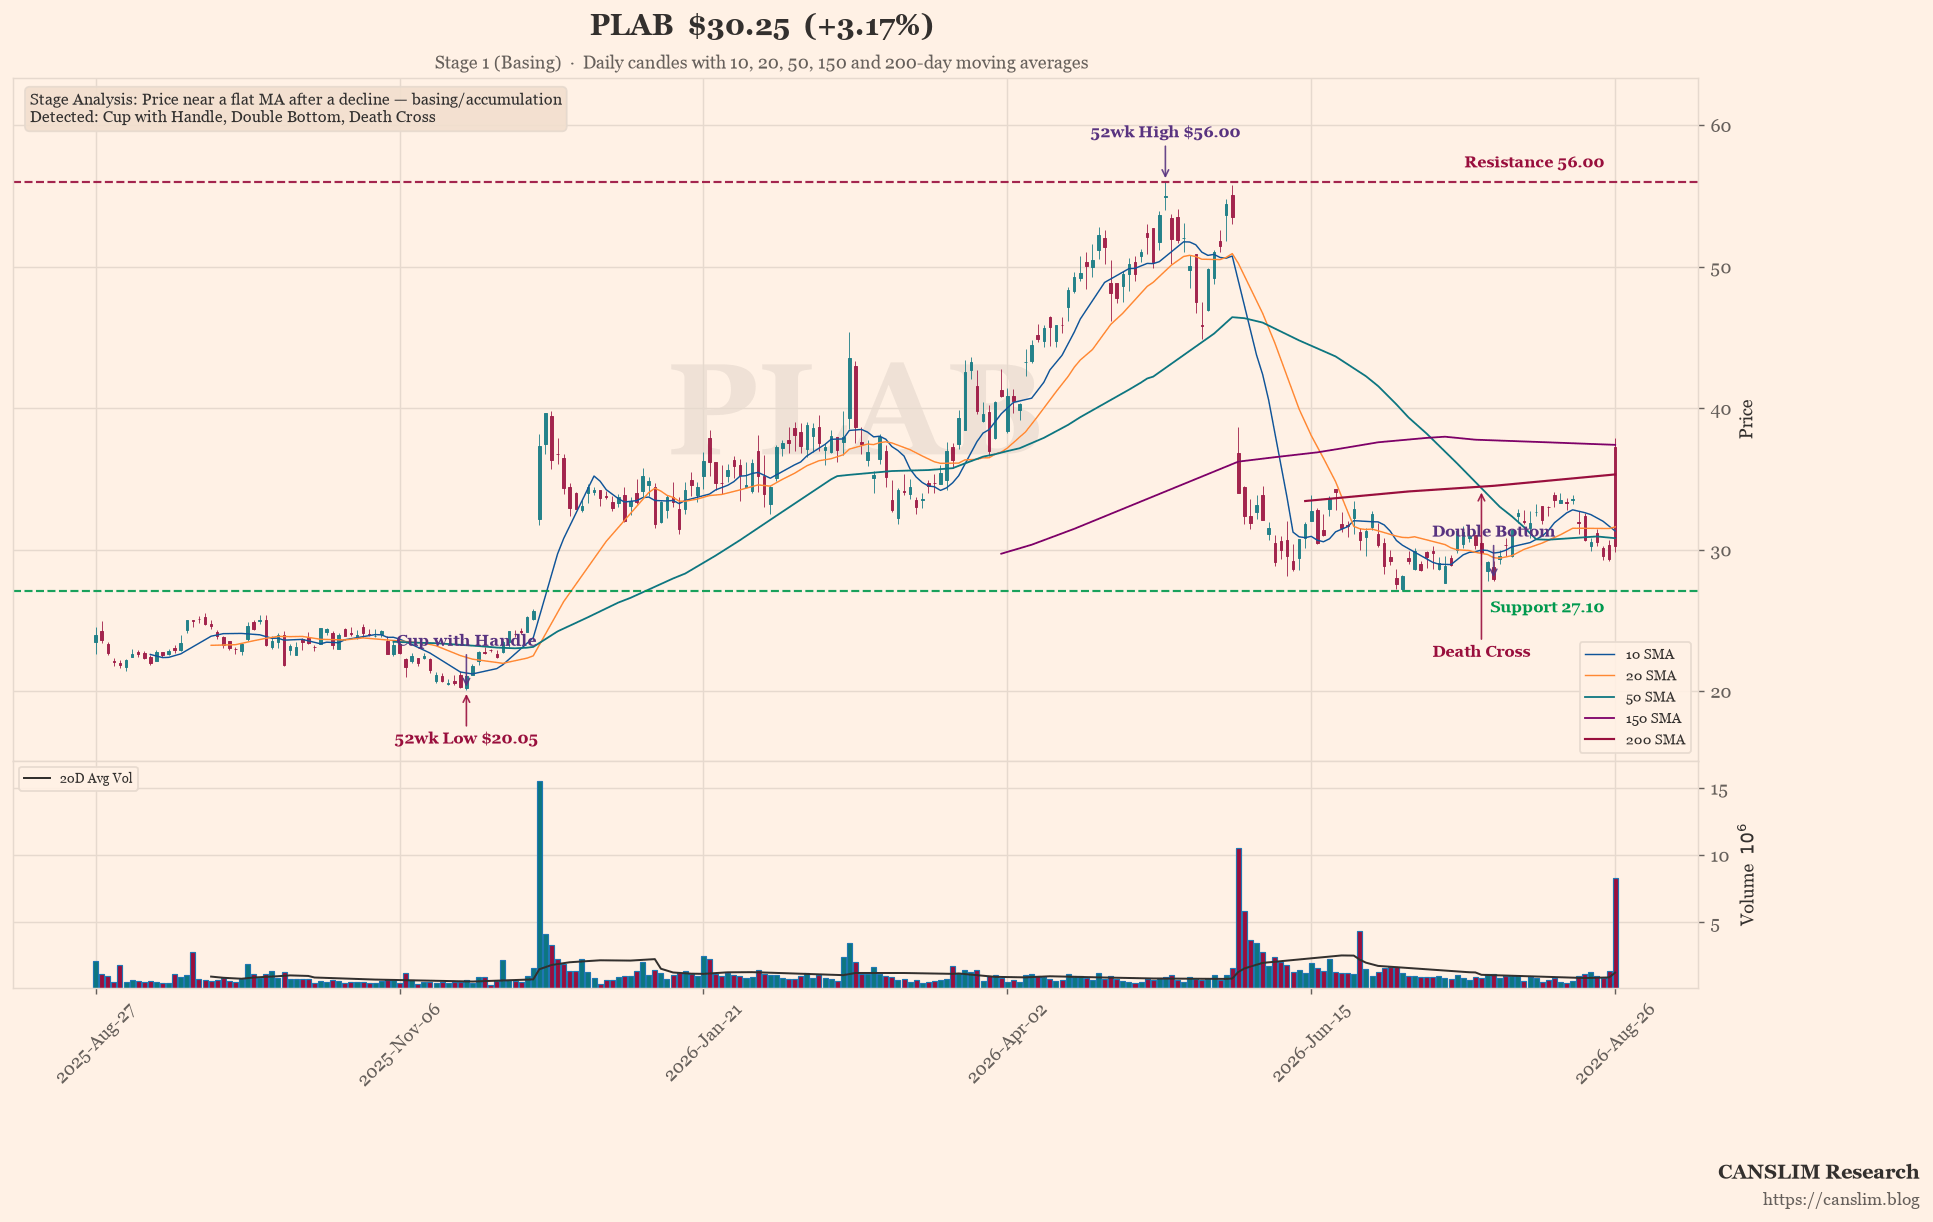
Photronics beat Wall Street’s numbers in fiscal Q3 2026—revenue of $216.05 million, up 3% year-over-year, and EPS of $0.50, a 24% surprise over the $0.40 consensus. Management framed the quarter as proof that the design-release delays that crushed Q2 are fading. But beneath the beat lies a more uncomfortable truth: the recovery is narrow, the guidance is cautious, and the Q&A exposed cracks in the narrative that the prepared remarks tried to paper over.
The real story is that Photronics is a two-speed company. High-end IC photomasks—the most advanced, profitable products—are booming, driven by AI demand. But the mainstream IC and FPD segments are stagnating or shrinking. Q2 revenue was flat year-over-year at $209.94 million, with IC down 5% and FPD up 13%. Q3’s 3% growth is a rebound, not a breakout. The company’s own Q4 guidance, while strong, still implies sequential growth of only about 2-4%—hardly the acceleration a beaten-down stock needs. Investors should ask: is this a genuine inflection, or a dead-cat bounce in a structurally challenged industry?
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion