Continue Reading With a Free Account
Create a free account to see the full scanned list, new entries and chart analysis. No card needed.
Create Free AccountContinue With GoogleAlready registered? Sign in
In Short
Nutex Health’s Q2 profit surge to $65.8M is an arbitration windfall, not operational growth—revenue fell 6% in H1. The stock jumped 6.67%, but the core business is shrinking. Can the legal wins last, or is this a mirage? Read the full breakdown.
The Lede and the Real Story
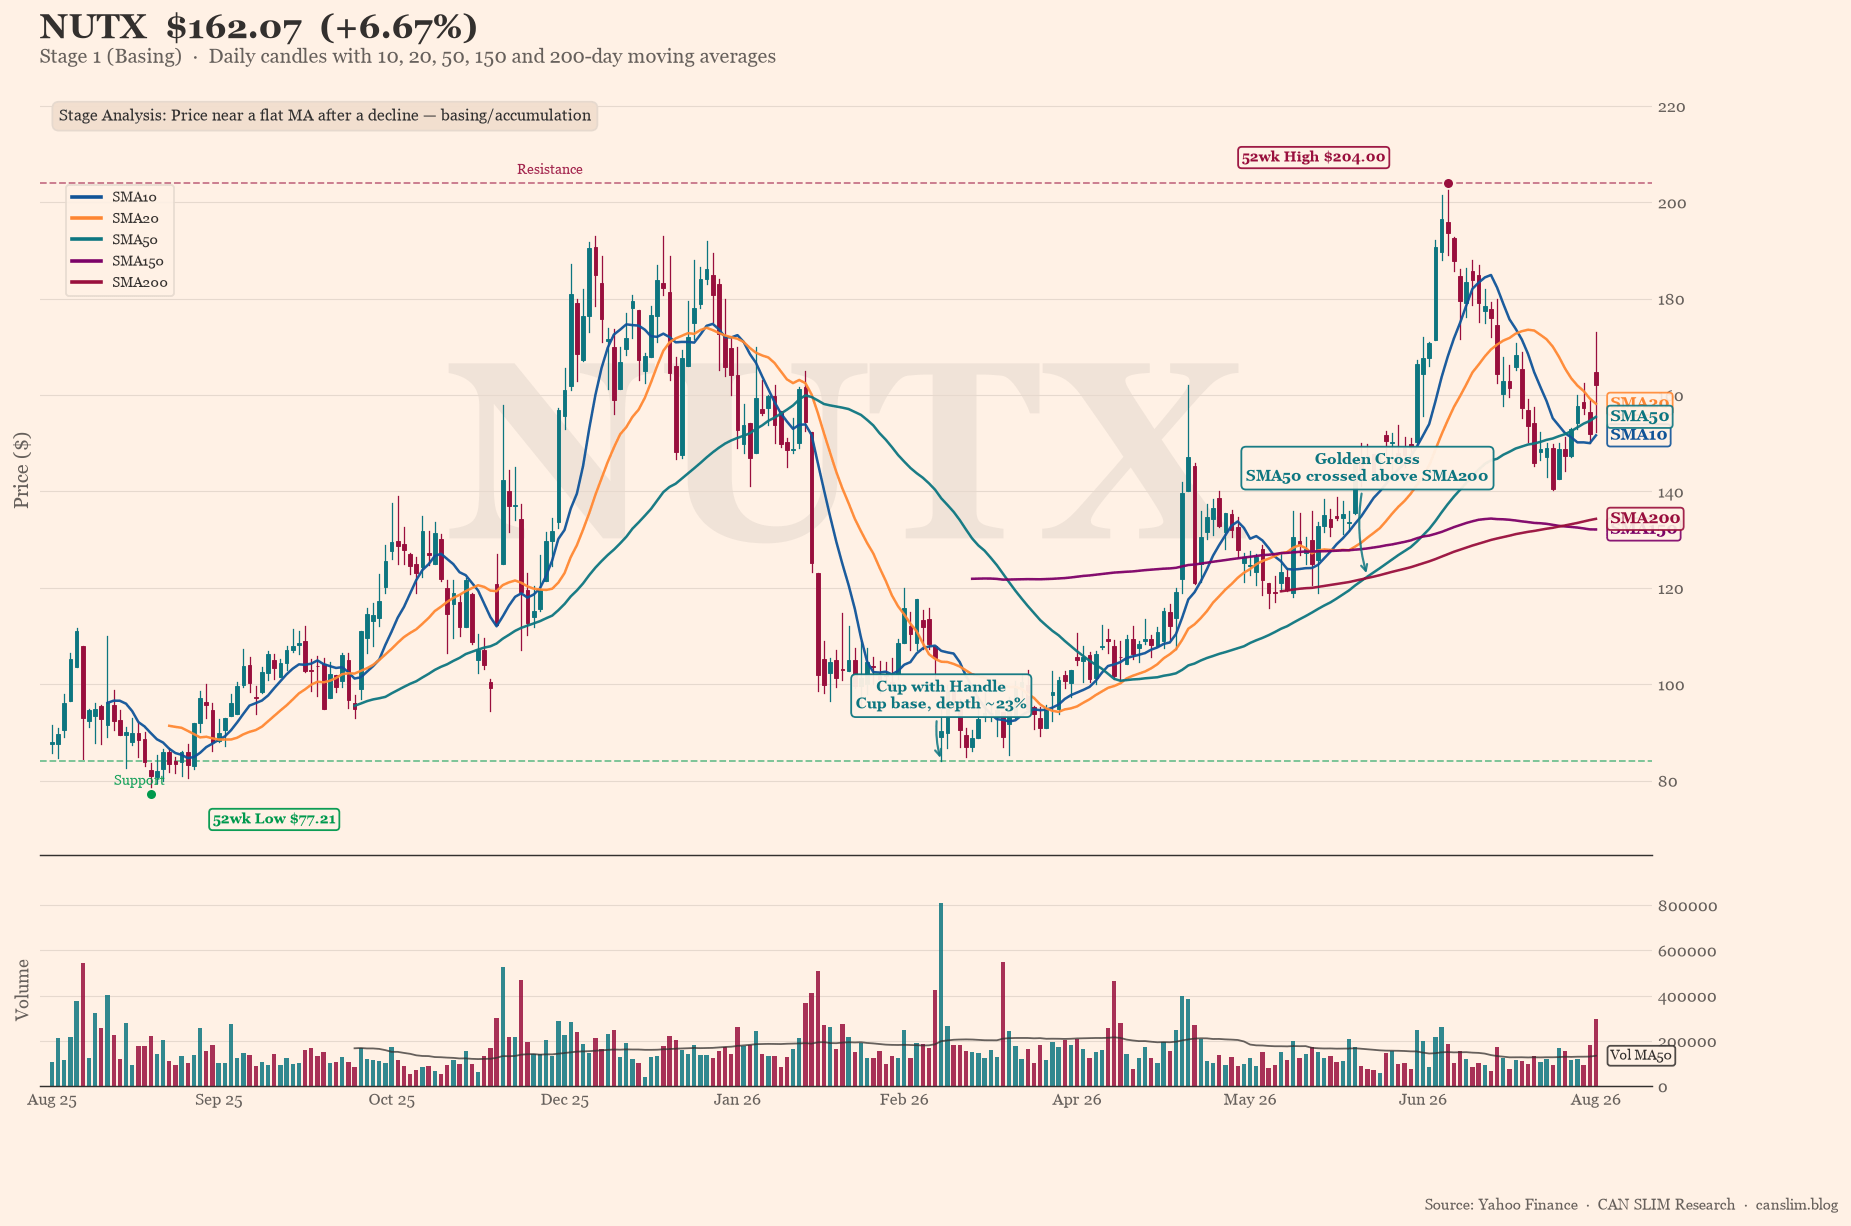
Nutex Health Inc. (NUTX) reported a headline-grabbing second quarter: net income of $65.8 million, a +89% earnings-per-share surprise versus analyst estimates, and a stock price that jumped 6.67% to $162.07. But strip away the arbitration gains and the story turns sharply. Total revenue for the first half of 2026 fell 6% year-over-year to $427.2 million from $455.8 million, and Q2 revenue of $210.75 million came in 2% below consensus. The company’s own CEO, Dr. Tom Vo, opened the call by touting ‘strong financial results,’ yet the numbers reveal a business whose core hospital operations are stagnating, with profitability increasingly dependent on a volatile, non-recurring source: arbitration awards against insurers.
The real story is that Nutex is trading growth for accounting wins. Management frames the quarter as ‘exceptional,’ but the underlying operational engine—patient volumes and hospital revenue—is sputtering. Adjusted EBITDA, a metric management itself flagged as pressured in Q1, remains under scrutiny. The market’s euphoric reaction to a profit number that is largely a function of legal settlements, not sustainable operations, is a classic red flag for investors who look beyond the headline.
Inside the Full Analysis
- 🔒The Negative Space — What They Didn’t Say
- 🔒Script vs. Reality
- 🔒Evasion Tactics & The Hot Seat
- 🔒Excuses vs. Execution
- 🔒The CAN SLIM Check
- 🔒Conclusion
Discover more from CANSLIM Research
Subscribe to get the latest posts sent to your email.